
Downloads
Download the report as a PDF
PDF | 744.85 KB
Executive summary
At the end of February, the government announced the most significant reform to the student loans system in England since at least 2012. The central planks of the reform are a lower earnings threshold for student loan repayments (cut to £25,000 and then frozen until 2026–27); a change in the future uprating of the earnings threshold from the rate of average earnings growth to the rate of RPI inflation; an extension of the repayment period from 30 to 40 years; and a cut in the maximum interest rate on student loans to the rate of RPI inflation (from a maximum rate of RPI inflation plus 3%). The new system will apply in full from the 2023 university entry cohort onwards, but the 2012 to 2022 entry cohorts (‘Plan 2 borrowers’) will also see significant changes.
Our initial analysis showed that:
- The announced reform package will transform the student loans system. Despite their name, pre-reform student loans mostly functioned as a graduate tax: a large majority of graduates were set to pay back 9% of their earnings above the repayment threshold for 30 years, irrespective of their student loan balance. Under the new system, this is no longer true: more than 70% of graduates can expect to repay in full and will receive no taxpayer-financed write-off of their loans.
- Graduates with lower-middling earnings will be hit the most by the changes with a lifetime loss of around £30,000. These earners enjoyed large taxpayer subsidies before the reform, but will have to pay back a much larger share of their loans under the new system.
- The highest-earning graduates will repay around £20,000 less as a result of the lower interest rate. These graduates would largely have paid back their loans in full even under the pre-reform system. For them, the lower interest rate translates into lower repayments overall, whereas the lower repayment threshold merely causes them to pay off their loans more quickly.
- The long-run taxpayer savings as a result of changes announced at the end of February is around £2.3 billion. The short-run impact on the budget deficit will be much larger at around £6.3 billion for the 2023 cohort. This is due to an accounting quirk.
- The system will also become substantially less generous for middle-earning graduates from the 2012–22 starting cohorts. These students are affected nearly as much by changes in repayment thresholds as students from the 2023 cohort onwards, but do not benefit from lower interest rates. Compared with the pre-reform system, 2022 starters stand to lose around £20,000.
In this briefing note, we present a more detailed analysis of the effects of the reform on students and the taxpayer – both on the 2012–22 entry cohorts and on entry cohorts from 2023 onwards – updated using the latest economic forecasts from the Office for Budget Responsibility. Throughout, we will emphasise the very large amount of uncertainty regarding the consequences of the reform. It is not clear how the announced changes will affect the behaviour of prospective students. And while we can say roughly who will gain and who will lose financially from the reform, it is hard to say exactly by how much. This is primarily because the impact crucially depends on what the earnings of current young people will be decades from now, which we cannot hope to predict precisely.
Key findings
- The results of our initial analysis hold up when we update our projections using the latest economic forecasts from the Office for Budget Responsibility and new data on graduate earnings. As a result of new OBR interest rate forecasts, we are now able to model the operation of the interest rate cap on student loans. However, all of these updates only have very small effects on the estimated impact of the reforms.
- The reform makes the higher education funding system in England even more of an outlier internationally. Even before the reform, England relied less on public funds for funding higher education than comparable countries. It is unpredictable how the low public subsidy will affect prospective students’ choices.
- The change in threshold indexing from average earnings growth to RPI alone is likely to cost middle-earning graduates from the 2022 and 2023 cohorts more than £10,000 over their lifetimes. For the taxpayer, this change alone is set to save substantially more than £2 billion in undiscounted real terms. It is somewhat concerning that such a significant change was not mentioned at all in the press materials announcing the reforms.
- Overall, the highest-earning borrowers will be better off under the system from 2023 onwards, and low-earning borrowers will be better off under the 2022 system. For 2022 school leavers, this means that incentives regarding whether to take a gap year will crucially depend on their expected future earnings.
- In the medium term, the reforms will result in graduates from the 2023 entry cohort repaying around £750 a year more from 2027–28 (when they typically start repaying loans) if earning more than £33,900. Graduates from earlier cohorts since 2012 earning more than £32,900 in 2026–27 (when the 2022 cohort will typically start repaying) will have to pay around £400 more than under the pre-reform system.
- The taxpayer will likely save more on loans to the 2022 cohort than on cohorts from 2023 onwards as a result of policy changes announced this year. This is because the cohorts from 2023 onwards will enjoy a lower interest rate on student loans, which will be costly for the taxpayer. In undiscounted terms, the reforms will likely cut the taxpayer cost by three-quarters for the 2022 cohort and by half for the 2023 cohort.
- Despite this, the short-term reduction in government borrowing from the reforms will be much larger for cohorts from 2023 onwards than for the 2012–22 cohorts. This is entirely due to the treatment of changes in the student loan interest rate in the national accounts. Paradoxically, lowering student loan interest rates lowers the initial cost of extending student loans, as it means a larger share of loans will be repaid with interest.
- The government’s policy choices have made the taxpayer cost of the student loans system less predictable. The change in the indexation of the repayment threshold ties the cost of loans more strongly to future earnings growth. As a result of the extension of the repayment term, graduate earnings in 40 years’ time will matter for student loans, and these earnings are even harder to predict today than earnings in 30 years’ time. The freeze in the repayment threshold means that the future cost of loans will hinge on the unpredictable path of inflation in the next few years.
1. Introduction
The scale of the changes to student loans announced at the end of February is difficult to overstate. The reform will, if fully implemented and kept in place, transform the student loans system from one where only a small minority of students go on to pay off their loans fully to one where most students will. This will move the system away from one where most students receive a taxpayer-financed write-off on their student loans to one where only the loans of lower-earning graduates will cost money for the taxpayer. Under the new system, most students will receive little or no net taxpayer funding for their higher education, as more than 70% will pay back their loans in full and government teaching grants are now negligible for the vast majority of subjects.1 Remarkably, there will also be large falls in taxpayer funding for borrowers from the 2012 to 2021 university entry cohorts, who presumably made their choice to take up a student loan under the legitimate expectation of very different repayment terms.2
This is a leap into the unknown. This year’s reforms will make the higher education funding system in England even more of an outlier internationally, as most other countries rely much more on the taxpayer for funding higher education. The UK already has the lowest share of public funding in tertiary education among OECD member countries at 25%, compared with an OECD average of around two-thirds (OECD, 2022).3
The consequences for prospective students’ choices are unpredictable. It is possible that the changes will encourage more students to study subjects with high financial returns, as a smaller part of the financial gain from a degree will in the future go towards higher student loan repayments and a larger part will benefit graduates themselves. This would be good news for the taxpayer, primarily because higher-earning graduates pay much higher taxes.
It is also possible that university enrolment will fall, as for those who are not expecting very high earnings after their degrees anyway, the changes will make university enrolment less financially attractive. Importantly, this is in stark contrast to the last major student loans reform in 2012, which only raised the costs of university for high earners, most of whom will enjoy large financial gains from university either way. For those expecting lower earnings, the 2012 reform actually led to similar or even lower expected student loan repayments (Crawford and Jin, 2014).
Besides this uncertainty about the effect of the reform on prospective students’ choices, the financial consequences of the reform are also very uncertain, even assuming that those choices will be unaffected. As we pointed out in our initial analysis (Waltmann, 2022b), graduates with lower-middling earnings will have to make much higher repayments under the new system, whereas those with the highest earnings will pay less due to the lower interest rate charged. The taxpayer will gain overall, but by much less than the predicted short-run impact on the government deficit would suggest. But exactly how much the taxpayer and different groups of graduates will gain or lose is impossible to say at this point.
The main reason for this is that what will happen to graduate earnings over the next 50 years is unknowable. Any prediction for future graduate earnings necessarily has to rely on data on the earnings of past graduates. But there is no guarantee that the mid-career earnings of graduates in Generation Z will look anything like the mid-career earnings of graduates in their parents’ generation.
The government’s policy choices have amplified this uncertainty. Changing the indexation of the repayment threshold from average earnings to RPI means that future graduates will now pay back a much larger share of their student loans if overall earnings growth turns out to be high than if it turns out to be low. As a result of the extension of the repayment period to 40 years, graduate earnings in the 2060s – which are impossible to predict with confidence today – will matter a lot for the 2023 entry cohort’s student loan repayments. Finally, the government has unwisely chosen to freeze the repayment threshold in nominal terms rather than lowering it outright and indexing from there. This means that – for no good reason – the future cost of loans will hinge on the unpredictable path of inflation in the next few years.
In order to give the reader some impression of the scale of the uncertainty, we will present the robustness of our findings to a scenario with much lower long-term earnings growth than the long-term growth rate currently predicted by the Office for Budget Responsibility (OBR). However, it should be kept in mind that this only captures one potential source of uncertainty. Importantly, it is also an open question whether future graduates will achieve the same high relative earnings in middle age as graduates from their parents’ generation.
A final wild card is RPI reform. All of our analysis in this briefing note assumes that the methodology for calculating the Retail Prices Index (RPI) will be reformed so as to coincide with the calculation of the Consumer Prices Index including owner occupiers’ housing costs (CPIH) from 2030 onwards. This seems very likely, but there is a pending legal challenge to the move, and the government’s own analysis of student loans reform does not take RPI reform into account. If RPI reform did not go ahead (and nothing else changed), the consequences for student loans would be broadly progressive: high-earning graduates would pay more (due to higher interest rates) and lower-earning graduates would pay less (due to a higher repayment threshold). Though – of course – were RPI reform not to go ahead, the government should reconsider the appropriateness of using the RPI to index thresholds such as those in the student loan system.
All of these uncertainties are likely dwarfed by uncertainty about future policy. Given the large scale and radical nature of the changes, there is a good chance that this or a future government will want to make further changes. If the past 10 years are any guide, the new student loans system will see multiple substantial reforms before the 2023 cohort’s loans are due to be written off in the late 2060s.4
2. Announced changes
On 24 February, the government announced a large number of changes to the student loans system. Some changes will apply only to university entry cohorts from 2023 onwards, some to the 2012 to 2021 entry cohorts, and some to all loan-eligible undergraduate students. Postgraduate loans and undergraduate borrowers who entered university before 2012 will be unaffected by the reform.
For new borrowers starting with the 2023 entry cohort, the earnings threshold above which student loan repayments have to be made will be lowered to £25,000 and frozen in nominal terms until 2026–27 inclusive. This is a large cut compared with what the threshold would otherwise have been in 2026–27. According to pre-reform (January 2022) policy, the threshold was set to rise to £28,551 in 2022–23 and would have risen further to around £32,900 in nominal terms by 2026–27.5 This means that a borrower earning above £32,900 will have to repay around £710 more in 2026–27 than in the absence of the reform.6
Second, the repayment period for new borrowers from 2023 will be extended to 40 years, up from 30 years at the moment. The repayment period starts in the April after students leave university education, which in many cases is not until students’ mid 20s as many do not start universities until their early 20s and/or pursue graduate study. As a result, many graduates from the 2023 entry cohort onwards can expect to be repaying their student loans until their mid 60s.
Third, the interest rate on student loans for the 2023 cohort will be cut from a maximum of RPI inflation plus 3% to RPI inflation only. Assuming that RPI reform goes ahead, this means that interest on student loans will be the rate of consumer price inflation from 2030 onwards – or in other words, that the real interest rate charged on student loans will be zero. This is a large and important change; it implies that from the 2030 entry cohort onwards, no student will pay back more in (CPI) real terms than they borrowed.
For ‘Plan 2 borrowers’, who started or will start university between 2012 and 2022, the repayment threshold will remain frozen at the current level of £27,295 for two more years until 2024–25, in addition to the one-year freeze announced at the end of January.7 This will amount to a substantial cut in the threshold compared with previous policy. In the 2024–25 tax year, the repayment threshold would have risen to around £31,200 in nominal terms without the freezes.8 This means that a graduate earning above £31,200 in 2024–25 will have to pay around £350 more towards their student loan than they would have done in the absence of this year’s policy changes.
For all borrowers from 2012 onwards, repayment thresholds will be adjusted in line with RPI rather than average earnings after the current freezes end. This means that graduates from the 2023 entry cohort will pay around £750 a year more in 2027–28 (when they typically start repaying loans) if earning more than £33,900. Graduates from earlier cohorts since 2012 earning more than £32,900 in 2026–27 (when the 2022 cohort will typically start repaying) will have to pay around £400 more than under the pre-reform system.
This change was not mentioned at all in the Department for Education’s press materials for the reform, and yet it could be hugely significant for the future of the student loans system. The reason is that, according to the OBR’s long-term projections, earnings will grow substantially faster than RPI. So, assuming that graduate earnings grow at roughly the same rate as earnings in the rest of the economy, this indexing change means that a growing share of graduate earnings at a given age will fall above the threshold. As a result, taxpayer subsidies will fall over time, with fewer and fewer graduates not paying off their loans before they get written off.
The difference between earnings growth and RPI inflation is set to be especially large following RPI reform in 2030. This is because RPI currently overstates consumer price inflation by around 0.9 percentage points on average, but will be an unbiased estimate of consumer price inflation from 2030 onwards. According to the OBR’s projections, average earnings growth is set to outpace consumer price growth by 1.8 percentage points per year in the long run.
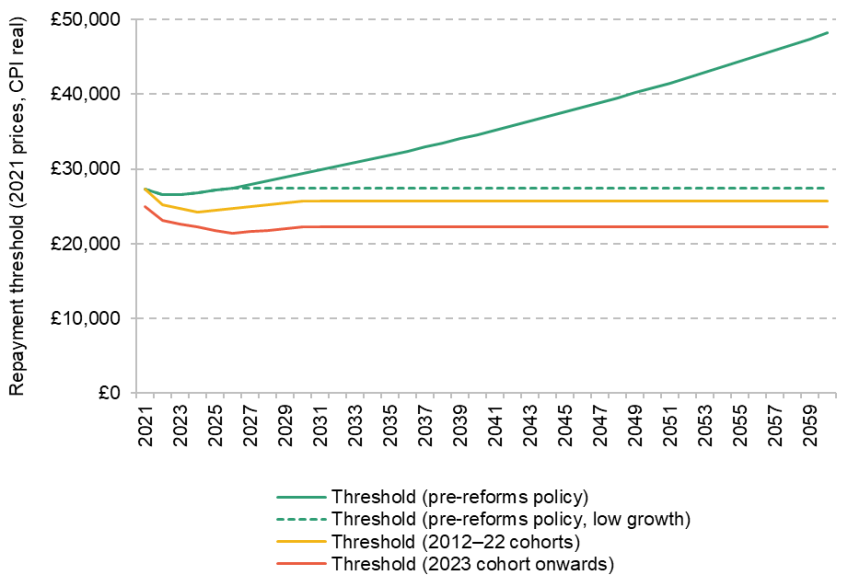
Figure 2.1 illustrates the path of the student loan repayment threshold in 2021 CPI real terms, under pre-reform (early January 2022) policy, for 2012–22 entrants, and for entrants from 2023 onwards, based on March 2022 OBR forecasts. For pre-reform policy, we also show a ‘low growth’ scenario where there is no growth in real earnings from 2027. (While this may seem excessively pessimistic, it is roughly in line with the experience of the last 15 years.)
The graph illustrates that the change in threshold indexing is set to lead to an enormous gap opening up in the coming decades between what the threshold would have been under pre-reform policy and what it will be under the new policy. This will already have large effects on students in the 2023 entry cohort, but effects will be even larger for future cohorts. However, this is entirely contingent on there being real growth in average earnings: if average earnings would have grown at the same rate as RPI anyway, the indexing change will (of course) have no effects at all. Furthermore, policy might well change: if there is substantial real earnings growth, a future government may well decide to increase the repayment threshold in real terms.
Figure 2.1. Changes to path of the student loan repayment threshold (CPI real terms)
Lastly, the cap on tuition fees will stay frozen in nominal terms at £9,250 for two additional years until the 2024–25 academic year. As shown below, this only has a very small effect on students and the taxpayer, but constitutes a further significant cut in university resources. The real value of maximum fees has already fallen around 16% in CPI real terms in the past 10 years, and is set to fall by another 10% by 2024–25. This will increase the financial pressure on universities substantially.
In addition to these substantive changes, there have also been major changes to the government accounting methodology for student loans that were announced at the same time as these reforms. The most important change is that the discount rate that the Department for Education (DfE) uses to value student loans was changed from RPI + 0.7% to RPI minus 1.1%. This means that, after adjusting for RPI inflation, loan repayments are now valued higher if they are made farther in the future. As a large share of student loan repayments will occur decades into the future, this seemingly technical change matters a lot. For someone starting university at age 18, their repayments in their 50s will be valued roughly twice as much with the new discount rate as with the old one.
While this adjustment to discount rates may well be justified in the current low interest rate environment, it increases the uncertainty attached to student loan modelling. Statements about the financial cost of loans will hinge crucially on student loan repayments in the distant future, which are impossible to predict accurately. For ease of interpretation, we focus on undiscounted numbers in this briefing note. For comparison with other work and DfE publications, we also report figures with discount rates of RPI + 0.7% and RPI – 1.1%. A discount rate of RPI + 0.7% has the further attraction of being roughly equal to long-run expected nominal GDP growth. This arguably makes it a reasonable discount rate for the public sector as, with a constant tax burden, tax revenues would also grow in line with nominal GDP.
A second accounting change is the (well-hidden) announcement from the government that discount rates are to be adjusted in line with RPI reform, so that the nominal discount rate remains unchanged in expectation. As a result, the DfE’s discount rate for student loans from 2030 onwards will be RPI minus 0.2% – provided that RPI reform goes ahead. In effect, this means that the government has – very sensibly – decided that discounting should at bottom not be relative to RPI but relative to true consumer price inflation.
We reflect this change below. All of our discounted figures are discounted in such a way as to cancel out the expected impact of RPI reform. So, for example, figures that we report as discounted by ‘RPI – 1.1%’ are discounted by unreformed RPI – 1.1% up until 2030 and discounted at reformed RPI – 0.2% (i.e. CPIH – 0.2%) thereafter. (This is equivalent to discounting by unreformed RPI – 1.1% throughout the forecast period.)
Finally, it is important to consider the policy backdrop against which these reforms to student loans occur. Most importantly, as we pointed out in February (Waltmann, 2022a), maintenance support for students is falling fast as a consequence of unexpectedly high inflation. According to March 2022 OBR projections, this will amount to a cut of around 11% (or around £100 per month) for students from the poorest families (who are entitled to the largest loans), relative to what support would have been had inflation projections been correct. Cuts will be even larger for students from slightly higher-earning families, as the parental earnings threshold for eligibility to maximum maintenance loans has been frozen in nominal terms since 2008.9
Box 2.1. What is RPI reform and why does it matter for student loans?
RPI reform refers to a decision by the UK government in November 2020 to adjust the methodology for calculating the Retail Prices Index (RPI) in 2030, from which point it will be calculated in the same way as the Consumer Prices Index including owner-occupiers’ housing costs (CPIH). CPIH inflation is typically around 0.9 percentage points lower than RPI inflation calculated using the traditional methodology.
This change will have two effects on the cost of student loans, provided the system now remains unchanged until 2030. First, it will have a real effect on the interest rate charged on student loans, as that interest rate is linked to RPI. As CPIH inflation is typically less than RPI inflation, this will reduce the amount of interest accrued on student loans and thus the cost of student loans for borrowers who pay off their loans in full.
Second, RPI reform will affect the rate at which the earnings threshold for student loan repayments is uprated. As part of its student loan reform package announced in February, the government announced that the repayment threshold will in the future be indexed to RPI rather than average earnings. As CPIH inflation is typically less than RPI inflation, this means that from 2030, the earnings threshold for student loan repayments can be expected to rise more slowly. This will increase the cost of student loans for borrowers with (lower) middling earnings, who will earn above the threshold so will need to repay more each year, but who may not repay enough to clear their loans (or at least not without RPI reform).
There is also a third way in which RPI reform might have affected student loan accounting, which we emphasised before (Farquharson et al., 2021). Some measures of the cost of spending on student loans such as the DfE’s RAB charge are constructed by discounting future repayments by RPI plus or minus a discount rate. As CPIH inflation is typically less than RPI inflation, it was reasonable to assume that RPI reform would reduce the discount rate and thus the cost of student loans in accounting terms.
However, the government has now clarified that this is not going to happen. Discount rates are to be adjusted along with RPI reform, so that the expected discount rate relative to CPIH inflation remains unchanged. As a result, RPI reform will be neutral with regard to these accounting measures.
3. Impact on students
The announced student loan reform package will have a large effect on the lifetime earnings of many student loan borrowers. Some borrowers are set to lose tens of thousands of pounds as a result of the reform, whereas others stand to gain. Besides the university entry cohort, the main factor governing a borrower’s gains or losses is how much they earn after graduation. For the 2012 to 2022 cohorts of university entrants, nearly all borrowers will lose from the reform, with graduates with middling earnings set to lose the most.10 For the 2023 cohort onwards, graduates with lower-middling earnings will lose the most, whereas the highest earners stand to gain substantially.
Figure 3.1 shows the impact of the reform package on the net lifetime earnings of the 2022 cohort of entrants (effects on earlier cohorts will be similar, albeit somewhat smaller). Middling earners will lose up to £20,000, whereas those with the highest and lowest earnings will be nearly unaffected. This is because nearly the entire impact of the reform comes from changes to the repayment threshold, with the change in threshold indexing being the biggest single factor. The repayment threshold is not very important for borrowers with the lowest lifetime earnings, as they will rarely have earnings above the threshold. The highest earners would mostly have paid off their loans either way, so a lower repayment threshold only means that they will pay off their loans more quickly, with little impact on overall student loan repayments.
One small additional impact of the reform comes through its effect on tuition fees. As seen in Figure 3.1, the freeze in maximum tuition fees will have hardly any impact on graduates in the bottom half of the lifetime earnings distribution, as these graduates are unlikely to pay off their loans either way; it will have a small positive impact on high-earning graduates, who are likely to pay off their loans. This contrasts with government rhetoric, which has emphasised the role of the fee freeze in ‘reducing the real cost’ of higher education for students.11 The freeze will typically make no difference at all to borrowers in the lower-earning half of graduates, and only a modest difference to the rest.
While the distributional impact of the reform displayed in Figure 3.1 will be broadly accurate under a wide variety of scenarios for how the economy develops over the coming decades, the gains and losses may well end up being substantially higher or lower. A particular source of uncertainty is the change in threshold indexing, whose effect hinges crucially on overall earnings growth as discussed in the previous section. As shown in Figure A.1 in the appendix, earnings losses due to the reform for middling earners might be much smaller at less than £7,000 in a low growth scenario.
Figure 3.1. Impact of reforms on the 2022 entry cohort
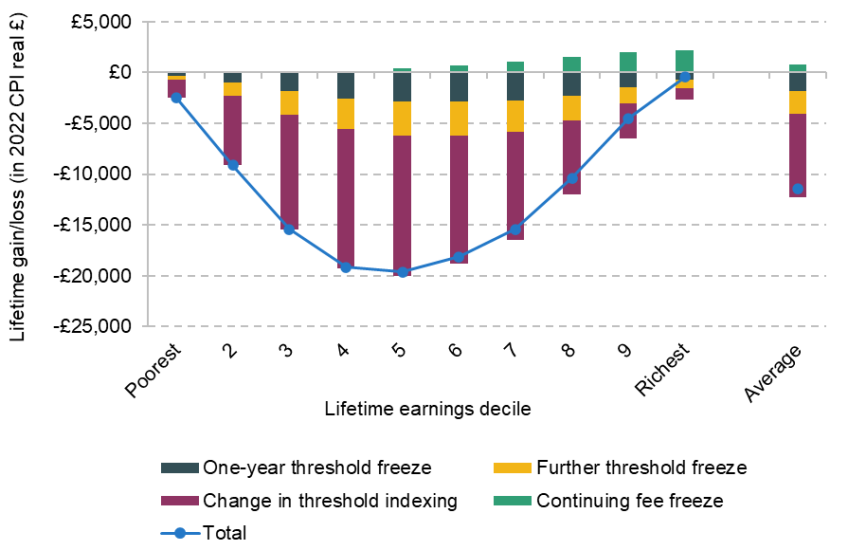
Note: The split into the impact of different policies depends on the order in which policies are added. The order shown is: one-year threshold freeze, further threshold freeze, change in threshold indexing and continuing fee freeze.
More generally, different modelling assumptions can lead to somewhat different conclusions about the likely impact of the reform. An important example is differences between the estimates of the impact of the reform package reported in this section and the Department for DfE’s own estimates (Department for Education, 2022a). According to these estimates, the impact of the reform will be slightly smaller and more skewed towards higher earnings. While there are a number of differences between these estimates and ours that limit their comparability, the main difference is likely to be the DfE’s more pessimistic forecast for graduate earnings over the life cycle.
Figure 3.2 shows the impact of the reform package on the 2023 entry cohort, which will roughly be representative of the following cohorts as well. The threshold changes and the extended repayment term all increase the lifetime cost of loans by large amounts, especially for middle-earning graduates. The logic here is the same as above: the lowest-earning graduates are nearly unaffected because they repay little anyway, and the highest earners are nearly unaffected because the lower threshold merely means that they repay more earlier (the extended repayment period will in most cases not affect them at all, as they will typically pay off within 30 years).
Figure 3.2. Impact of reforms on 2023 entry cohort
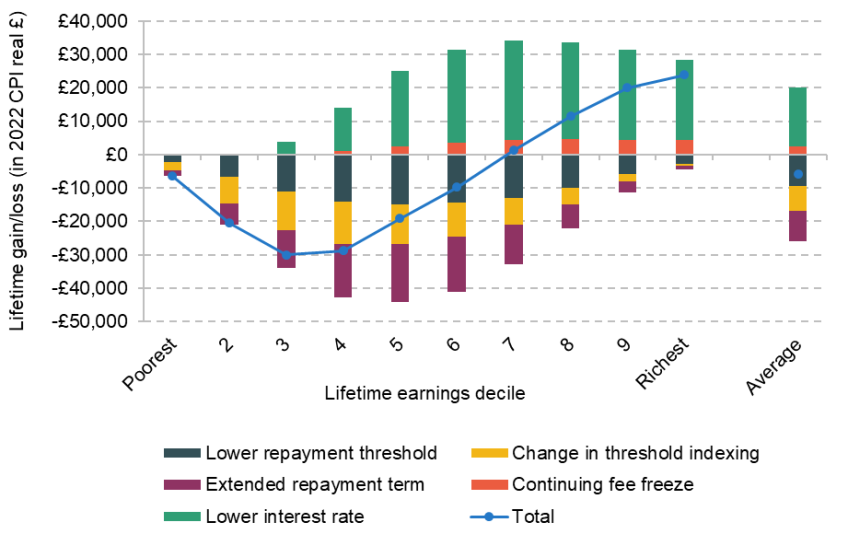
Note: The split into the impact of different policies depends on the order in which policies are added. The order shown is: lower repayment threshold, change in threshold indexing, extended repayment term, continuing fee freeze and lower interest rate.
For all except the lowest earners, these changes are partially or more than counterbalanced by the freeze in maximum fees and – much more importantly – the cut in the student loan interest rate. On the whole, student loan reform will increase the cost of loans for lower and middling earners. The net loss will be largest for graduates with lower-middling earnings, who stand to lose around £30,000 on average over their lifetimes from the reforms. On the other side of the spectrum, the highest-earning graduates stand to benefit by more than £20,000.
Again, the shape of these gains will be broadly accurate, but the precise numbers will depend on how the economy evolves. Figure A.2 in the appendix shows that in a low growth scenario, somewhat fewer graduates would benefit from the reform, but the losses would be somewhat smaller at less than £20,000 and slightly more skewed towards the middle of the graduate earnings distribution. In any event, the losses for some graduates will be large: even losses of £20,000 are likely to make a substantial difference to graduates’ lives.
These large and differential impacts mean that there are likely to be substantial differences in student loan repayments based on students’ university entry cohort. While most prospective students will not have a choice regarding which loan system applies to them, many of those sitting A levels this year will, as many could choose between entering university this year or waiting until next year.
Figure 3.3. Impact of ‘cancelling a gap year’ (2022/2023 entry cohorts)
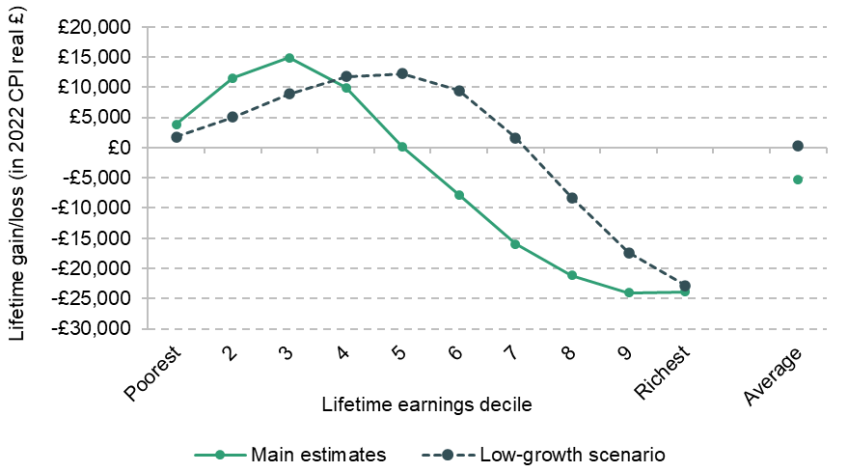
Note: Graph shows the difference between 2022 entry cohort and 2023 entry cohort repayments by earnings decile. The implicit assumption is that taking/cancelling a gap year has the same effect on earnings as being born one year later/earlier.
This has led some to conclude that those sitting A levels this year could save large sums by entering university this year rather than next, and hence that there might be a ‘mass cancellation of gap years’ (Morgan, 2022). Indeed, if policy does not change (and that is a big if), those who expect to be lower-earning graduates may be able to save substantial sums in student loan repayments by cancelling gap years (see Figure 3.3). In contrast, the highest-earning graduates will be much better off doing a gap year. For those with average earnings for graduates or just above, which option will lead to lower lifetime repayments is impossible to say even if policy could be expected to remain constant.12 As shown in Figure 3.3, one crucial factor will be overall earnings growth.
4. Impact on taxpayers
The impact of the student loan reform package on taxpayers is subject to an additional complication. In contrast to the impact on students, the impact on taxpayers is by convention measured in discounted terms, i.e. weighting student loan repayments differently depending on when in the life cycle they are received. Different discount rates can lead to very different conclusions regarding the overall cost of the student loans system and the consequences of any reforms.
Table 4.1. Taxpayer cost of student loans in £ (in % of outlay)
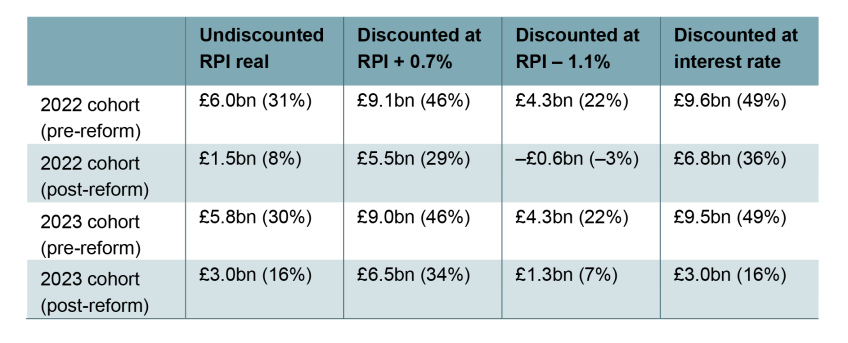
Note: ‘Pre-reform’ means with policy as announced by January 2022. Following new government guidance (Department of Health and Social Care, 2022), discount rates in the second and third columns are adjusted upwards by 0.9 percentage points after 2030 to achieve a constant discount rate relative to CPI despite RPI reform (see Box 2.1). Following standard DfE practice, loan outlay is not discounted.
Table 4.1 illustrates this by showing the cost of student loans under the pre-reform system and the post-reform systems for the 2022 and 2023 cohorts, discounted using four different discounting schemes. The first column shows the cost in undiscounted RPI real terms. According to this measure, the long-run taxpayer cost of the pre-reform student loans system was going to be £6.0 billion for the 2022 entry cohort and £5.8 billion for the 2023 cohort, or in each case around 30% of initial outlay. After the reform, this cost falls radically by three-quarters for the 2022 cohort to £1.5 billion or 8% of initial outlay. This is substantially bigger than the reduction for the 2023 cohort, for which the taxpayer cost in undiscounted RPI real terms will be cut not quite in half to £3.0 billion.13
With a higher discount rate at RPI + 0.7%, the discount rate that the Department for Education used up until the announcement of the reform, the cost of the student loans system looks much higher and the impact of the reform package is smaller. With the DfE’s new lower discount rate of RPI – 1.1%, in contrast, the cost of the student loans system is smaller (and indeed negative for the 2022 cohort after the reform) and the impact of the reform is somewhat larger.
The final column shows the cost of loans and the impact of the reform when the discount rate used is the interest rate charged on loans. The significance of this discounting scheme is that it is used in accounting for student loans in the national accounts. The taxpayer cost of student loans measured by discounting at the interest rate is the amount the government has to recognise as a cost in the government budget when issuing student loans under ONS accounting rules, and which will therefore count towards the budget deficit (PSNB). Intuitively, this amount is the part of the student loan that will not be paid back with interest.
On this measure, the reform saves around £6.5 billion in spending on the 2023 university entry cohort and £2.8 billion on the 2022 entry cohort, whereas on all other measures shown, the reform saves more on the 2022 cohort. The reason is that the reform package changes the interest rate on loans for the 2023 cohort and thus the discount rate used to calculate the cost under this measure. Paradoxically, this means that lowering student loan interest rates is both a giveaway to students and reduces the initial cost of extending loans that counts towards the deficit, because the lower discount rate outweighs the increase in the true taxpayer cost of loans.
This is a known quirk in the national accounts treatment of student loans, which we pointed out before (Farquharson et al., 2021).14 This quirk has now allowed the Chancellor to gain a lot more fiscal headroom with the February reform package than would have been warranted in undiscounted terms. However, it should not be concluded that the deficit impact of student loans now understates their true cost; indeed, this impact is now the same as our preferred measure of the long-term cost of student loans by construction (as the interest rate on loans will be the rate of RPI inflation for all borrowers from the 2023 cohort onwards).15 Instead, given that interest rates on student loans for the 2012–22 cohorts exceed reasonable discount rates, the initial deficit impact of student loans arguably overstates their true taxpayer cost for pre-2023 cohorts.
Figure 4.1 shows how the predicted cost savings (measured in undiscounted RPI real terms) are split between the different parts of the reform for the 2022 entry cohort. All parts of the policy reduce the cost of the system; the change in threshold indexing has by far the largest effect. Compared with changes relating to the repayment threshold, savings from freezing tuition fees are minor.
Figure 4.1. Taxpayer cost of student loans in undiscounted RPI real terms, 2022 cohort
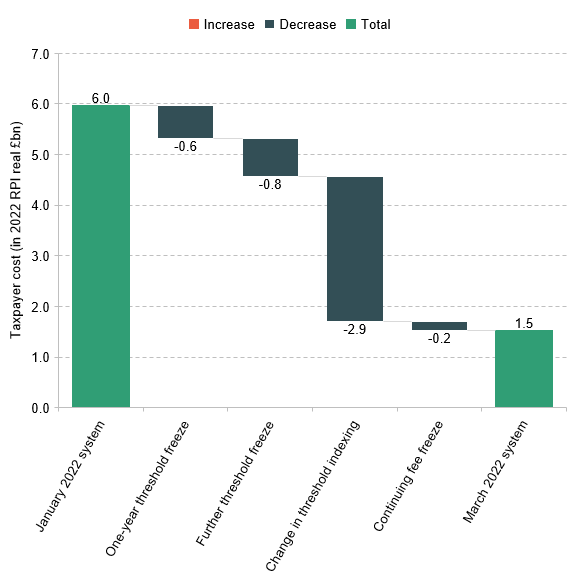
Note: The split into the impact of different policies depends on the order in which policies are added.
Figure 4.2. Taxpayer cost of student loans in undiscounted RPI real terms, 2023 cohort
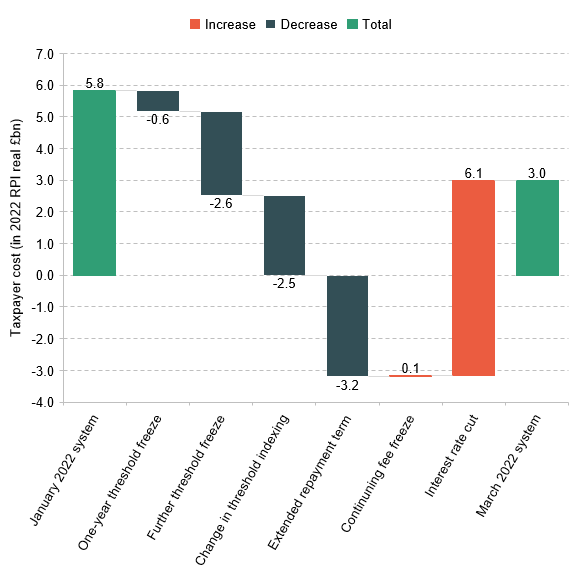
Note: The split into the impact of different policies depends on the order in which policies are added.
Figure 4.2 shows the same for the 2023 cohort. Again, threshold reductions have a large effect, as does the extended repayment term. Curiously, the freeze in maximum fees actually increases the taxpayer cost (or rather, reduces the taxpayer benefit) of student lending. This is because without the cut in the interest rate, the reform package would turn student lending into a profitable business for the taxpayer in undiscounted RPI real terms, which would be rendered slightly less profitable by a smaller loan size. Finally, the cut in the interest rate is very costly, leading to the final taxpayer cost of £3 billion.16
Like the impact on students, the impact on taxpayers also hinges on forecasts of earnings in the distant future and is thus subject to significant uncertainties. Table 4.2 gives some sense of this, by showing the impact of the reform package in a low growth scenario. Predicted taxpayer savings as a result of the reform are smaller, especially for the 2022 entry cohort. Notably, estimated savings in spending on the 2023 cohort are larger than for the 2022 cohort on all measures in this scenario.
Table 4.2. Taxpayer cost of student loans in £ (in % of outlay): low growth scenario
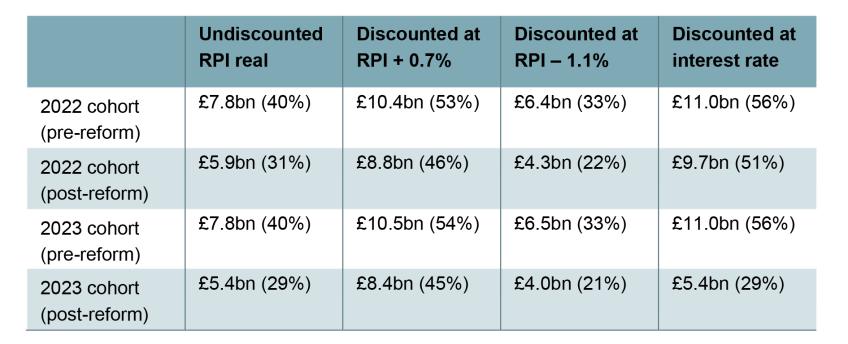
Note: ‘Pre-reform’ means with policy as announced by January 2022. Following new government guidance (Department of Health and Social Care, 2022), discount rates in the second and third columns are adjusted upwards by 0.9 percentage points after 2030 to achieve a constant discount rate relative to CPI despite RPI reform (see Box 2.1). Following standard DfE practice, loan outlay is not discounted. ‘Low growth’ means no earnings growth relative to CPI from 2027 onwards.
5. Conclusion
This year’s student loan reform will open a new chapter for higher education funding in England. Much more so than even the Augar Review (Augar, 2019) envisioned, students will in the future have to pay for their own education. They will be able to draw on taxpayer support while they are studying, but this will in most cases have to be paid back in full in later life.
These changes are a leap into the unknown. It is unknowable today how this reform will affect the choices of prospective students. It is also impossible to quantify the fiscal and distributional consequences of the reform precisely, because even more will hinge on what graduate earnings will be in decades’ time than under the current system. We do know, however, that the reform will hit those with middling and lower-middling earnings the most, who under the pre-reform system looked set to enjoy large taxpayer subsidies. In contrast, graduates with the highest earnings from the 2023 cohort onwards will benefit, as for them the effect of lower interest rates will dominate. Taxpayers will also gain, but not by as much as the headline impact on the deficit might suggest.
However, there are good reasons to take even these rough projections about long-term impacts with a grain of salt, because it is also unknowable how long the new system will stay in place. Prospective students would be well advised to take note of the ease with which the government has just changed repayment conditions for the 2012 to 2021 cohorts, who may have taken up their student loans with the legitimate expectation of very different repayment terms. This suggests that future governments may well change conditions again – potentially with very different implications for gains and losses.
For now, the only impact of the reforms that is virtually certain is that graduates from the 2012 entry cohort onwards will pay more towards their student loans in the next few years due to the freeze in the repayment threshold. This will squeeze the budgets of these graduates at a time when many will be saving for a down payment on a house or starting a family. It constitutes a further hit to the real incomes of these graduates on top of the large rise in the cost of living, the freeze in the personal allowance, and the hike in National Insurance rates.
In the end, a more important question than who will gain or lose how much from the reforms is whether the reforms improve the system. One clear improvement is the reduction in sky-high interest rates for students from the 2023 cohort onwards. While this change will almost entirely benefit higher earners, it will reduce distortions and increase fairness between high earners who have taken out loans and those whose parents paid for their education. The change could also increase trust in the system, as the new student loans system will be a good deal for all students, including those who go on to become high earners.
On the other hand, limiting public higher education funding to a minority of low-earning students arguably makes the system worse. Partly as a result of the distortions created by the tax system, this may well lead some students not to attend university even when this would be socially optimal. However, subsidies in the student loans system are not the only way the government can counteract these distortions and make higher education more attractive. Other tools include grants to students or universities and adjustments to the tax system (for example, the government could make student loan repayments tax-deductible for future cohorts).
Finally, there is no justification for nominal freezes at any time, but they are especially problematic at the moment. Because inflation is currently high and unpredictable, the repayment threshold may well be reduced by more (or less) than the government intended. This introduces an unnecessary element of uncertainty into the student loans system, and the government might well have to take corrective action in a few years. It would have been much better to reduce the repayment threshold to its intended value and then uprate it with the government’s preferred long-term indexing rule.
Acknowledgements
The author gratefully acknowledges the financial support of the Nuffield Foundation (reference EDO /FR-000022637), the ESRC Centre for the Microeconomic Analysis of Public Policy (ES/T014334/1) at IFS and an IAA mini-bid grant (reference ES/T50192X/1). The project has been funded by the Nuffield Foundation, but the views expressed are those of the author and not necessarily the Foundation. Visit www.nuffieldfoundation.org.
References
Augar, P., 2019, Independent panel report to the Review of Post-18 Education and Funding. https://assets.publishing.service.gov.uk/government/uploads/system/uploads/attachment_data/file/805127/Review_of_post_18_education_and_funding.pdf.
Britton, J., van der Erve, L. and Waltmann, B., 2019, Higher education funding: more change to come?. Institute for Fiscal Studies (IFS), Briefing Note 266, https://ifs.org.uk/publications/14588.
Crawford, C. and Jin, W., 2014, Payback time? Student debt and loan repayments: what will the 2012 reforms mean for graduates?. Institute for Fiscal Studies (IFS), Report 93, https://ifs.org.uk/publications/7165.
Department for Education, 2022a, Higher education policy statement & reform consultation: equality analysis. https://assets.publishing.service.gov.uk/government/uploads/system/uploads/attachment_data/file/1058933/Higher_education_policy_statement_reform_consultation_-_Equality_analysis.pdf.
Department for Education, 2022b, Fairer higher education system for students and taxpayers. https://www.gov.uk/government/news/fairer-higher-education-system-for-students-and-taxpayers.
Department of Health and Social Care, 2022, Department of Health and Social Care group accounting manual 2021 to 2022: additional guidance, version 1. https://www.gov.uk/government/publications/dhsc-group-accounting-manual-2021-to-2022/department-of-health-and-social-care-group-accounting-manual-2021-to-2022-additional-guidance-version-1.
Farquharson, C., Sibieta, L., Tahir, I. and Waltmann, B., 2021, 2021 annual report on education spending in England. Institute for Fiscal Studies (IFS), Report 204, https://ifs.org.uk/publications/15858.
Morgan, J., 2022, Students ‘could save £40K’ by cancelling gap years before reforms. https://www.timeshighereducation.com/news/students-could-save-ps40k-cancelling-gap-years-reforms.
OECD, 2022, Spending on tertiary education (indicator). doi: 10.1787/a3523185-en, https://data.oecd.org/eduresource/spending-on-tertiary-education.htm (accessed on 05 April 2022).
Office for National Statistics, 2020, Student loans in the public sector finances: a methodological guide. https://www.ons.gov.uk/economy/governmentpublicsectorandtaxes/publicsectorfinance/methodologies/studentloansinthepublicsectorfinancesamethodologicalguide.
Waltmann, B., 2022a, Government uses high inflation as cover for hitting students, graduates and universities. Institute for Fiscal Studies (IFS), Observation, https://ifs.org.uk/publications/15940.
Waltmann, B., 2022b, Sweeping changes to student loans to hit tomorrow’s lower-earning graduates. Institute for Fiscal Studies (IFS), Observation, https://ifs.org.uk/publications/15953.
Appendix
Figure A.1. Impact of reforms on the 2022 entry cohort: low growth scenario
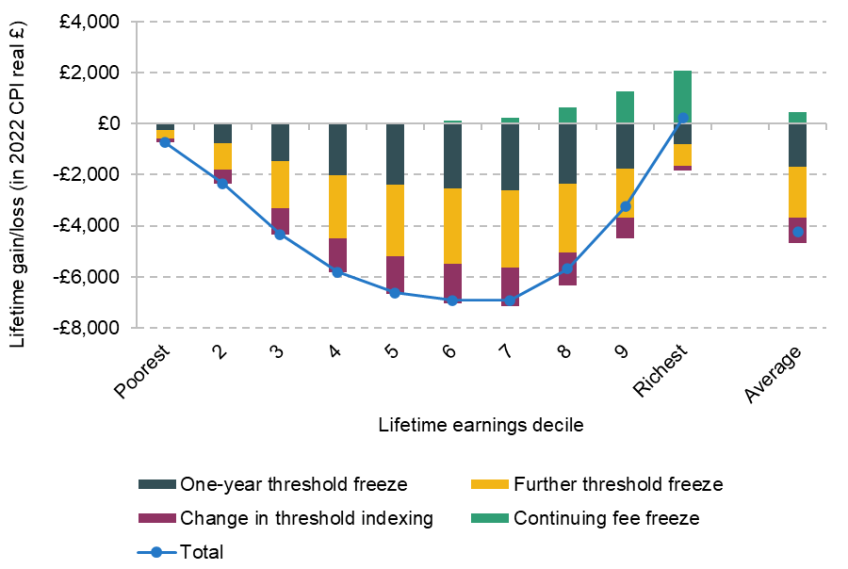
Note: ‘Low growth’ means no earnings growth relative to CPI from 2027 onwards. The split into the impact of different policies depends on the order in which policies are added. The order shown is: one-year threshold freeze, further threshold freeze, change in threshold indexing and continuing fee freeze.
Figure A.2. Impact of reforms on the 2023 entry cohort: low growth scenario
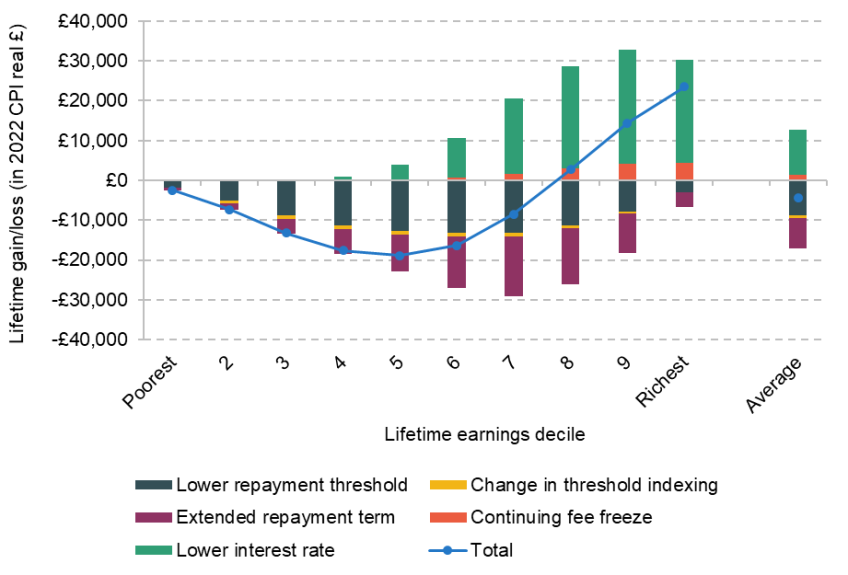
Note: ‘Low growth’ means no earnings growth relative to CPI from 2027 onwards. The split into the impact of different policies depends on the order in which policies are added. The order shown is: lower repayment threshold, change in threshold indexing, extended repayment term, continuing fee freeze and lower interest rate.
Endnotes
Authors

Ben Waltmann
Ben's main research areas are tax and social protection in developing countries, higher education, and dynamic discrete choice models.
More from IFS
Understand this issue


Policy analysis


Academic research


