Downloads
Download report PDF
PDF | 4.12 MB
Foreword
For the past six years, the Nuffield Foundation has funded the Institute for Fiscal Studies in a major programme of work, monitoring and analysing funding arrangements and expenditure across all phases of the education system. A vast array of briefing papers and other outputs are now gathered on the programme’s microsite at https://ifs.org.uk/education-spending. The site is an authoritative source of data, analysis and insight on all aspects of funding, with deep dives into specific, high-priority and timely issues. At its heart are the set-piece annual reports that enable policymakers, educators, researchers and the wider public to look at the whole education landscape, and to understand the latest changes and trends.
This year’s report is – as ever – comprehensive, investigative and eye-opening. It is very hard to select headline findings and messages from an overwhelming choice on offer, but panning out to look at the big and longer-standing issues four might be highlighted.
First, the fact that costs in schools and other educational providers perennially run ahead of general inflation mean that ostensible increases in funding continue not to be reflected in real budgets or actual provision. This is in a context in which spending on education as a proportion of national income has dropped substantially from its peak in 2010. It explains why the view from the chalkface always feels more austere than that from the Chancellor’s desk in the Treasury.
Second, not widely observed in public discourse, we have seen a major convergence in recent decades in per-capita public expenditure on children and young people in different phases of their education. Previously, the older the pupil or student was, the more would be spent on them, with massive differentials. The narrowing of these differentials since at least the late 1980s continued this year and is well highlighted in this year’s report. Given the particularly formative role of education for younger children, this general trend may well be something to celebrate.
Third, this year sees further erosion of funding measures that have attempted to skew resources towards more disadvantaged children, whether that be real-terms levels of Pupil Premium for children from free school meal families in early years and schools, other aspects of school funding formulae, or eligibility arrangements for free childcare entitlements. These losses are a particular concern if we are serious about addressing the attainment gap between disadvantaged children and their peers. Even before the COVID-19 pandemic, this gap had started to widen again following several years of narrowing. It is now clear from a wealth of evidence that the lockdown, other aspects of the pandemic, and its aftermath all significantly exacerbated the gap. The challenges for schools and other providers in helping a whole generation whose education was affected to catch up to where they would have been otherwise is particularly acute for children and young people from poorer backgrounds. On average, their learning loss was greater, they and their families faced more severe mental health and well-being challenges, and their return to normal schooling was much slower.
Fourth, policies such as ‘Education Investment Areas’ have been pursued by the UK government as tools for addressing the persistent geographic inequalities in educational achievement and opportunities seen at all levels of the system, and are part of its ‘levelling up’ agenda. It is clear from this report that so far these are too limited to be registering significant enough impact on funding levels to shift the dial on educational outcomes in specific parts of England.
The Nuffield Foundation is proud to have funded the programme of work on education spending from its inception, and it remains one of our most powerful investments, with its annual reports and outputs very visible and well-used. We would like to thank Luke Sibieta and the many other members of staff at IFS who have worked in such a dedicated fashion to bring this report together.
Josh Hillman
Director of Education, Nuffield Foundation
Preface
This report is the sixth in a series of annual reports on education spending in England. The authors gratefully acknowledge the support of the Nuffield Foundation, which has funded this series of annual reports (grant number EDO/ FR-000022637). The Nuffield Foundation is an independent charitable trust with a mission to advance social well-being. It funds research that informs social policy, primarily in Education, Welfare and Justice. The Nuffield Foundation is the founder and co-funder of the Nuffield Council on Bioethics, the Ada Lovelace Institute and the Nuffield Family Justice Observatory. The Foundation has funded this project, but the views expressed are those of the authors and not necessarily the Foundation.
Website: www.nuffieldfoundation.org. Twitter: @NuffieldFound
The authors thank the Economic and Social Research Council for support via the ESRC Centre for the Microeconomic Analysis of Public Policy (grant number ES/T014334/1), which underpins much of IFS’s research.
The authors would also like to thank the members of the advisory group, officials from the Department for Education, and colleagues at IFS, who have commented on and greatly informed the analysis in this report.
This report uses a range of data releases from the Department for Education, its predecessors, related agencies and non-departmental bodies. These are all listed in the sources below individual figures and/or in the methods section of our new microsite housing all our analysis of education spending (https://ifs.org.uk/education-spending). The IFS student finance modelling uses data from the Family Resources Survey, made available by the Department for Work and Pensions, the Office for National Statistics (ONS) Quarterly Labour Force Survey and Labour Force Survey, and the University of Essex’s British Household Panel Survey and Understanding Society. It also draws on National Pupil Database data linked to data from the Higher Education Statistics Agency (HESA). The National Pupil Database is Crown Copyright and made available by the Department for Education. HESA data are Copyright Higher Education Statistics Agency Limited. Neither the Department for Education nor Higher Education Statistics Agency Limited nor HESA Services Limited can accept responsibility for any inferences or conclusions derived by third parties from the data. The Department for Work and Pensions bears no responsibility for the interpretation of the data in this report.
The views and analysis presented in this report are those of the authors alone. Any errors or omissions are also their responsibility.
Executive summary
This is our sixth annual report on education spending funded by the Nuffield Foundation. It seeks to provide a clear and consistent comparison of the level and changes in spending per student across different stages of education. Our dedicated website (https://ifs.org.uk/education-spending) further provides easy access to our latest analysis, figures and the underlying methodology.
Following on from cuts to most areas of education spending during the 2010s, the government has provided additional funding at successive spending reviews between 2019 and 2021. However, rising levels of inflation and cost pressures have dampened the effects of extra funding. The government also has high ambitions for education to play a major role in ‘levelling up’ poorer areas of the country. In this year’s annual report, we therefore focus on geographic differences in education spending across each stage of education, as well as the extent to which education spending is targeted at pupils from more disadvantaged backgrounds.
Total spending
- In 2022–23, total public spending on education in the UK stood at £116 billion (including the cost of issuing student loans and in 2023–24 prices). In real terms, this represents an 8% or £10 billion fall since 2010–11.
- Education spending has also fallen as a share of national income, from about 5.6% of national income in 2010–11 down to about 4.4% in 2022–23. This is about the same share of national income as in the early 2000s, mid 1980s and late 1960s. There has been no long-run increase in the share of national income devoted to public spending on education, despite large rises in education participation over the long run.
Early years
- Total spending on early years education and childcare more than quadrupled between 2001–02 and 2018–19, when it reached £6.6 billion. This was largely driven by increases in spending on the free entitlement, while support through the benefit system has fallen since 2009–10. Total spending has fallen since 2018–19 to £5.6 billion, partly impacted by the pandemic and high inflation. This still represents a major increase in resources at a time when other stages of education have been squeezed.
- From September 2025, all children in working families will get up to 30 hours of funded childcare a week from 9 months old. These new entitlements will mean that free entitlement spending doubles between this year and 2026–27: the largest and fastest expansion on record.
- The Budget included new money to raise funding rates for existing entitlements. Even so, we estimate that core resources per hour for 3- and 4-year-olds in 2024–25 will be 12% below their level in 2012–13 once providers’ costs are taken into account. The government is instead prioritising younger children: for 2-year-olds, the average (cash-terms) funding rate will reach £8.28 in that year, more than £1 an hour higher in real terms than its previous peak in 2017–18. More important than the specific rates, however, is having a sound process for setting and revising funding rates going forward.
- The most deprived fifth of local authorities receive hourly resources that are 12% higher than areas in the most affluent fifth, after accounting for higher provider costs in London. This results from funding for deprivation, disability and additional language needs in the Early Years National Funding Formula, as well as the Early Years Pupil Premium and the Disability Access Fund.
- Except for provisions for disabled children, funding uplifts for additional needs fell between 2017–18 and 2023–24. Despite recent increases, the Early Years Pupil Premium is due to be 2% lower in real terms in 2023–24 than in 2017–18. Core funding for deprived children, which represented an additional 60% of the core funding rate in 2017–18, is worth just 38% in 2023–24. This fall reflects the fact that funding for additional needs is constrained to be 10.5% of total funding, whilst the number of children classified as deprived has increased. Some of the rise in deprivation reflects transitional protection under universal credit. However, a national funding formula where resource per disadvantaged child falls as deprivation rises seems particularly illogical.
Schools
- School spending per pupil in England fell by 9% in real terms between 2009–10 and 2019–20. This reflects a 1% real-terms increase in total spending on schools, which was more than outweighed by an 11% increase in pupil numbers. The core schools budget is now due to rise from £52.6 billion in 2019–20 to £58.6 billion in 2024–25 (in today’s prices). This funding increase will reverse past cuts and we estimate that school spending per pupil in 2024 will return to 2010 levels in real terms based on standard measures of economy-wide inflation (the GDP deflator).
- The costs faced by schools – such as teacher and support staff salaries – are growing faster than economy-wide inflation. We estimate that schools’ costs will rise by 7% in 2023–24. This reflects the 6.5% pay offer to teachers and an 8% salary rise for support staff. In 2024–25, we estimate that schools’ costs will grow by 4%, which is just about matched by 4% growth in total funding. After accounting for growth in schools’ costs, we estimate that the purchasing power of school budgets in 2024 will still be about 4% lower than in 2010. The recently announced 10% increase in the National Living Wage could push up school costs further, as local government employers seek to maintain small wage differentials over the National Living Wage.
- Secondary school spending per pupil in England in 2023–24 is due to be about £6,900, which is 10% higher than in primary schools (£6,300). This is down from a difference of about 30% in the 2000s and over 50% during the early 1990s. This represents a very significant reduction in the secondary:primary funding ratio over time.
- School spending per pupil is about 21% higher amongst the most deprived group of schools than for the least deprived group, even after accounting for differences in costs across areas. However, this funding advantage is down from 31% in 2010 due to larger spending cuts for more deprived schools. Between 2010 and 2021, the most deprived secondary schools saw real-terms cuts of 12% compared with 5% for the least deprived ones.
- A range of factors explain the larger cuts for more deprived schools. First, the Pupil Premium has not kept pace with overall inflation. Second, the introduction of statutory minimum funding levels in 2020 disproportionately benefited less deprived schools, and reduced the share of total funding focused on more deprived schools. Third, funding factors for deprivation in local authority formulae have reduced in real terms over time, mostly reflecting decisions to reduce deprivation funding in the national formula in 2018. Some of this shift was a deliberate decision to focus more on funding for schools with low prior attainment. This will have spread disadvantage funding more widely. However, it will only have partially compensated the most deprived schools for reductions in deprivation funding over time.
- The pupil population is expected to decline by 600,000 or 8% between 2024–25 and 2030–31, with a 400,000 reduction in primary school pupil numbers and a 200,000 reduction in secondary school pupil numbers. This would reverse almost all of the increase in the pupil population since 2010–11 and create less demand for school places. However, declining pupil numbers will only reduce spending needs if schools are able to shrink their costs and staff numbers in equal measure.
Further education and skills
- In the 2023–24 academic year, we estimate that spending per student aged 16–18 in further education (FE) colleges will be £7,100, compared with £5,800 in school sixth forms and £5,400 in sixth-form colleges. Higher funding for FE colleges reflects extra funding for costly technical programmes and for students from more deprived areas.
- Between 2010–11 and 2019–20 financial years, spending per student aged 16–18 fell in real terms by 14% in colleges and 28% in school sixth forms. For colleges, this left spending per student at around its level in 2004–05, while spending per student in sixth forms was lower than at any point since at least 2002.
- In the 2021 Spending Review, the government announced £1.6 billion in extra funding for colleges and sixth forms by 2024–25. Yet even with the additional funding, college spending per student in 2024–25 will still be about 10% below 2010–11 levels, and school sixth-form spending about 23% lower than in 2010–11.
- The government announced extra funding in July and October 2023 to enable colleges to afford higher staff pay rises and to increase funding rates for GCSE retakes. However, none of this was new funding. It all came from existing plans. Student numbers have increased by less than expected and the government could thus increase funding rates by more than planned.
- The main driver of slower growth in student numbers is a 13% decline in the number of 18-year-olds in further education between 2019 and 2022. This reflects falling levels of participation in education and training amongst 18-year-olds, which has fallen from 73% in 2015 to 70% in 2020 and to 66% in 2022. There has been a gradual rise in the share of 18-year-olds in employment (up from 14% in 2014 to 19% in 2022). The share of 18-year-olds who are not in education, employment or training (NEET) was at 16% in 2022, near equal to the share last seen in the Great Recession of the late 2000s.
- The distribution of funding across areas is highly shaped by the share of students in (more highly funded) FE colleges, which leads to higher levels of spending per student in more disadvantaged areas and in Northern regions of England, with mostly lower spending levels in London. As a result, spending per student is about 9% higher in the most deprived areas than in the least in 2023–24, up from about 4–5% in 2013–14. This increase reflects the smaller cuts for FE colleges and greater funding for students in disadvantaged areas over time.
- Total spending on adult skills is set to increase by 14% in real terms between 2019– 20 and 2024–25. However, this only reverses a fraction of past cuts: total adult skills spending in 2024–25 will still be 23% below 2009–10 levels. Spending on classroom-based adult education has fallen especially sharply, driven by falling learner numbers and real-terms cuts in funding rates, and will still be over 40% below 2009–10 levels in 2024–25 even with the additional funding.
- Following on from big increases between 2010 and 2015, the total number of adult apprentices (aged 19 or over) has declined by 16% since 2016–17 and the introduction of the apprenticeship levy. However, the number of higher apprentices, including degree apprentices, has trebled in the same period.
Higher education
- Up-front spending on teaching resources per higher education student has continued to decline steadily, standing at £9,600 per year for the 2023–24 university entry cohort. This is around £2,100 or 18% lower in real terms than in 2012–13, largely because the cap on tuition fees is now 24% lower in real terms than it was in 2012–13. Teaching resources are now only slightly higher in real terms than they were in 2011–12 (£9,400) before the substantial increase in tuition fees.
- The nominal freeze in the level of fees is set to continue for another year, adding financial pressure on universities. At the same time, official forecasts for domestic student numbers have been revised down substantially, with the number of undergraduate student entrants now expected to increase by 7% between 2021 and 2026. In more welcome developments for higher education providers, international student recruitment has been strong, and the finances of the main university pension scheme (USS) have improved markedly on the back of higher long-term interest rates.
- For current students, higher-than-expected inflation has continued to erode the real value of maintenance loans. Students in 2023–24 will be entitled to borrow 11% less towards their living costs than they were in 2020–21, a cut equivalent to £107 a month for the poorest students. Without a change in policy, living cost support for future students will be permanently lower, causing hardship for some.
- On top of this, parental earnings thresholds governing maintenance loan eligibility have been frozen since 2008. As a consequence, maintenance support for students from families with middling earnings has been cut even more severely. A student with parental earnings of £62,000 is entitled to £4,700 this academic year, but would have received £2,500 (52%) more in real terms in 2016–17 if their parents earned the same relative to average earnings.
- Unlike for other stages of education, the distribution of higher education spending across local areas differs substantially depending on whether students’ local areas of origin or their areas of residence during term time are considered. By the area that students come from, spending per young person is highest in London (£15,800) and lowest in Northamptonshire (£5,800) and Blackpool (£6,250). This largely reflects differences in areas’ university participation rates, with students from more advantaged backgrounds more likely to attend higher education and benefit from spending directly.
- Higher education spending also has wider economic impacts on the areas in which people study. On this measure, per-capita higher education spending is highest in university towns, with by far the highest spending in Canterbury (£2,300) followed by Bath (£1,380) and Brighton (£1,280). In contrast, around a third of all travel-to-work areas in England do not have a higher education provider and therefore do not benefit directly from public spending on higher education at all. A handful of local areas – notably Oxford and Cambridge – also benefit substantially from public research funding for universities, and reap more rewards from the innovation that comes alongside.
1. Introduction and context
Education spending is the second-largest element of public service spending in the UK behind health, representing £116 billion in 2023–24 in today’s prices or about 4.4% of national income. To make efficient and equitable policy choices, it is crucial to have a clear, consistent picture of how the level of spending at each phase of education has changed over time, expected future changes and the factors driving these changes. Such issues are a vital component of policy debate, given evidence showing how education investments at different ages combine to drive long-run outcomes (Cunha, Heckman and Schennach, 2010; Johnson and Jackson, 2019).
In a series of annual reports on education spending funded by the Nuffield Foundation, we have sought to cast light on this subject by illustrating how spending per pupil across different stages of education has changed over time. We also publish a range of smaller outputs throughout the year to provide more timely and rapid analysis of the resource challenges facing different phases of education. This analysis is housed on a dedicated website (https://ifs.org.uk/education-spending), providing easy access to the latest figures and the underlying methodology. The Nuffield Foundation has kindly decided to fund this programme for a further three years from 2024 through to 2026.
The government has consistently emphasised the role that education can play in narrowing inequalities and ‘levelling up’ poorer areas of the country. With this in mind, this year’s annual report has a special focus on differences in spending across different areas of England, and the extent to which funding is targeted at institutions and areas serving more disadvantaged students. This provides insight on the degree to which education spending is being used as a means of redistribution towards poorer families, and potentially as an engine for social mobility, particularly given evidence suggesting that students from poorer families tend to benefit more from education spending. We look at the picture across the early years, schools, further education colleges and sixth forms, and higher education. Due to differences in the organisation of each sector, the size of institutions and available data, the analysis is performed slightly differently in each case. However, this still enables us to provide a clear picture of the level of funding targeted at disadvantaged students and areas across each stage of education.
The rest of this introduction provides overall context on total spending, pupil numbers across each sector over time and the overall methods and approach we use in our analysis.
1.1 Total spending on education
The total level of UK education spending has risen significantly in real terms over time. As shown in Figure 1.1, growth was particularly fast from the late 1990s through to the late 2000s, with real-terms growth averaging about 5% per year between 1998–99 and 2010–11. Education spending then fell as public spending cuts began to take effect from 2010 onwards. Between 2010–11 and 2019–20, official education spending fell by over 15% in real terms. Since then, it has begun to increase again, but it remained 12% below its level in 2010–11 by 2022–23.
Figure 1.1. UK education spending (2023–24 prices and as a share of national income)

Source: HM Treasury, Public expenditure statistical analyses, various editions; HM Treasury, GDP deflators, November 2023; Office for Budget Responsibility, Economic and fiscal outlook, various editions; Office for National Statistics, Student loans in the public sector finances: a methodological guide, January 2020.
Some of the decline in education spending during the 2010s reflects initially large declines in capital spending just after 2010 (Sibieta, 2023a). The decline also reflects a deliberate increase in effective private funding for higher education through graduate contributions later in life.
Unfortunately, these official figures do not fully account for the cost to the taxpayer of issuing student loans from 2011–12 onwards. As a result, the series overstates cuts to education spending since 2010–11. Recent changes to national accounting rules mean that the expected cost of issuing student loans is included in overall measures of government spending and the public finances, such as the deficit. We estimate that if official measures of education spending had followed the new national accounting rules for student loans, education spending would have been around £6 billion higher in 2015–16 and £5 billion higher in 2022–23.1 If we add these numbers to the official measure of education spending, the real-terms cut in education spending between 2010–11 and 2022–23 falls from 12% to 8%.
Including the adjustments for student loans, education spending represented about 4.4% of national income in 2022–23. This follows a temporary peak of 5% during the height of the COVID-19 pandemic in 2020–21, when spending was boosted and the size of the economy was depressed. However, education spending has declined as a share of national income over the last 10–15 years, and is down from a peak of over 5.6% of national income around 2010. This peak followed a big rise in education spending during the 2000s, when it rose from about 4% to 5.6%.
Looking over the longer term, it is clear that education spending as a share of national income has not seen a sustained rise since the early 1970s, when it stood at 4.5–5% of national income. It has instead oscillated between about 4% and 5.5% of national income. It is now at a similar level to that seen in the early 2000s, mid 1990s, mid 1980s and late 1960s. This is despite large rises in participation in post-compulsory education over time, in both schools and higher education, as well as the creation of an early years sector.
As we analysed in detail in last year’s annual report (Drayton et al., 2022), there is a contrast between long-term trends in health and education spending over time. There has been no sustained increase in the share of national income devoted to education spending, despite rises in education participation over time. In contrast, and in response to rising needs, health spending has more than doubled as a share of national income, from about 4% of national income in the late 1970s to over 8% in 2022–23. Further details about the changing composition of public spending can be found on the IFS Taxlab website.2
1.2 Student numbers over time
Total spending figures can obscure the impact of changes in the number of pupils, which are often one of the most important factors driving changes in the total and per-pupil level of spending over time. There have also been some fairly substantial changes in recent times, which are due to continue over the next decade.
Figure 1.2a shows the number of pupils in state-funded primary and secondary schools over time. Numbers in primary schools grew by 17% between 2009–10 and 2019–20, the equivalent of an extra 700,000 pupils – or effectively a full cohort of children. They are now, however, starting to fall again, with a 5% or 200,000 drop expected between 2019–20 and 2024–25. Pupil numbers in secondary schools fell from the early 2000s through to about 2014–15. Between 2014–15 and 2019–20, they then grew by nearly 10% or 300,000, and they are forecast to grow by a further 8% or 200,000 between 2019–20 and 2024–25.
Looking beyond 2024–25, the total pupil population is expected to fall by 600,000 or 8% between 2024–25 and 2030–31. This would reverse most of the increase in the pupil population since 2010–11. Rising pupil numbers create resource challenges in terms of a need for extra schools and extra staff. Falling pupil numbers create the reverse problem, in that some schools and staff may no longer be needed. Indeed, some schools might not be financially viable.
While pupil numbers in primary and secondary schools are driven mainly by population size, pupil numbers in other stages of education – early years, further education and higher education – are also affected by changing patterns of participation. Figure 1.2b shows that there have been big increases in pupil numbers at all three stages. While population growth plays a role, extensions to the free childcare entitlement (in the early years) and higher levels of participation (at later stages) are the main factors driving these changes.
There is a range of support for early years and childcare, including subsidies through the tax and benefit system. But the largest group of programmes – and the one most recognisably aimed at early education – is the trio of ‘free entitlements’ to funded early education and childcare places, paid for by the Department for Education:
- The universal entitlement offers all 3- and 4-year-olds a part-time (15-hour) place for 38 weeks of the year.
- The extended entitlement, introduced in 2017, offers an additional 15 hours a week of childcare to 3- and 4-year-olds in working families.
- The 2-year-old offer, introduced in its current form in 2014, provides the roughly 40% most disadvantaged children with a part-time early education place, again for 38 weeks a year.
Figure 1.2. Pupil numbers in education in England
a) Schools

b) Other stages of education

Note and source: Years refer to academic years. Early years numbers represent part-time-equivalent places of 3- and 4-year-olds taking up the universal early years entitlement (excluding 4-year-olds in infant classes) and are taken from Department for Education, ‘Education provision: children under 5 years of age’, January 2023, January 2010, January 2006 and January 2002. Primary and secondary school numbers are taken from Department for Education, ‘Schools, pupils and their characteristics’, January 2023 and earlier years, and National pupil projections: October 2023. Further education and sixth forms figures refer to 16- to 18-year-olds in state-funded schools or colleges as measured at the end of each calendar year in Department for Education, Participation in education, training and employment: 2022. Higher education figures relate to full-time students on first undergraduate degrees and other undergraduate courses from HESA, Who’s studying in HE? and also use Historical statistics on the funding and development of the UK university system, 1920–2002. Forecasts for the early years and 16–18 education are based on ONS 2020-based forecasts for the population of 3- to 4- and 16- to 18-year-olds. Forecasts for higher education are based on Department for Education methods for forecasting the cost of student loans up to 2026 (https://explore-education-statistics.service.gov.uk/methodology/student-loan-forecasts-for-england-methodology) and ONS forecasts for the number of 18- to 21-year-olds from 2026 to 2030.
Between 2001–02 and 2016–17, the total number of part-time-equivalent places for the universal free entitlement in the early years rose by 33%, reflecting greater numbers of children in the population and expansions to free entitlement eligibility. In 2017–18, the number of part-time-equivalent places jumped as children in working families became eligible for the extended entitlement. Since then, the number of part-time-equivalent places has been roughly constant. Whilst numbers taking up the universal free entitlement have fallen by 60,000 or 7% between 2017–18 and 2022–23, reflecting reduced cohort sizes and falling take-up rates, the number taking up the extended entitlement has gone up by 60,000.
Looking to the future, the number of part-time-equivalent places for 3- and 4-year-olds is expected to remain at this level. The number of 3- and 4-year-olds taking up the universal entitlement is expected to drop by 9% or 70,000 between 2022–23 and 2029–30, mainly reflecting reduced cohort sizes. However, this drop is due to be offset by further increases in take-up of the extended entitlement.
From September 2024, the entitlement to free early education and childcare will be gradually extended to all children aged over 9 months whose parents are in work. This will represent another substantial increase in the entitlement, which is discussed further in Chapter 2 and Drayton and Farquharson (2023).
The number of students in 16–18 education grew by almost 50% between 1990–91 and 2010–11, from about 800,000 to 1.2 million full-time-equivalent (FTE) students. After 2010–11, numbers fell by about 10% down to just over a million in 2018–19, reflecting reduced cohort sizes rather than falls in participation.
Since then, numbers have started to rise again and the number of students is 7% higher in the latest year of data (2022–23) than in 2018–19. This mostly reflects growth in cohort sizes again. Of potential concern is a recent drop in education participation amongst 16- to 18-year-olds, which was 79% in 2022–23, down from 81–82% in the period between 2013 and 2020. This represents the lowest level of participation since 2010 and, as we shall see in Chapter 4, was mostly driven by falling participation amongst 18-year-olds. This has led to lower-than-expected increases in student numbers this year.
Further rises are expected over the next few years due to population growth, with numbers currently projected to rise by 8% between 2022 and 2025, and a total of 14% between 2022 and 2030. This would make for 100,000 extra students by 2025, or 150,000 extra by 2030. This would clearly place upwards pressure on college and sixth-form spending. However, these projections are partly predicated on no further falls in education participation.
The number of full-time undergraduate students in higher education in England more than doubled between 1990 and 2019, to reach 1.06 million. Participation increased during the pandemic, with student numbers increasing by 6.6% in 2020, but growth has since slowed. In the latest year (2022), the same number of people started university as the previous year, whereas government was forecasting back in July 2022 that the number would increase by around 2%. Government also now expects the number of entrants in future years to grow less quickly.
The latest forecasts imply higher education student numbers will increase by 5% or 65,000 between 2022 and 2026. Based on ONS population forecasts, we would then expect the number of full-time undergraduate students in higher education to continue to rise, reaching 1.33 million in 2030. This would be 133,000 (11%) more than in 2022.
Increases in student numbers will clearly place pressure on spending. In the past, such as during the 1990s, spending has not always increased in line with rising student numbers, thereby reducing spending per student. At other times, large increases in higher education student numbers have led governments to make substantial changes to the higher education finance system in order to ensure sufficient levels of resources.
This time, perhaps in anticipation of rising student numbers, the government has already made large changes to the student finance system, which will likely reduce the cost of the system to the taxpayer (Waltmann, 2022a). However, we are also seeing large real-terms reductions in spending per student as rising inflation erodes the real-terms value of the fee cap, which has been frozen in cash terms at £9,250 since 2017.
1.3 Methods and approach
The rest of this report focuses on day-to-day or current spending on different areas of education in England. This is primarily for data availability reasons, though we have also provided analysis comparing school spending per pupil across the four nations of the UK, which indicates higher levels of school spending per pupil in Scotland in particular (Sibieta, 2023b). We have also examined trends in school capital spending over time (Sibieta, 2023a).
For the most part, we focus on public spending on education. This is due to a lack of reliable data on total private spending on each stage of education over time. For schools, we have produced additional analysis comparing state school spending per pupil and private school fees over time (Sibieta, 2023c), as well as the likely effects of Labour’s proposals to remove tax exemptions from private schools. For higher education, we also analyse the level of expected graduate contributions to higher education spending through student loan repayments later in working life. Indeed, we show that the most recent set of reforms is likely to increase graduate contributions to higher education spending and reduce the expected government subsidy.
In Chapters 2–5, we examine trends in spending on the early years, schools, further education and skills, and higher education. In Chapter 6, we compare trends in spending per pupil across different stages of education over time. In each case, our methodology for calculating spending per student is detailed in full on the dedicated website (https://ifs.org.uk/education-spending/methods-and-data). In most cases, figures relate to core education spending and exclude temporary support during the pandemic, though it is not always possible to separate this out. Chapter 7 concludes.
In this report, we have a special focus on geographical differences in spending per child, and the levels of extra funding for children and young people from disadvantaged backgrounds. Each chapter takes a slightly different approach, given the different measures of deprivation used in the funding system for each stage and the organisation of providers.
In most cases, we calculate real-terms changes by adjusting for economy-wide inflation as captured by the GDP deflator. This is the standard practice used for analysing public spending in the UK. Across long periods of time and in stable economic environments, the GDP deflator is likely to provide a close approximation to the costs faced by education providers. However, we have recently seen a very big spike in inflation, much of which reflects the rising costs of imported energy and food. The GDP deflator does not fully capture import prices as it measures domestic inflation, making it less useful for assessing the cost pressures on public services during such periods. With this in mind, we also provide analysis of likely costs faced by providers in the current situation of high inflation and high cash-terms growth in earnings across the public and private sectors. This allows for a wider picture of the current pressures on providers’ budgets.
2. Early years
Over the last quarter of a century, England has undergone a substantial transformation in its approach to early years education and childcare. As Figure 2.1 shows, total spending on the early years, encompassing both the provision of funded childcare places and childcare subsidies via the tax and benefit system, grew from £1.6 billion in 2001–02 to a peak of £6.6 billion in 2018–19, in today’s prices. It has since decreased to £5.6 billion in 2022–23. These shifts in spending have been accompanied by changes in the composition of early years support. In 2009–10, spending on the (universal) free entitlement matched that of childcare subsidies for low-income working families. Since then, spending on the free entitlement has doubled, while childcare subsidies through the benefit system have fallen by over half and take-up of programmes such as tax-free childcare remains low.
This state of flux is set to continue with the reforms announced in the March 2023 Budget: by September 2025, all children in working families will be entitled to 30 hours per week of funded term-time care from 9 months old until the start of school. This continues the trend of successive governments in expanding the free entitlement to cover more children and more hours.
This period has also been marked by changes in how early years funding is allocated locally to different areas, most notably with the introduction of the Early Years National Funding Formula in 2017–18. Most families access early education and childcare in their local neighbourhood; hence, understanding how resources are distributed across areas is just as important as examining the national funding landscape.
This chapter is split into two parts. The first lays out how total spending on the early years system and on the free entitlement has changed at the national level (Section 2.1) and looks forward to how spending might evolve over the coming years in light of the new entitlements (Section 2.2). The second part looks at spending on early years at a local level. It explores the geographical distribution of spending on the free entitlement, the extent to which funding follows needs and how this has changed over time.
Figure 2.1. Total spending on support for early education and childcare

Note: Free entitlement spending includes spending on the universal entitlement for 3- and 4-year-olds, the extended entitlement for 3- and 4-year-olds in working families, and the entitlement for disadvantaged 2-year-olds. Spending through the tax system includes the value of tax reliefs via employer-sponsored childcare vouchers and tax-free childcare, but not the value of VAT exemptions. Spending through the benefit system includes childcare subsidies in universal credit and its predecessors. Spending through universal credit is imputed by combining the average payment for the childcare element in 2021–22 (the only year this statistic is available) with annual take-up figures released by the Department for Work and Pensions. This assumes the average value of the universal credit childcare payment remains constant in cash terms. Spending in both the tax system and the benefit system is reported on a UK-wide basis. We approximate spending in England by rescaling by the English share of the UK’s under-15 population. Spending in both the tax and benefit systems includes spend on children aged 5 or above. For most schemes, the vast majority of take-up is by families with children under the age of 5; hence we make no adjustment, though we recognise that total spend goes on a wider age range. More detail of our methodology can be found at https://ifs.org.uk/education-spending/methods-and-data. Uses HM Treasury, GDP deflators, November 2023.
Source: See https://ifs.org.uk/education-spending/methods-and-data.
2.1 Early years spending
As demonstrated in Figure 2.1, by far the biggest programme of early years spending in England is the ‘free entitlement’ to a funded early education place. There are a number of distinct offers within the free entitlement programme:
- a universal offer of 15 hours a week for all 3- and 4-year-olds;
- an extended entitlement to 30 hours a week for 3- and 4-year-olds in working families;
- a disadvantage offer of 15 hours a week for the most disadvantaged 2-year-olds;
- new ‘Budget entitlements’, rolled out between April 2024 and September 2025, to 30 hours a week for children from 9 months to the end of age 2 in working families.
This final group of programmes, announced in the March 2023 Budget, will eventually mean that children in households where all adults are in paid work will be entitled to up to 30 hours a week of funded childcare from the end of paid parental leave (at 9 months) until they start school.
Total spending
As Figure 2.2 shows, free entitlement spending has seen close to uninterrupted real-terms growth from the mid 2000s until its peak in 2018–19. Notably, this is even as other stages of education and public services more broadly (outside healthcare) have experienced significant funding pressures (Zaranko, 2022). Growth in total real-terms resources is set to continue with the roll-out of the new entitlements announced in the March 2023 Budget. Only three other areas of public spending (NHS England, Defence, and the Foreign, Commonwealth & Development Office) are set to see a real-terms rise in spending between 2024–25 and 2028–29 under current spending plans (Boileau, 2023), a signal of the government’s prioritisation of childcare.
Figure 2.2. Total real-terms spending on free entitlement hours in England

Note: ‘Universal’ entitlement refers to the entitlement to 15 weekly hours of funded care for 3- and 4-year-olds during term time. The ‘extended’ entitlement captures the additional 15 hours a week that 3- and 4-year-olds in working families can access. The ‘2-year-old’ offer provides 15 hours of funded childcare to 2-year-olds in disadvantaged families. It was initially piloted in a small number of areas in 2012, before being rolled out nationally in 2013. Because our data on total spending do not split out the universal and extended entitlements, we allocate total spending proportional to their budgets from the Dedicated Schools Grant. Uses HM Treasury, GDP deflators, November 2023.
Source: See https://ifs.org.uk/education-spending/methods-and-data.
However, Figure 2.2 also highlights that much of this growth is driven by the expansion of additional entitlements. All of the increase in overall free entitlement spending in the decade since 2012–13 came from the introduction of the 2-year-old and extended entitlements. Meanwhile, spending on the core universal offer fell from £2.9 billion in 2012 to £2.5 billion last year (all in 2023–24 prices). These changes reflect demographic trends amongst the 3- and 4-year old population discussed in Chapter 1. After the peak in the number of 3- and 4-year-olds in 2016–17, a population bulge that started in the mid 2000s began to recede and the number of 3- and 4-year-olds in England has since fallen by 115,000, or about 8% of its peak.
Although growth in the 2-year-old offer also contributed to the overall rise in free entitlement spending during the 2010s, falling populations have impacted real-terms spending on 2-year-olds as well. However, falling spending is driven to a greater extent by changes to the number of children who are eligible for the 2-year-old entitlement. Eligibility for the entitlement is determined by whether families receive certain other benefits (or whether the child meets other criteria, such as having an education, health and care plan or being a care leaver). In 2015–16, these criteria covered nearly 40% of 2-year-olds. However, since then, eligibility rates have fallen due to the transition from legacy benefits to universal credit, the tightening of the coverage and generosity of the working-age benefits system, and the impact of wages rising while eligibility thresholds remained fixed in cash terms. Taken together, in 2022–23, just 27% of 2-year-olds were eligible for the entitlement (Farquharson, 2023a).
Spending per child and per hour
These changes in the number of children taking up childcare places can explain much of the fluctuation in total spending on the free entitlement. To strip out the impact of changing populations and to better understand what these resources mean for childcare providers on the ground, it is informative to look at spending per child and per childcare hour. Figure 2.3 shows these measures alongside total spending, focusing on spending on 3- and 4-year olds (both universal and extended entitlements). Real-terms spending is indexed to its 2009–10 level to understand how spending has changed over time.
Spending per child taking up a place (yellow line) has largely tracked total spending (green line) but has been less volatile – especially during the pandemic period – and is now about 95% above its 2009–10 level. Yet, as discussed earlier, much of this increase is driven by the offer of more hours to 3- and 4-year olds from working families (the extended entitlement), which began rolling out from 2017–18.
Figure 2.3. Growth in real-terms spending on the free entitlement for 3- and 4-year-olds

Note: Spending on universal and (from 2017–18) extended entitlements for 3- and 4-year-olds. Spending per place is spending per part-time-equivalent place (15 hours) across both entitlements, so a child accessing their full universal and extended entitlement would count towards two part-time-equivalent places; see https://ifs.org.uk/education-spending/methods-and-data for more details. Uses HM Treasury, GDP deflators, November 2023.
Source: See https://ifs.org.uk/education-spending/methods-and-data.
Spending per hour is also shown (in blue) to better understand the amount of resources available to deliver the childcare entitlements. Based on hourly spending, growth in free entitlement spending has been more measured. Between 2009–10 and 2022–23, it grew by 18% in real terms. Underlying this growth, however, Figure 2.3 also reveals the irregularity of funding increases. There is clear evidence of a ‘ratchet’ pattern, where a big jump in real-terms spending is followed by real-terms decline as cash-terms funding settlements are eroded by inflation.
Most recently, 2022–23 saw a cash-terms rise in funding rates; however, higher-than-expected inflation has meant a significant drop in real-terms spending per hour over the last year. In real terms, spending per hour in 2022–23 was 8.6% lower than it had been the year before, one of the steepest one-year drops in our data series.
The picture for 2-year-old hourly funding is similar, with several years where the core funding rate was held constant in cash terms (so eroding providers’ real resources).
2.2 Budget reforms and beyond
Having documented significant shifts in spending on the free entitlement programme over the past 20-odd years, we now look ahead to future spending. The reforms outlined in the March 2023 Budget mark the biggest expansion yet, with planned expenditure on funded childcare hours set to double over the next four years.
Starting from April 2024, the programme will extend its coverage to 2-year-olds in working families, defined similarly to the extended entitlement for 3- and 4-year-olds. It will then further expand to include children as young as 9 months from September of the same year. Initially, the offer will provide up to 15 hours a week for 38 weeks annually, with flexibility to cover additional weeks. This allocation will increase to 30 hours per week by September 2025, at which point all children in working families will be eligible for up to 30 hours of funded care per week from the end of statutory parental leave until the start of school.
Total funding
Figure 2.4 shows the impact of these Budget reforms on core central funding for the free entitlement. This differs from the measures of spending we have used so far, which incorporate a broader set of funding sources for the free entitlement. Nevertheless, this funding measure still captures almost all spending (Drayton and Farquharson, 2023).
Figure 2.4. Total core funding for the free entitlement, by programme

Note: See box 1 in Drayton and Farquharson (2023) for methodology. Uses HM Treasury, GDP deflators, November 2023.
As Figure 2.4 shows, spending on the free entitlement is set to rise substantially in real terms: by 2027–28, total spending will be significantly more than twice as high as its 2022–23 level. This represents a huge increase in the early years budget, which is all the more notable for the much tighter settlements imposed on other areas of public services. The impacts of inflation are nonetheless still felt: based on inflation forecasts at the time of the March 2023 Budget, real-terms spending was set to rise by almost 70% between 2022–23 and 2024–25. That figure is now just over 60%.
Importantly for providers, part of this additional spending is an uplift for existing entitlements worth about £290 million next year. As we describe below, this uplift is largely being used to increase the rate paid for 2-year-olds in 2023–24 and then again (to a lesser extent) in 2024–25. There was also a smaller increase in the rate for 3- and 4-year-olds from September this year.
Hourly funding
These large sums of money invested into expanding the free entitlement are a strong signal of the government’s priorities. However, for these additional childcare hours to be deliverable in practice, it is the funding rate that childcare providers receive that matters more.
In Figure 2.5, we show how core funding per hour (which excludes uplifts such as the Early Years Pupil Premium) has changed for 3- and 4-year-olds since the Dedicated Schools Grant was introduced in 2012–13. In cash terms (shown in green), the core funding rate is currently more than 20% higher today than it was a decade ago, bolstered by the Budget uplift, and could continue to rise substantially over the coming years based on current spending plans. Yet, real resources have failed to keep pace. As the series in grey shows, this cash-terms increase has been unable to keep up with economy-wide inflation (as measured by the GDP deflator). On this measure, core funding per hour is about 9% lower in 2023–24 than it was a decade ago. While spending plans under the Budget uplift go some way in reversing these declines, based on the latest forecasts of inflation, the core funding rate is set to remain 4% below its 2012–13 value by 2024–25.
However, this measure is based on economy-wide inflation, which is likely to underestimate the costs that childcare providers specifically face. In particular, around three-quarters of their expenses go to staff costs (Drayton and Farquharson, 2022), and wages – most notably the minimum wage – have been rising faster than economy-wide prices for most of the last decade.
Once providers’ specific costs are taken into account, core funding per hour in 2023–24 is around 16% lower than a decade ago. Even the uplift from the Budget is unlikely to see resources per hour restored to anything like their previous level: on our estimates, core resources per hour in 2024–25 will remain more than 10% lower than in 2012–13.
Figure 2.5. Core funding per hour for 3- and 4-year-olds, on different inflation measures

Note: Funding rates up to 2022–23 are drawn from the Early Years block of the Dedicated Schools Grant. In 2023–24, funding rates changed midway through the financial year, in September; the chart presents weighted averages of the April–August and September–March rates. The funding rate for 2024–25 has been announced as £5.88 for 3- and 4-year-olds in cash terms. For 2025–26 onwards, we use estimates of the total free entitlement budget for each stage combined with estimated part-time-equivalent places to model how core funding could evolve. GDP deflators are taken from HM Treasury, GDP deflators, November 2023. Providers’ cost series accounts for changes in costs specific to childcare providers; see Drayton and Farquharson (2022) for more details.
The rate for 2-year-olds has fallen less steeply, from £6.46 in 2015–16 to £6.12 last year in today’s prices, representing a 5% fall over the period. Two-year-olds have also received a much bigger increase in funding rates from September 2023: the core funding rate has been increased to £7.95 for the remainder of this financial year, rising to £8.28 (in cash terms) in 2024–25. This, together with relaxation of staff:child ratios for 2-year-olds, also announced in the March 2023 Budget, will leave providers catering to younger children with more resources compared with 2017–18, when core funding per hour peaked.
Delivering the Budget reforms
Extending the free entitlement to children aged 2 and under in working families represents a substantial expansion in the amount of funded childcare that providers are expected to deliver. Expected rises in total spending and hourly funding for 2-year-olds (and the much smaller increases for 3- and 4-year-olds) seem to acknowledge the scale of this reform.
But while the early years continue to be prioritised relative to most other areas of public spending, significant challenges still remain with the design, distribution and deliverability of the new entitlements.
The Budget reforms raise fundamental questions about the aims of England’s early years system. Since new entitlements will only be available to children in ‘working’ families, these reforms put supporting parents in the labour market at their centre. By definition, this means that children in the poorest families (whose parents are out of work) are not included, limiting the ability of early education and childcare to mitigate socio-economic disparities.
Indeed, the new entitlements continue the trend towards prioritising childcare support for parents who work, rather than universal services or targeted early education for low-income families: the poorest 30% of families will see almost no direct benefit from the new entitlements (Farquharson, 2023b). This comes on top of the decline in the share of disadvantaged 2-year-olds eligible for a funded childcare place discussed earlier. Given that high-quality early years childcare has been shown to have positive effects on child development, particularly for the most disadvantaged, less support for the poorest children may widen inequalities early in life.
Another key challenge facing the new entitlements is their deliverability. With the government expected to control approximately 80% of pre-school childcare prices once the entitlements are fully implemented (Drayton et al., 2023), there are substantial risks associated with setting the funding rate correctly. Setting the rate too high, and without proper regulation, could lead to public funds being converted into excessive profits rather than invested in other areas. Conversely, set the rate too low and providers may be discouraged from participating, particularly as their ability to cross-subsidise with privately paid hours declines.
The government has budgeted for higher funding rates for 2-year-olds and under-2s that are well above current market prices. But for 3- and 4-year-olds, the funding rate aligns more closely with existing market rates, posing potential challenges in areas where funding and provider costs diverge. The key issue is how these rates will be set and adjusted in the future. Historically, rates have seen extended periods of cash-terms freezes, with inflation eroding providers’ real resources, followed by significant adjustments. The need to rationalise this process and to revise rates in a more consistent and predictable way is all the greater as the government plays an increasing role in setting prices in the childcare market.
2.3 Geographic patterns of spending
So far, we have studied the amount of spending on early years ‘free entitlements’ at a national level. But childcare and early education are inherently local: for families using these entitlements, the availability and funding of places in their local area are more relevant than the national picture. In this section, we examine the distribution of free entitlement spending for 3- and 4-year-olds across the country, and by area characteristics such as deprivation. This analysis sheds light on the extent to which early years funding acts to ‘level up’ inequalities across areas.
Early years funding system
Free entitlement funding is allocated across areas according to the Early Years National Funding Formula (EYNFF) (Education and Skills Funding Agency, 2022). This was introduced in 2017–18 to rationalise funding across local authorities, ensuring that areas with similar characteristics are treated similarly, and to provide transparency around allocation decisions.
Under this system, all local authorities receive a flat hourly funding rate which is then topped up according to areas’ needs. The formula provides extra funding for children with particular characteristics (denoted ‘factors’): deprivation, disability and additional language needs. When the EYNFF was introduced, the factor uplifts for deprivation, English as an additional language (EAL) and disabled children were worth 60%, 8% and 21%, respectively, of the universal base rate.
Another major driver of differences between areas is the area cost adjustment (ACA). This is a scaling-up of the funding rate in each area to reflect local costs of providing early years education and childcare – for instance, costs of employing staff (which make up the bulk of costs) and costs of leasing premises. Finally, floors to funding rates and caps on year-to-year gains are applied to arrive at the final rate for local areas. In the first three years of the EYNFF, there were also transitional protections in place to ensure significant changes in funding were smoothed over multiple years, rather than occurring in a single year.3
The EYNFF governs how central government allocates free entitlement funding across local authorities (LAs). Each LA is then responsible for allocating funding to the providers in its area, based on its own (and confusingly named) ‘Early Years Single Funding Formula’. While these formulas are the responsibility of LAs, central government has increasingly restricted what factors the Early Years Single Funding Formula can consider and to what extent, and so differences in funding rates for providers around England are driven more by the national funding formula than by the differences across LAs’ single funding formulas. In the rest of this section, we therefore focus on hourly funding rates derived from the EYNFF.
It is also a requirement that each type of childcare provider receives the same hourly rate for delivering the free entitlement, yet they may have different costs of delivery. The area cost adjustment and uplifts for maintained nurseries go some way in addressing these cost differences. However, we do not explicitly consider how different types of providers fare under the EYNFF.
Box 2.1. Measuring funding to areas
The funding that different areas receive reflects a bundle of different factors and funding sources. We are interested in constructing a measure that captures the ‘effective’ resources local areas have at their disposal from all sources.
Our main measure takes the total allocation for the universal entitlement for each area under the EYNFF and adds on additional funding through the EYPP and DAF. We then deflate this measure, dividing through by the area cost adjustment for each local authority to strip out differences in costs. Finally, we divide through by the number of childcare hours to arrive at an average hourly rate. This retains gains due to the application of the funding floor, but tells us more about how far those ‘effective resources’ stretch in an area given local costs. We omit supplementary funding to areas for nursery schools as we consider this to address cost differences.
When studying changes over time, rather than focusing on the composite measure of resources that both includes EYPP funding and excludes delivery costs, we separately analyse the cost-adjusted EYNFF and the EYPP rate. This is to disentangle changes in different aspects of the system which would be lost in the composite measure.
For measuring 2023–24 funding, we use EYNFF rates initially allocated in January. This does not reflect additional changes announced in the March 2023 Budget, which started to come into effect in September through the Early Years Supplementary Grant (Department for Education, 2023a). This funding raised funding rates for each factor roughly equally, by around 6%; hence we do not expect major differences to the distribution of funding rates across areas as a result of this change.
On the other hand, our analysis of rates for different ‘factors’ and uplifts through EYPP and DAF – where we want to study changes over time – do reflect the March 2023 Budget’s changes. In this case, we calculate the rate for 2023–24 by taking a weighted average of the rate during April to August and the rate during September to March.
As well as additional needs uplifts included in the EYNFF, there are the Early Years Pupil Premium (EYPP) and the Disability Access Fund (DAF). These supplements operate somewhat differently from the national funding formula: rather than boosting the funding rate the local authority receives, which is then handed down to childcare providers equally, providers receive additional cash per eligible child; that is, funding follows the child.
Funding rates from the EYNFF therefore differ across places for three reasons: differences in local costs of childcare delivery, differences in needs of populations, and features of the funding formula such as funding floors. We construct a measure of resources per hour which differs from the EYNFF funding rate in two key ways (see Box 2.1 for details of its construction):
- First, we use a measure that removes area cost adjustments. This is because we are interested in how funding relates to the underlying need of areas rather than any differences in the costs of provision across areas. For instance, employing staff and leasing premises is significantly more expensive in London than in the rest of the country (the average cost adjustment was around 25% higher in London in the first year of the EYNFF than in the rest of England).
- Second, we incorporate funding through the EYPP and DAF to provide a more complete picture of the extent to which resources follow disadvantage. This is calculated as an average boost to a local authority’s hourly funding rate although, as discussed previously, in reality different providers within a local authority will receive different rates depending on how many deprived children they cater to.
This measure of resources per hour provides a comparable measure of resources allocated to each local authority, given differences in the costs of delivering childcare provision, and reflects the breadth of support available to areas, crucially by accounting for EYPP.
Patterns of early years funding across areas
Figure 2.6 maps the geographic allocation of early years hourly funding for 3- and 4-year-olds in 2023–24, net of area cost differences and inclusive of the EYPP and DAF. This shows how effective resources to deliver the 3- and 4-year-old universal entitlement are distributed across the country. The allocation of funding is mostly focused on more disadvantaged areas when we consider where in the country children have better or worse starts to life. On one measure of child development, ‘school readiness’, areas in the North West and, to a lesser extent, the North East and West Midlands perform poorly compared with the national average, while the South East and South West perform highly (Office for Health Improvement and Disparities, 2023). Figure 2.6 shows that resources are broadly allocated along these lines: areas in the North of the country and in the Midlands receive greater resource relative to the more affluent Home Counties and areas in the South of England. One notable exception to this pattern is London, where children do well in terms of ‘school readiness’ and many local authorities receive generous funding allocations, even once we account for higher delivery costs. The figure also shows, even using our net-of-area-costs measure, urban locations see higher resources, largely reflecting greater needs of populations.
Figure 2.6. Geographic distribution of funding for 3- and 4-year-olds in England (LHS), with London inset (RHS), 2023–24

Note: 3- and 4-year-old hourly funding rate from EYNFF, net of area cost adjustment and inclusive of EYPP and DAF. See Box 2.1 for more detail.
As hinted at in Figure 2.6, many differences across areas will be driven by different levels of need. In the EYNFF, the most significant uplifts are for areas with high rates of poverty (as measured by large numbers of primary school children registered for free school meals). In Figure 2.7, we explore the extent to which the funding system overall provides additional resources to local authorities with higher levels of disadvantage, as measured by the Index of Multiple Deprivation (IMD). Local authorities with above and below average population density are denoted urban and rural, respectively. London boroughs (which are all urban) are also highlighted.
Figure 2.7. Local authority deprivation, rurality and funding for 3- and 4-year-olds, 2023–24

Note: Rural = below average population density. Urban = above average population density. All London LAs are urban. Purple and yellow dotted lines represent lines of best fit for urban (excluding London) and rural places, respectively. 3- and 4-year-old hourly funding rate from EYNFF, net of area cost adjustment and inclusive of EYPP. See Box 2.1 for more detail.
As expected, since funding explicitly accounts for deprivation, there is a positive association between deprivation and funding. The most deprived fifth of local authorities receive hourly resources that are 12% higher than areas in the most affluent fifth. However, this represents less of a boost to the most deprived places than, for instance, the school funding system, where spending per pupil is about 15–20% higher in the most deprived fifth of areas. This is partly down to the EYNFF limiting spending for disadvantaged and high-needs children to around 10.5% of total spending (Department for Education, 2023c). In contrast, the schools National Funding Formula allocates around 17.4% of funding through additional needs factors (Department for Education, 2022).
Although more deprived areas receive higher early years funding overall, there remains a reasonable amount of variation in funding amongst areas with similar levels of deprivation, even after adjusting for delivery costs. This is particularly pronounced in London and largely reflects differences in need among other dimensions. For instance, Tower Hamlets has high numbers of children with English as an additional language (who receive an additional uplift in the funding formula) relative to other areas with similar levels of deprivation. Below, we study in greater detail uplifts given for deprivation and additional language needs.
Urban areas (including London) attract around 6.5% higher funding on average than less populated areas, even once differences in the costs of provision are accounted for (the raw gap is twice that). As Figure 2.7 shows, some of this can be explained by deprivation: more than 70% of areas in the most deprived fifth of LAs are urban. Urban areas, particularly in and around London and the Midlands, are also characterised by greater ethnic diversity, which feeds into higher funding rates via EAL uplifts.
Changes over time: EYNFF funding rate
The 2023–24 funding rates, which we have focused on so far, were constructed in a ‘bottom-up’ way based on the EYNFF. Before that, this step-by-step exercise was last conducted in 2017–18, when the EYNFF was introduced. During the intervening years, rates have been frozen and transitional protections unwound; from 2021–22, this was followed by uniform cash uplifts for all areas. Additionally, changes were made to the 2023–24 formula – for instance, around how cost adjustments are calculated or how much deprivation or disability uplifts are worth. Similarly, in recent years, the value of the EYPP uplift for disadvantaged children has been frozen. These changes may have impacted areas differently, making it important to understand how today’s rates compare with past funding levels.
In this subsection, we consider the EYNFF funding rate (net of cost adjustment) without the inclusion of EYPP, which we review in isolation in the final subsection. This is to better understand how different components of funding have changed.
Figure 2.8 shows each local authority’s EYNFF hourly funding rate net of area cost adjustments, relative to the average across areas in 2017–18 and 2023–24. This highlights the extent to which the generosity of resources a local authority receives under the EYNFF has changed relative to other local areas. We can see this by comparing the line of best fit (in green) to a ‘45-degree’ line (in dark grey). As well as indicating how funding has changed over time for different places, this comparison also speaks to the importance of applying the funding formula regularly. If places mostly retain their 2017–18 position (i.e. they lie on the 45-degree line), there may be less concern that rates are not updated in a ‘bottom-up’ way each year. On the other hand, if local authorities see large changes in their position, it suggests some could be losing out in in-between years.
As Figure 2.8 shows, the slope of the line of best fit is around half that of the 45-degree line, indicating movement in the ranking of local authorities between 2017–18 and 2023–24. This is partly down to the unwinding of transitional protections which is responsible for the biggest changes occurring at the extremes, i.e. for local areas considerably above or below the average rate in 2017–18. We discuss the impact of the withdrawal of transitional protections in more detail below.
Figure 2.8. Cost-adjusted real-terms funding rate for 3- and 4-year-olds relative to average, 2017–18 and 2023–24

Note: 3- and 4-year-old hourly funding rate from EYNFF, net of area cost adjustment. See Box 2.1 for more detail. De-meaned values constructed by removing the average for each year, weighted by part-time-equivalent places. Uses HM Treasury, GDP deflators, November 2023.
Even ignoring movement due to removal of transitional protections, the slope of the line of best fit (dotted purple line) is around two-thirds that of the 45-degree line, suggesting changes in the relative generosity of funding for certain areas between 2017–18 and 2023–24. Several areas experienced a significant change in position: Hammersmith & Fulham moved up by 19 ranks between the point at which transitional protections had disappeared and the latest application of the EYNFF, while Brighton fell by 28 ranks. These large adjustments suggest more frequent updating would guard against local areas losing out during the intervening years.
We can also examine differential changes in funding rates over this period between different regions of England. Figure 2.9 shows average real-terms funding rates (net of cost adjustments) for each region of England in 2017–18 and 2023–24. Every region experienced a real-terms decline. The biggest funding rate falls occurred in the South West (10%), Inner London (8.6%) and the West Midlands (6.6%). Only Outer London almost maintained the real value of resources over this period.
Figure 2.9. Cost-adjusted real-terms funding rate for 3- and 4-year-olds by region, 2017–18 and 2023–24

Note: 3- and 4-year-old hourly funding rate from EYNFF, net of area cost adjustment. See Box 2.1 for more detail. Constructed by calculating average for LAs in each region, weighted by part-time-equivalent places. Uses HM Treasury, GDP deflators, November 2023.
This variation is largely driven by the unwinding of transitional protections, which particularly affected Inner London areas and the South West. This was a design feature of the EYNFF which sought to allocate funding to different places predominantly based on local needs and smoothed out large adjustments in resources over multiple years for areas most impacted by the reallocation. Between the first funding rate allocation under the EYNFF and the point at which transitional protections had disappeared, rates had fallen in Inner London and the South West by 12% and 11% in real terms, respectively. In contrast, in a region that gained over the transitional period, Outer London, rates had fallen by only 1% in real terms by the time protections were unwound.
This represents a convergence of rates across regions but limited progress in terms of ‘levelling up’ inequalities across geographies. For instance, in 2017–18, the affluent South West region had a similar funding rate, net of cost adjustments, to the West Midlands, a much poorer region. Following the unwinding of transitional protections, funding in the South West is more in line with comparable, well-off regions such as Outer London or the South East. On the other hand, Inner London local authorities also ‘lost out’ with the removal of transitional protections. Although Inner London is not home to the very poorest local authorities (these are mostly in the North West, Yorkshire and the West Midlands), it has many pockets of high deprivation. Some of these poorest regions such as the North East were relatively protected in real terms over this period, while others such as the West Midlands saw bigger cuts (6.6% in real terms); hence the overall contribution to ‘levelling-up’ is mixed.
Changes over time: deprivation, high needs and EYPP
One way areas with more deprived or higher-needs populations receive greater resources is through uplifts in the EYNFF rate for deprivation and children with additional needs (EAL and disability). As was shown in Figure 2.7, these are important for distributing funding to areas where need is greater, yet the generosity of these supplements relative to the core funding rate has changed over time.
Except for provisions for disabled children, each uplift has fallen as a share of the base rate between 2017–18 and 2023–24. The most pronounced of these is the reduction in funding for deprived children, which stood at around 60% of the core funding rate in 2017–18 and is worth just 38% in 2023–24. This can be explained by recent rises in the number of children eligible for free school meals (FSM) in primary school, which is used to estimate the number of 3- and 4-year-olds who are disadvantaged. Transitional protections during the phasing-in of universal credit, which prevent many children moving off FSM, have led to a significant rise in the number of children eligible for FSM. Just under a quarter of pupils in England are eligible for means-tested FSM this year, compared with a long-run average of about one in six (Cribb et al., 2023). While the number of children designated as disadvantaged has risen substantially, the total amount of early years funding dedicated to disadvantage has not. Under the EYNFF, 8% of the total budget for the free entitlement can be earmarked for deprived children. This has remained constant while the number of children over which this funding is shared has increased, resulting in a fall in the uplift each disadvantaged child brings. It is likely that not every additional child eligible for FSM under universal credit transitional protections requires additional resources. However, a national funding formula where resource per disadvantaged child falls as deprivation rises seems particularly illogical.
On top of provisions through the EYNFF, the Early Years Pupil Premium and the Disability Access Fund provide areas with additional funding for low-income and high-needs children accessing the universal 15-hour entitlement. This is another mechanism to ensure that funding follows need.
Figure 2.10 plots the hourly EYPP rate and the annual per-child DAF amount between 2017–18 and 2023–24. The solid lines plot cash-terms amounts of these uplifts; the dashed lines show their real value, accounting for economy-wide inflation. EYPP and high-needs uplifts were frozen until 2022–23, representing a real-terms cut of 9% since 2017–18. The squeeze on resources felt on the ground was likely even greater, given that costs specific to the provision of childcare grew faster than economy-wide inflation over much of this period (Drayton and Farquharson, 2022).
Figure 2.10. Cash- and real-terms funding for Early Years Pupil Premium and Disability Access Fund

Note: Uses HM Treasury, GDP deflators, November 2023.
A significant rise to the DAF in 2022–23, followed by a smaller rise this year, has brought today’s disability uplift 13% higher in real terms than its value in 2017–18. By comparison, EYPP remains 2% below its 2017–18 real value, despite a 21% cash-terms top-up between 2021–22 and 2023–24. This highlights the corrosive effects of high inflation and comes on top of the reduction in funding for deprived children through the EYNFF discussed earlier. Total spending on EYPP is worth around twice the amount spent through the DAF and applies to many more children; therefore the rise in generosity for the DAF matters less than real-terms cuts to EYPP. This four-year freeze in EYPP is similar to the cash-terms freeze in the Pupil Premium in schools since 2015–16 (see Chapter 3 for further details), reflecting wider pressures on resources dedicated to disadvantaged children in the education system.
Finally, we study the breakdown of total funding, rather than hourly funding rates, to understand how early years funding is distributed for different purposes and whether this has changed over time. We focus on the universal 15-hour entitlement as EYPP and the Disability Access Fund only apply to these hours. Figure 2.11 considers, for 2017–18 and 2023–24, the share of funding spent on the core universal hours, disadvantaged children and high-needs children and the amount going to area costs.4
Figure 2.11. Composition of 3- and 4-year-old total spending on universal 15-hour entitlement

Note: Core spending is spending on universal hours. ‘High needs’ includes uplifts for disabled children and EAL children and the DAF. ‘Disadvantage’ includes uplift for FSM-eligible children and EYPP.
The vast majority of spending goes to the core delivery of the universal entitlement. In 2017–18, it made up 83% of spending, with around 9% allocated to disadvantage and 3% to high needs. The figure also highlights the 4% that went towards addressing differences in costs of provision across areas: in 2017–18, the average area cost adjustment was worth 18% of the base funding rate.
By 2023–24, spending on area cost adjustments have fallen slightly to 3%, reflecting updated data for premises costs and changes in methodology for estimating premises costs for different provider types. By comparison, information used to estimate staff costs has not been updated and relies on 2013–14 estimates (Department for Education, 2023c). The average area cost adjustment is now worth 13% of the base funding rate. The DfE outlines issues with the compatibility of more recent data in the cost adjusting methodology; nonetheless, relying on some cost estimates that are now a decade out of date is unwise in a time of high inflation.
The main takeaway from Figure 2.11, however, is how stable the shares are over time. This is achieved by design, with the share spent on disadvantage and high need constrained by limits invoked through the EYNFF. It also reflects EYPP seeing no real-terms growth.
2.4 Summary
The introduction of the Early Years National Funding Formula in 2017–18 was a sensible approach to ensure that areas receive funding for early years provision based on need and that funding could respond to changing circumstances. In 2023–24, funding is spread more evenly across regions (though there is certainly room for greater progressivity in this area) and roughly tracks measures of deprivation and high need.
The ability of the EYNFF to address inequalities, however, is significantly constrained by the cap on spending for additional needs to 10.5% of total funding. There is no obvious rationale for a system that responds to greater need by providing less resource per child and it is less generous than, say, allowances for additional needs in the national formula for school spending. In addition, despite setting up infrastructure to intelligently allocate funding, the low frequency with which rates are updated undermines the progressivity of the system, as the real value of funding held constant in cash terms is eroded over time. The most notable example of this is the freezing of the EYPP rate: its real value fell by (at least) 9% between 2017–18 and 2021–22. The cumulative impact of this reduction in resources for disadvantaged children is particularly concerning given the additional setbacks these children experienced during the pandemic.
As well as squeezing providers’ resources, an erratic approach to updating rates generates uncertainty around future funding. With the government expected to deliver even more free childcare over the coming years, it becomes increasingly important to have a sound process for setting funding rates.
3. Schools
The government has chosen to increase school spending in England at recent spending reviews. The core schools budget in England has risen by 10% in real terms from £52.6 billion in 2019–20 to £57.6 billion in 2023–24, and is due to further rise by another 2% to reach £58.6 billion in 2024–25 (all in 2023–24 prices). As pupil numbers have been relatively stable over this period, total spending per pupil is expected to grow by 10% in real terms between 2019–20 and 2024–25. However, rising inflation has eroded the purchasing power of these funding increases, and large cash-terms increases in staff pay have led to schools facing faster increases in costs than overall inflation. In Section 3.1, we analyse trends in school spending per pupil, projections for the future and how cost rises are affecting the purchasing power of school budgets.
The government has also undertaken a major reform of the school funding system through the introduction of the National Funding Formula for schools in April 2018. It has consistently emphasised the role of schools in ‘levelling up’ poorer areas of the country. Five years on from the introduction of the National Funding Formula, we analyse how funding is spread across schools and areas by levels of deprivation (Sections 3.2 and 3.3). This shows that more deprived schools still receive higher levels of spending per pupil, but this advantage has narrowed over time, with the most deprived schools seeing the biggest cuts.
Throughout this chapter, we focus on current or day-to-day spending on schools (i.e. excluding capital spending). In light of the safety concerns over school buildings, we have published separate analysis of trends in school capital spending (Sibieta, 2023a). This shows that school capital spending in England is currently about 26% lower than in the late 2000s (comparing the three-year average up to 2023–24 with that up to 2008–09). For further details on the methods used to analyse school spending, see https://ifs.org.uk/education-spending/methods-and-data.
3.1 Total school spending per pupil
Figure 3.1 shows total school spending per pupil aged 3–19 between 2003–04 and 2023–24 broken down into four different components:
- Funding allocated to schools. This includes funding directly allocated to schools and early years providers. Early years funding is included in primary school budgets for past years. We cannot exclude this for all years, so we include early years funding for all years to maintain consistency. This also includes funding for special schools and alternative provision.
- Local authority spending. This includes central spending on a range of services for pupils with special educational needs, admissions, transport and other services.
- Sixth-form funding. This is funding provided to schools for pupils aged 16–19. We include this given that it is often included within total secondary school expenditure figures.
- Extra funding for employer pension contributions. From September 2019, schools received about £1.5 billion in extra funding to meet the cost of higher employer pension contributions. We often present numbers with and without these figures for comparisons over time as the funding was directly intended to compensate schools for higher costs. Employer pension contributions are to rise by a further 5 percentage points from April 2024. The government has committed to compensating state-funded schools and colleges for the extra costs of this change in 2024–25, with future years considered in the next spending review.5
Figure 3.1. Total school spending per pupil by component (2023–24 prices)

Note and source: See Methods and data. HM Treasury, GDP deflators, November 2023. No data are available for 2020–21, so this is imputed based on a constant real-terms growth rate between 2019–20 and 2021–22.
Combining all these factors, we calculate total school spending as £65.5 billion in 2023–24. This is higher than the core schools budget for England presented by the government, £57.6 billion in 2023–24. This can be mostly explained by the fact that we include £3.1 billion in post-16 funding and nearly £3.5 billion in early years funding, as well as additional services provided by local authorities that are funded through the wider local government settlement.
In 2003–04 (the earliest year for which we can produce this consistent set of figures), total school spending stood at about £6,300 per pupil in 2023–24 prices. This rose by 23% in real terms up to 2009–10, reaching a high point of £7,800 per pupil. After 2009–10, spending per pupil fell by 9% in real terms to reach £7,100 in 2019–20, taking spending per pupil back to around the level last seen in about 2006.
Up to 2009–10, each of the components rose by similar amounts. After 2009–10, the different components evolved very differently. Per-pupil funding provided to schools rose by around 4% in real terms between 2009–10 and 2019–20. In contrast, local authority spending on services fell by 57% over the same period. A large part of this contrasting pattern is mechanical, reflecting a transfer of funding and responsibilities from local authorities to both academies and maintained schools. There was also a big drop in sixth-form funding. As we show in Chapter 4, school sixth-form funding per student fell 24% over this period.
These figures represent our best estimates of the change in total public spending available for school services in England over this period. They include the effect of cuts to local authority services, many of which schools will have had to fund from their existing budgets, and cuts to school sixth-form funding, which will have put pressure on secondary school budgets. If we exclude sixth-form funding, school spending per pupil aged under 16 fell by 8% in real terms between 2009–10 and 2019–20. However, if we were able to exclude early years funding for all years, this cut would become larger as early years funding grew in real terms over this period.
Interestingly, a large amount of the real-terms fall in spending per pupil since 2009–10 can be accounted for by the fact that total spending has not kept pace with fast growth in pupil numbers. Total spending on schools (as calculated for Figure 3.1) rose by about 1–2% in real terms between 2009–10 and 2019–20, whilst pupil numbers grew by 11% over the same period. The net result is the 9% real-terms fall in spending per pupil that we observe.
Since 2019–20, school spending per pupil has begun to grow again in real terms, reflecting extra funding provided in the 2019 and 2021 spending reviews, as well £2.3 billion extra funding from 2023–24 as announced in the 2022 Autumn Statement. As a result, between 2019–20 and 2023–24, total school spending per pupil grew by 5% in real terms, partially reversing past cuts, or by 7% if we include funding to compensate schools for extra employer pension contributions.
Figure 3.2 projects total school spending per pupil up to 2024–25 based on the latest government spending plans and forecasts for pupil numbers and inflation. This is shown relative to 2009–10, the most recent high-point in school spending per pupil in real terms. This includes the effects of an extra £825 million over a full year in school funding announced in July 2023 to cover the costs of increasing the average teacher pay offer to 6.5% from September 2023. For consistency with government figures, we focus on total school spending including compensation for higher employer pension contributions. We present two scenarios. The first shows actual and expected future real-terms trends after adjusting for economy-wide inflation based on the GDP deflator. The second uses an estimated measure of schools-specific cost inflation, which includes actual increases in staff salaries and non-staff costs up to 2023–24, and an assumed 3% increase in staff salaries for 2024–25.
Figure 3.2. Total school spending per pupil (actual spending up to 2023–24, projected to 2024–25), 2009–10 = 100

Note and source: See Methods and data for cash-terms spending per pupil up to 2023–24. Cash-terms spending per pupil forecast for 2024–25 based on figures for the core schools budget published in the Autumn Statement 2022, National pupil projections, and figures provided by the Department for Education. HM Treasury, GDP deflators, November 2023. Schools-specific cost inflation measures defined in Methods and data.
We do not have the necessary data to extend these series back in the same way before 2019–20. However, our previous analysis has compared trends in school spending per pupil (based on economy-wide inflation) with trends assuming staff costs follow trends in overall public sector pay per head. Under both scenarios, we found that school spending per pupil declined by about 9% in real terms between 2009–10 and 2019–20 (Britton et al., 2020). Whilst freezes in public sector pay in 2011 and 2012 initially kept school costs down, increases in employer pension contributions and National Insurance contributions increased school costs in 2016 and 2017.
Spending per pupil increased in real terms using both measures of inflation up to 2021–22, with a brief dip in 2022–23. Based on economy-wide inflation, school spending per pupil is then expected to grow further in real terms up to 2024–25, taking it back to 2010 levels. We see a very different picture if we account for schools-specific cost inflation, with the purchasing power of school budgets declining slightly in real terms up to 2024–25. This would leave the real-terms level of school budgets about 4% lower than they were in 2009–10.
The reason for this divergence results from the specific way in which the GDP deflator measure of economy-wide inflation is calculated. In particular, it focuses on domestic prices and largely excludes the effects of rises in the price of imports. This matters a great deal in the current situation as imports of food and energy have played a big role in driving overall inflation.
The GDP deflator is currently forecast to grow by 6.1% in 2023–24, whilst our measure of schools-specific costs is due to grow by 7.2%. The faster growth in school costs is driven by fast growth in staff salaries (such as the 6.5% growth in teacher pay in September 2023 and an expected 8% growth in other staff pay in 2023–24). Schools will also face rises in non-staff costs, which are probably best reflected in the expected 6.1% growth in the Consumer Prices Index in 2023–24.
For 2024–25, the GDP deflator is currently forecast to grow by 1.7%. In contrast, we project a 3.8% increase in school costs, which is only just covered by a 3.8% cash-terms increase in school funding per pupil. As part of our estimates for school costs, we assume a 3% increase in staff salaries, matching OBR projections for CPI inflation in 2024–25. The actual increases in school costs will depend on actual pay awards and the out-turn for inflation. However, the risks are likely to be on the upside for costs. There is still evidence of significant recruitment and retention difficulties in the teacher and support staff labour market (McLean, Worth and Faulkner-Ellis, 2023). The government is also committed to recruiting extra teachers as part of plans to reform the post-16 system (White et al., 2023). Furthermore, the National Living Wage is due to rise by 10% in April 20246 and local government employers have made it clear that they aim to maintain ‘headroom’ in school support staff pay relative to the National Living Wage. This suggests school support staff pay is likely to increase by significantly more than 3%. An increase of 6.5% for school support staff would add a further 1 percentage point to the growth in school costs in 2024–25.
Average spending by primary and secondary schools
Figure 3.3 shows our estimates for the level of primary and secondary school spending per pupil in England from the late 1970s through to 2021–22 (in 2023–24 prices), together with projections up to 2024–25. Spending levels exclude temporary COVID-related grants. Actual figures up to 2021–22 are based on spending levels by individual schools, which excludes spending undertaken by local authorities and spending on special schools. The figures are therefore lower than those shown in Figure 3.1. We produce projections based on both the GDP deflator and our own estimates of the growth in schools-specific cost.
Figure 3.3. Spending per pupil in primary and secondary schools (2023–24 prices), actual up to 2021–22 and forecasts up to 2024–25
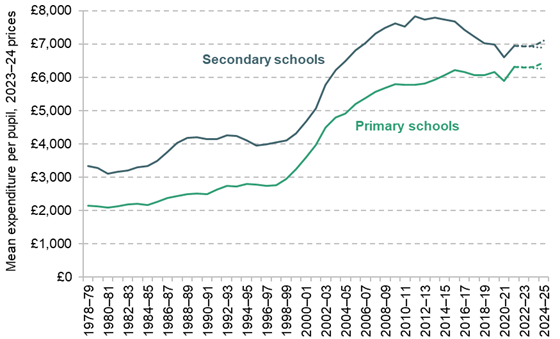
Note and source: Dashed lines are projections and dotted lines use schools-specific cost inflation (both based on Figure 3.2). See Methods and data. HM Treasury, GDP deflators, November 2023.
Spending per pupil has evolved in a number of distinct phases:
- Modest growth over the 1980s and 1990s. During the 1980s and 1990s, primary school spending per pupil grew by 2.1% per year, on average, in real terms and secondary school spending per pupil grew by slightly less (1.4% per year, on average). This includes a 6% real-terms cut in secondary school spending per pupil during the early 1990s, when primary school spending per pupil was largely constant in real terms.
- Rapid growth over the 2000s. From 1999–2000 onwards, spending per pupil grew rapidly, with growth of nearly 6% per year in real terms for primary and secondary schools over the 2000s. This led primary school spending per pupil to rise from £3,200 per pupil in 1999–2000 to reach £5,800 by 2009–10, whilst secondary school spending per pupil grew from £4,300 to £7,600 per pupil (all in 2023–24 prices).
- Funding squeeze since 2010 and increased role of individual schools. There has been a squeeze on funding since 2010–11. This has not, however, always been visible in the spending levels of individual schools. This is because maintained schools and academies both received extra funding to take on responsibility for services previously provided by local authorities (i.e. this was a transfer of funding, rather than an increase in funding for existing activities). As a result, over the decade between 2009–10 and 2019–20, primary school spending per pupil grew by 6% in real terms, whilst secondary school spending per pupil fell by 8%. This averages out to an effective real-terms freeze on spending per pupil by individual schools. Secondary schools saw a worse picture partly due to big reductions in school sixth-form funding (see Chapter 4).
- Return of growth up to 2024. Core school spending per pupil is expected to grow in real terms through to 2024. Combining actual growth in spending per pupil and forecast growth up to 2024–25, primary school spending per pupil is likely to grow by 5% in real terms between 2019–20 and 2024–25, and secondary school spending per pupil by 2% (both adjusting for economy-wide inflation). The expected growth rates are lower when we instead account for our estimates of school costs growth, with 2% real-terms growth in primary school spending per pupil and a 1% real-terms fall in secondary school spending per pupil (leaving it about 10% lower in real terms than in 2009–10).
Two long-term trends emerge from this analysis. First, the gap between secondary and primary school spending has fallen significantly over time. In the 1980s, secondary school spending per pupil was about 56% higher than primary school spending per pupil. This narrowed to 49% in the 1990s and then to 30% in the 2000s. This narrowing continued through the 2010s, and the secondary:primary school funding difference is due to be only 10% in 2024–25. Some of the recent narrowing reflects that primary schools have benefited more from the transfer of responsibilities and funding from local authorities to schools. However, this is also clearly part of a long-term relative shift in funding and resources from secondary to primary schools.
Second, there have clearly been cycles in the growth of spending per pupil. Modest growth or cuts during the 1980s and 1990s were followed by large increases during the 2000s, which were in turn followed by cuts and freezes during the 2010s. One could argue that squeezes in funding per pupil during the 2010s were less concerning because they followed on from big increases during the 2000s. But one could equally argue that the large increases during the 2000s were needed to catch up, following the modest rises and cuts during the 1980s and 1990s. Unfortunately, none of these trends provides any definitive guide to a right or target level of spending per pupil. Instead, decisions on school spending are best guided by objectives for the school system, the extent to which extra resources are needed to achieve those objectives, and the state of the labour market for teachers and support staff.
3.2 Differences across schools by levels of deprivation
In this section, we examine differences in spending per pupil by levels of deprivation across schools. This represents a key consideration given the government’s focus on ‘levelling up’ poorer areas of the country. Empirical evidence also suggests that focusing additional resources on schools facing higher levels of deprivation could be an important tool in narrowing the achievement gap between children from rich and poor families (Jackson, Johnson and Persico, 2016; Gibbons, McNally and Viarengo, 2018; Jackson, 2020).
For this analysis, we split schools into five equally sized groups or quintiles of deprivation based on the share of pupils eligible for means-tested free school meals (FSM) in each individual year. For background, Figure 3.4 shows the average share of pupils eligible for FSM across these quintiles for primary and secondary schools between 2010–11 and 2021–22 (the last year covered by school-level data for actual spending levels). This illustrates the key national trends over time, with a reduction in the share of pupils eligible for FSM up to about 2017, followed by a substantial rise across all quintiles up to 2021. Some of this recent rise represents greater eligibility for FSM under universal credit, transitional protections for families moving onto universal credit and a genuine increase in hardship.
Across most quintiles, this trend has left the share of pupils eligible for FSM in 2021–22 a little bit higher than was the case in 2010–11. For example, the share of pupils eligible for FSM increased from 4% in 2010–11 to 7% in 2021–22 amongst the least deprived primary and secondary schools. Amongst the most deprived primary schools, the share of pupils eligible for FSM increased from 44% to 46% over the same period, and it rose from 33% to 40% amongst the most deprived secondary schools. This has left the differences in deprivation between the most and least deprived quintiles about the same as they were a decade ago.
The make-up of the quintiles can change over time as schools become more or less deprived. However, a large element of deprivation is persistent: about two-thirds of pupils eligible for FSM have been eligible for 80% of their school career (Cardim-Dias and Sibieta, 2022). The main change over time has been the reducing share of the most deprived quintile made up by schools in London. In 2010–11, 29% of the most deprived primary school quintile was made up by pupils in London, and 34% for secondary schools. By 2021–22, only 14% of the most deprived secondary quintile was made up by schools in London, and about 20% for primary schools.
Figure 3.4. Share of pupils eligible for free school meals by quintile of eligibility for free school meals

Note and source: See Methods and data.
Figure 3.5 Spending per pupil by quintile of eligibility for free school meals, relative to least deprived quintile

Note and source: See Methods and data. HM Treasury, GDP deflators, November 2023.
Figure 3.5 shows the level of spending per pupil across each quintile relative to the least deprived quintile. It provides a guide to the long-run changes in the targeting of funding towards more deprived schools. Over the 2000s, all schools saw increases in spending per pupil, but they were largest for the most deprived schools. This partly represented the effect of a range of specific grants directly targeted at more deprived schools. As a result, the gap in spending per pupil between the most and least deprived schools rose from around 20% in 2000–01 for primary and secondary schools to reach nearly 35% by 2010–11. Up to 2014–15, the difference in funding between the most and least deprived schools remained around 35%. After that, the difference fell to about 21–22% in 2021–22, rolling back all of the increase that took place over the 2000s.
Some of this reduction reflects the reducing share of the most deprived quintile made up by schools in London, which receive higher levels of funding to pay London weighting for teacher salaries. To account for this, we adjust school spending to look at differences before the ‘ area cost adjustment’ is applied. We focus on the period since 2010–11, when relative differences in costs across areas have been mostly constant (this is less true going back in time). Belfield and Sibieta (2016) provide analysis of longer-term trends.
Figure 3.6 shows the relative differences across quintiles since 2010–11 and adjusting for area costs. This shows a remarkably similar pattern across primary and secondary schools. Between 2010–11 and about 2013/2014, spending per pupil in the most deprived quintile was about 30% higher than in the least deprived quintile. After 2013/2014, this declined gradually over time to reach about 21% in 2021–22. Therefore, the difference between the most and least deprived quintiles is clearly lower in 2010–11 after we account for area costs (30% instead of 35% in raw terms). However, we still see a large decline from 30% to 20% since 2010, with much of the decline occurring after 2013/2014.
Figure 3.6. Spending per pupil by quintile of eligibility for free school meals, relative to least deprived quintile and after adjusting for area costs
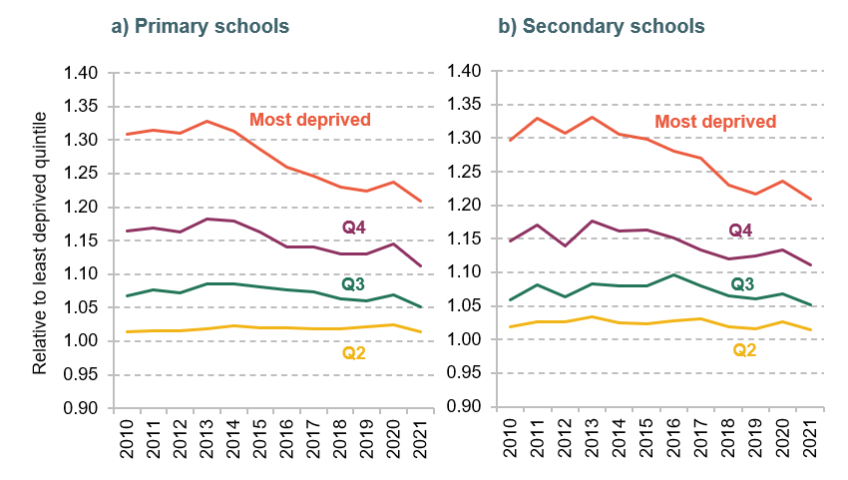
Note and source: See Methods and data. HM Treasury, GDP deflators, November 2023.
Figure 3.7. Real-terms change in spending per pupil by quintile of eligibility for free school meals between 2010–11 and 2021–22: London and the rest of England

Note and source: See Methods and data. HM Treasury, GDP deflators, November 2023.
Figure 3.7 then shows the change in primary and secondary spending per pupil by quintile between 2010–11 and 2021–22 for all schools (after adjusting for area costs), and broken down by whether they were in London or the rest of England (the quintiles are still determined on a national level by year).
The first clear difference is the fact that primary schools have experienced real-terms growth in spending per pupil, and secondary schools have experienced real-terms cuts. This reflects the earlier point that primary schools are likely to have benefited more from the transfer of funding and responsibilities from local authorities to individual schools, a reduction in the secondary:primary funding ratio over time and greater cuts to school sixth-form funding.
Amongst primary schools, we see smaller real-terms increases in spending per pupil for the most deprived primary schools (4%) than for the least deprived ones (13%). Lower growth for deprived primary schools seems to mostly reflect lower increases for the most deprived primary schools outside London (3%). Within London, we see spending-per-pupil increases in excess of 10%, and even larger in the middle quintiles. This will partially reflect the fact that schools in London have been becoming relatively less deprived over time and have shifted to lower quintiles. Funding will only slowly adjust to this change as various aspects of the funding system, such as the minimum funding guarantee, will preserve historical funding levels to some extent.
We see a similar process at work for secondary schools, except the overall picture is one of real-terms cuts. The most deprived secondary schools saw a real-terms cut of 12% between 2010–11 and 2021–22, compared with 5% for the least deprived secondary schools. This was mostly driven by larger cuts of 13% amongst the most deprived secondary schools outside London. Within London, we see mostly smaller and similar cuts across quintiles.
Changes to the school funding system
In order to explain why school funding has fallen more amongst the most deprived schools, it is necessary to briefly set out how the school funding system operates. The main source of funding for schools is the National Funding Formula, which was introduced in April 2018. The Department for Education has a central formula, which incorporates extra funding for schools in London that need to pay higher salaries, higher funding for schools with more deprived pupils and higher funding for small schools and those in sparsely populated areas, as well as a series of other factors, such as low prior attainment and whether pupils speak English as an additional language. This formula is used to calculate total funding across local authorities. It represents a substantial improvement on the pre-2018 system, when levels of funding per student across local authorities were essentially rolled forwards and no account was taken of the changing circumstances of different local authorities.
Local authorities then operate their own school funding formulae, but, since 2013–14, they can only use a specific set of factors, which largely match those used in the national formula. Essentially, local authorities can tweak the national formula, but cannot make big or complicated changes. These local funding formulae incorporate extra funding for more deprived schools and for small schools in sparsely populated areas, as well as other factors. Academies are treated in an identical way to local-authority-maintained schools in the same local authority. The government has a long-term ambition to move towards a single national formula across all schools in England, replacing the more than 150 local formulae with a single national formula. It has been gradually encouraging local authorities to move in this direction.
The system also incorporates a number of mechanisms that smooth out changes in funding from year to year. First, the National Funding Formula incorporates a ‘funding floor’ that sets a minimum increase in funding attracted by individual schools. This mainly smooths changes in funding allocated to local authorities, and prevents local authorities from receiving big decreases in any given year. Second, there is a ‘minimum funding guarantee’ that provides a minimum increase (or decrease) in funding per pupil actually allocated to individual schools each year. This has the effect of smoothing any reductions in funding per pupil, such as if a school is becoming less deprived over time. Third, the National Funding Formula incorporates statutory ‘minimum funding levels’. If the funding level determined by the main elements of the formula give a funding level below the minimum funding level, then schools’ allocations are topped up to the minimum levels. These minimum funding levels were made statutory from 2020–21 and local authorities are obliged to use them in their own formulae.
These smoothing mechanisms have a number of implications for trends over time. First, if the national and local formulae imply reductions in funding per pupil, such as if an area or school is becoming less deprived over time, then these changes will happen slowly. This helps explain why we see more positive changes in funding per pupil for schools in London in the middle quintiles. These schools have become less deprived in relative terms over time, but smoothing mechanisms preserve some of the higher funding they received when they were more deprived. Second, minimum funding levels will have disproportionately benefited schools with lower levels of deprivation, as these are the schools that would otherwise receive lower funding. This will already form a direct, major explanation for why the least deprived schools have seen more positive (or less negative) funding changes over time. For 2021–22, Andrews (2020) estimates that about 20% of schools had their funding set by these minimum funding levels.
On top of the National Funding Formula, there is a series of national grants that go direct to schools. These include the Pupil Premium, which represents a fixed extra amount for each disadvantaged student. They also include a changing set of grants mainly focused on supporting schools with unexpected cost rises, such as the Teacher Pay Grant or the School Supplementary Grant. With the exception of the Pupil Premium, these are normally folded into the National Funding Formula the year after they are introduced (or the earliest opportunity).
Given the structure of the school funding system, it is important to analyse deprivation funding at both the national and local levels. Smoothing mechanisms mean we cannot directly decompose the changes in funding per pupil by levels of disadvantage. However, this analysis does indicate the relative importance of the different factors and processes explaining the higher levels of spending cuts experienced by more deprived schools. Furthermore, the changes to the funding factors will determine the long-run implications for different types of schools, especially when a direct school-level national funding formula is introduced.
Changing levels of funding for deprivation at the national level
In Figure 3.8, we illustrate the role of changing funding factors for deprivation at the national level. These are the factors directly controlled by the Department for Education. In particular, we show the real-terms level of the Pupil Premium for disadvantaged pupils in primary and secondary schools (those who have been eligible for FSM in the past six years). We also show the real-terms level of key funding factors in the National Funding Formula – the levels of funding for a pupil eligible for FSM and for each pupil living in the most deprived areas (as defined by the Income Deprivation Affecting Children Index, IDACI). These latter funding factors are only available since the National Funding Formula was introduced in 2018–19, but can be tracked up to 2024–25.
Figure 3.8. Pupil Premium and National Funding Formula factors targeted at deprivation over time, 2023–24 prices

Note and source: Education and Skills Funding Agency, Pupil premium: allocations and conditions of grant 2023–24 and previous years. Department for Education, National funding formula for schools and high needs, 2018–19 to 2024–25. FSM total combines amount for current eligibility and whether pupils have been eligible in the past six years. HM Treasury, GDP deflators, November 2023.
The Pupil Premium was introduced in April 2011 to provide extra funding for disadvantaged pupils. It provides a fixed extra amount for each pupil eligible for FSM in the past six years, as well as extra amounts for pupils from families in the armed services and for children in care. Over £2.5 billion of the £2.7 billion total allocation in 2023–24 is taken up by the extra amounts for pupils who have been eligible for FSM, which is what we focus on here.7
The Pupil Premium reached a real-terms peak around 2014/2015, amounting to £1,700 for disadvantaged pupils in primary schools and £1,200 for disadvantaged pupils in secondary schools (all in 2023–24 prices). A higher level was set in primary schools on the grounds of the greater effectiveness of early intervention to tackle the attainment gap between children from rich and poor families. The level was mostly frozen in cash terms up to 2021–22, leading to real-terms declines of 10% between 2014–15 and 2021–22 (the period covered by school-level data). There were cash-terms increases in the rates in 2022–23 and 2023–24, but these did not fully keep pace with overall inflation, and the Pupil Premium for disadvantaged students is about 14% lower in real terms in 2023–24 than in 2014–15.
These real-terms reductions in the Pupil Premium will naturally have a bigger impact on schools with more disadvantaged students. Indeed, if the Pupil Premium had kept pace with overall inflation, then spending per student amongst the most deprived schools would have been about 1–1.5% higher than was actually the case.
Figure 3.8 also shows the amounts provided by the Department for Education through the National Funding Formula (NFF). The dashed lines are the total amounts provided for pupils currently eligible for FSM (combining two specific factors, one for those currently eligible and a further factor for those who have ever been eligible in the past six years). The dotted lines are the funding levels for a pupil living in the most deprived areas (as defined by IDACI). In contrast to the Pupil Premium, these deprivation funding factors in the NFF are higher for secondary schools than for primary schools. This reflects the fact that when the NFF was first introduced, most elements sought to preserve past funding priorities.
Between the introduction of the NFF in 2018–19 and the last year covered by our school-level data in 2021–22, we observe 3–4% real-terms declines in both the FSM and IDACI funding factors. These will have reduced the amount of funding available to more deprived local authorities and will, therefore, have likely contributed to the bigger cuts experienced by more deprived schools (subject to the operation of the funding floor). However, to see the full effect, we need to examine the actual amounts provided by local authorities, which we turn to below.
Before examining the amounts of deprivation funding actually provided by local authorities, it is important to note that there has actually been substantial growth in the amounts provided by the Department for Education through the NFF for more recent years. As a result, the total amount provided for a pupil eligible for FSM in 2024–25 will be 8% higher in real terms for primary schools than it was in 2018–19, and about 12% higher in secondary schools. There will be smaller increases for factors associated with IDACI, with the amount for the most deprived group still being about 4–5% lower in real terms than in 2018–19.
Changing levels of funding for deprivation at the local level
The crucial factors for determining the level of extra funding received by deprived schools are the amounts provided by local authorities through their own local formulae. These amounts naturally vary across local authorities and they can prioritise different factors (e.g. the relative role of funding factors associated with FSM and IDACI). With this in mind, Figure 3.9 summarises the level of deprivation funding provided by local authorities by showing the total level of deprivation funding per pupil eligible for FSM. This is shown since the introduction of simpler formulae in 2013–14 through to the most recent data available for 2023–24. We also show the 25th and 75th percentiles to get a sense of the spread across local authorities.
In 2013–14, the total level of deprivation funding per FSM pupil was, on average across local authorities, £3,300 in secondary schools and £2,500 in primary schools. There was also significant variation across local authorities. For example, a quarter of local authorities were providing £600 more than the average amount for secondary schools and a quarter were providing £1,100 less than the average. Such variation was slightly smaller for primary schools.
Between 2013–14 and 2018–19, the level of deprivation funding per FSM pupil grew in real terms by 15% for primary schools and 22% for secondary schools. However, since the introduction of the NFF in 2018, the total level of deprivation funding per FSM pupil has substantially declined and the variation across local authorities has shrunk dramatically.
Between 2018–19 and 2021–22, the average level of deprivation funding per FSM pupil fell in real terms by 28% for primary schools and 26% for secondary schools. This decline will play a major role in explaining the higher levels of cuts experienced by more deprived schools up to 2021–22 (the last year covered by our school-level data). Further real-terms declines occurred in 2022–23.
Figure 3.9. Levels of deprivation funding within local authority funding formulae over time, 2023–24 prices

Source: Authors’ calculations using Department for Education, Schools block funding formulae 2023 to 2024 and previous years. HM Treasury, GDP deflators, November 2023.
These were followed by real-terms freezes or small falls in 2023–24, which contrast very strongly with the increases in NFF rates for FSM pupils in primary schools (17%) and secondary schools (20%) seen in Figure 3.8. This creates natural concerns as to whether further increases in national funding rates for deprivation will be passed on in 2024–25.
We cannot directly estimate the effect of these changes in local funding formulae on the higher cuts experienced by more deprived schools. The minimum funding guarantee will smooth out and limit the year-on-year changes. However, if local deprivation funding had been maintained at 2015 levels in real terms, then spending per pupil would have been 3–4% higher in 2021–22 than was actually the case. This shows the importance of these changes in local funding formulae, which will also drive the long-term picture for deprivation funding.
Another key trend is the substantial reduction in the variation across local authorities. In 2017–18, just before the introduction of the NFF, around one in four local authorities were providing total deprivation funding per FSM pupil that represented less than about 70% of the average amount, whilst about one in four provided at least 18% more than the average amount. By 2023–24, this variation had substantially declined. At this point, one in four local authorities were providing less than 90% of the average amount and one in four were providing at least 10% more than the average amount. Interestingly, we also see bigger reductions amongst local authorities that used to provide the largest amounts of deprivation funding per FSM pupil, with the 75th percentile declining in real terms by 36% for primary schools and 31% for secondary schools between 2017–18 and 2023–24. This compares with a 14% real-terms reduction in the 25th percentile for primary schools and a 5% real-terms reduction in the 25th percentile for secondary schools over the same period. The bigger falls in high levels of deprivation funding per FSM pupil have therefore been a key driver in the real-terms falls in average deprivation funding per FSM pupil in primary and secondary schools. Quite literally, there has been a ‘levelling-down’ in deprivation funding per FSM pupil across local authorities.
The declines in deprivation funding levels within local authority funding formulae are unlikely to be purely driven by local choices. Instead, they are much more likely to reflect choices and constraints created by central government. First, as noted above, we see 3–4% real-terms declines in the value of NFF factors associated with deprivation between 2018–19 and 2021–22 (the last year of school-level data).
Second, the NFF factors associated with deprivation were introduced at lower rates than those set by local authorities. This was partly a deliberate choice to provide extra funding for low prior attainment (see later in this section). The effects on deprivation funding are illustrated in Figure 3.10, which shows the maximum funding for deprivation in the NFF (funding for FSM factors plus funding for the most deprived IDACI group) and the average level of deprivation funding per FSM pupil in local funding formulae for 2018–19, 2021–22 and 2023–24. As can be seen, the maximum levels of deprivation funding per pupil within the NFF in 2018–19 were well below the level of deprivation funding per FSM pupil provided by local authorities (33% lower in the case of primary schools and 40% for secondary schools). Over time, the level of deprivation funding provided by local authorities has come down to meet the national values, and the variation across local authorities has narrowed considerably (with slightly larger reductions amongst those previously providing relatively high amounts). This is unsurprising as local authorities must make choices within the funding envelope provided by the Department for Education. There is also substantial encouragement and policy direction towards harmonising funding factors across local authorities towards NFF values, as part of an ambition to create a single national funding formula. Indeed, the NFF rates will eventually replace the local versions.
Figure 3.10. Comparing National Funding Formula rates with actual deprivation funding per FSM pupil provided by local authorities, 2023–24 prices

Note and source: Authors’ calculations based on Figures 3.8 and 3.9. The black lines indicate the 25th and 75th percentiles.
Changing levels of funding for low prior attainment
So far, we have focused on formula factors based on socio-economic disadvantage. However, the funding system also allocates funding on the basis of low prior attainment. For primary schools, this is targeted at pupils who did not achieve a ‘good’ level of development in the Early Years Foundation Stage at age 5. For secondary schools, it is currently targeted at pupils who did not achieve the expected levels in reading, writing or maths at age 11. On the introduction of the NFF in 2018, the government deliberately chose to focus more funding on low prior attainment on the basis that this was a more direct measure of educational disadvantage. Thus it is likely that some deprivation funding has been replaced by low prior attainment funding.
Figure 3.11 illustrates this by showing the average level of the low prior attainment factor in local authority funding formulae, together with the NFF national values from 2018–19 onwards, both in real terms. As can be seen, the NFF values were (deliberately) set above the values previously used in local funding formulae, particularly for secondary schools. As a result, there was a large real-terms increase in low prior attainment factor values in local funding formulae in 2018–19, about an extra £430 or 33% for each pupil with low prior attainment in secondary schools and about an extra £150 or 15% for each one in primary schools.
Since 2018–19, the values used for low prior attainment in local funding formulae have been largely constant in real terms and now effectively mirror the national values. However, the NFF values have declined in real terms by 10% for primary schools and 7% for secondary schools.
Figure 3.11. Levels of funding for low prior attainment within local authority funding formulae and the National Funding Formula over time, 2023–24 prices

Note and source: Authors’ calculations using Department for Education, Schools block funding formulae 2023 to 2024 and previous years. HM Treasury, GDP deflators, November 2023. 2013–14 is not included as different measures were used in that year.
The net effect of all these changes is that schools with more deprived pupils with low prior attainment will have been partly compensated for lost funding for socio-economic disadvantage by increased funding for low prior attainment. This may help explain why the very large real-terms decreases in local deprivation funding seen in Figure 3.9 did not translate into larger spending cuts for deprived schools overall. It will also spread disadvantage funding more widely to a different set of schools with low prior attainment but lower levels of deprivation.
Importantly, however, the increased funding for low prior attainment will only partially compensate schools with high levels of deprivation. To see this, we can estimate that a pupil with low prior attainment and eligible for FSM would have attracted about £3,700 per year in the period from 2015 to 2017 (under local funding formulae), and this declined to about £3,100 by 2023–24. For secondary schools, this amount has declined from about £4,700–5,000 to £4,400 over the same period. Furthermore, there have been real-terms cuts to the NFF values for low prior attainment.
Summarising changes in deprivation funding across schools
In summary, there has been a decline in the extra funding targeted at the most socio-economically deprived schools over time. Some of this decline simply reflects the changing geography of deprivation and funding moving around the country to reflect this. In particular, a smaller share of the most deprived schools are now located in London, which gets higher funding to pay higher teacher salaries. However, even after accounting for this, the funding advantage for the most deprived schools still declines from 31% in 2010–11 to 21% in 2021–22. The most deprived schools outside London have seen the most negative changes over time, with the most deprived secondary schools outside London seeing real-terms cuts of 13% between 2010–11 and 2021–22.
A range of changes can help explain the larger cuts for more deprived schools. First, the Pupil Premium has not kept pace with overall inflation over time. Second, the introduction of statutory minimum funding levels in 2020 will have disproportionately benefited less deprived schools, and reduced the share of total funding focused on more deprived schools. Third, funding factors for deprivation in local authority formulae have reduced in real terms over time. This decline was particularly large after the National Funding Formula was introduced in 2018, which set deprivation funding at a lower level than the level that was previously used by local authorities. The deprivation funding factors in local authority funding formulae have come down over time to meet this lower value, particularly amongst local authorities that previously provided larger amounts. Some of this shift was a deliberate decision to focus more funding for disadvantage on low prior attainment. This will have spread disadvantage funding more widely. However, it will only have partially compensated the most deprived schools for reductions in deprivation funding over time.
3.3 Differences across local areas
We now examine the differences in spending per pupil across local authorities. Given the way the school funding system operates, these differences are predominantly driven by the operation of the National Funding Formula and other grants set by the Department for Education. They include the effects of extra funding targeted at deprivation and at low prior educational attainment and for schools located in sparsely populated areas. However, levels and changes over time will also partially reflect factors that seek to smooth and dampen changes over time, such as the funding floor and the minimum funding guarantee.
The only exception is the relative level of funding provided to secondary and primary schools, which does differ across local authorities, though this variation is reducing as part of the expected transition to a direct school-level National Funding Formula.
With this in mind, Figure 3.12 maps the level of primary and secondary school spending per pupil across local authorities relative to the national average. Local authorities in the London area receive higher levels of funding per pupil to compensate for having to pay higher salaries. In order to concentrate on differences by levels of need (as opposed to mechanical differences to afford higher salaries), we undo the effects of the area cost adjustment for Figure 3.13 later.
The areas with the highest levels of spending per pupil are located in inner London, particularly Westminster, Lambeth, Southwark, Haringey, Tower Hamlets, Islington, Camden and Hackney. In these areas, spending per pupil is close to 20% or more above the national average, even before application of the area cost adjustment. This reflects the very high levels of deprivation in inner London (even though these levels have declined over time).
We also see relatively high levels of spending per pupil (10–20% above the national average) in other relatively deprived areas of London, such as Lewisham and Hammersmith & Fulham), and for relatively deprived areas outside of London such as Liverpool, Nottingham, Manchester and Blackpool, as well as secondary schools in Salford and Middlesbrough.
There are then a larger number of local authorities with spending per pupil about 5–10% above the national average. These include many urban, deprived areas such as outer London, Birmingham, many areas of Greater Manchester and some parts of the North East.
Figure 3.12. Spending per pupil across local authorities in 2021–22, relative to national average and before applying the area cost adjustment
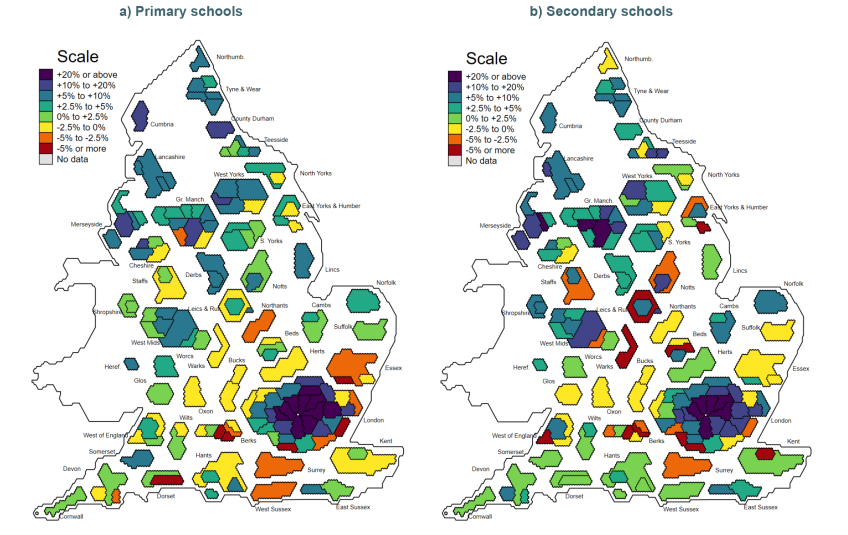
Note and source: Methods and data. Office for National Statistics, Counties and Unitary Authorities 2019 Boundaries. Map design is based on non-contiguous hexagon-based cartograms of the UK (House of Commons Library, 2022).
Figure 3.13. Local authority average school spending per pupil by FSM decile in 2021–22 and 2010–11 (before adjusting for area costs)
a) Primary schools

b) Secondary schools

Note and source: See Methods and data. HM Treasury, GDP deflators, November 2023.
Most local authorities see spending per pupil close to the national average, i.e. within 5% of the national average. These include, as one might expect, many areas with low or middling levels of deprivation, such as Hertfordshire, Hampshire, Oxfordshire and Devon. However, they also include many local authorities with relatively high levels of deprivation, such as Stoke-on-Trent, Wolverhampton, Newcastle, Hull and Sheffield. In these areas, levels of deprivation place local authorities in the most deprived 20% or 10% of areas, yet spending per pupil is close to the national average (i.e. within about 5%). Unfortunately, the reason for this is not entirely clear.
The areas with the lowest spending per pupil (consistently below the national average) are predominantly less deprived counties in the South East or South West of England, such as Surrey, Berkshire, Buckinghamshire, Leicestershire, Warwickshire, Northamptonshire, many parts of Essex, and more affluent local authorities in South London.
Figure 3.13 demonstrates the extent to which spending per pupil is targeted at more deprived areas, and how this has changed over time. In particular, it shows the average level of spending per pupil across areas by decile of eligibility for FSM across local authorities in 2010–11 and 2021–22, with the percentages showing the level relative to that in the least deprived decile.
As should be familiar now, the picture is much more positive for primary schools, with most areas seeing real-terms growth in primary school spending per pupil. This reflects the fact that primary schools are likely to have benefited more from the transfers of funding and responsibilities from local authorities to individual schools, as well as the reductions in the secondary:primary funding ratio over time. In contrast, the vast majority of areas have seen real-terms falls in secondary school spending per pupil.
Spending per pupil is clearly higher in more deprived areas. For primary schools, spending per pupil in 2021–22 is about 13–15% higher amongst the two most deprived deciles as compared with the least deprived areas. This is down from 18% higher for the most deprived decile in 2010–11, but is largely unchanged at 13% for the second most deprived decile. The overall picture is a flatter profile of primary school spending per pupil across areas by level of deprivation.
We see a similar picture for secondary schools. Secondary school spending per pupil has fallen by more in the most deprived areas. This has reduced the degree to which spending per pupil is targeted at more deprived areas, from 25% extra for the most deprived decile in 2010–11 to 19% in 2021–22, and from 17% to 13% for the second most deprived decile.
This flattening of the profile of spending per pupil across areas by deprivation will have been driven by the reduced levels of funding for deprivation we documented in Section 3.2. The slightly smaller reductions for the second most deprived decile are likely to reflect schools in London becoming less deprived over time, but still seeing higher levels of spending per pupil due to smoothing mechanisms in the funding system.
3.4 Summary and future challenges
Recent increases in school funding have delivered a return to real-terms growth in school spending per pupil between 2019 and 2022. However, the spike in inflation has put school budgets under increasing pressure. Increases in teacher and other support staff pay have driven up school costs, as have increases in energy and food prices. Whilst we see real-terms increases in school spending per pupil judged against standard measures of inflation used to analyse public spending, the purchasing power of school budgets is barely increasing at all when we consider the specific costs facing schools.
The government made major changes to the school funding system through the introduction of the National Funding Formula in 2018. It has also placed a high emphasis on the role of schools in ‘levelling up’ poorer areas of the country. However, we see that the most deprived schools have seen the biggest cuts to school spending per pupil since 2010, even after we account for the changing geography of deprivation. This appears to have been driven by a range of factors. First, the Pupil Premium has not kept pace with overall inflation over time. Second, the introduction of statutory minimum funding levels in 2020 disproportionately benefited less deprived schools. Third, deprivation funding factors in local authority funding formulae have reduced in real terms over time, reflecting the lower level of funding for deprivation in the National Funding Formula than in what came before. This reflects a deliberate government decision to focus more funding for disadvantage on low prior attainment. This will have spread disadvantage funding more widely. However, it will only have partially compensated the most deprived schools for reductions in deprivation funding over time.
Such trends are a major source of concern given evidence showing that educational inequalities have started to increase again in recent years, particularly since the COVID-19 pandemic, with pupils experiencing persistent levels of disadvantage seeing the worst trends (Education Policy Institute, 2023). Whilst the government has provided extra funding to schools as part of education catch-up plans, the amounts fall well below what was recommended by the Education Recovery Commissioner.8 Furthermore, such catch-up funding is only temporary, whilst the increases in educational inequalities look increasingly deep-seated. The government has provided extra resources for deprived areas through the creation of ‘Education Investment Areas’. However, the resources attached are relatively limited, such as salary incentives for a small number of teachers and improved wifi networks (Department for Education, 2023e).
Finally, school spending per pupil is actually more highly targeted at deprived areas (15–20% higher for the most deprived fifth of areas than for the least deprived) as compared with the early years and 16–19 funding systems (where it is about 9–12% higher). The school funding system also targets disadvantage in a more sophisticated way, with fixed amounts of extra funding for pupils eligible for free school meals, living in the most deprived areas and with low prior attainment. This contrasts with lower amounts of data on disadvantage for the early years and 16–19 funding systems, and a fixed share of funding for deprivation in the early years system (irrespective of actual trends in deprivation). The early years and 16–19 funding systems would do well to emulate some of the design features of the school funding system.
4. Further education and skills
Across all areas of education spending, further education and skills saw the largest spending cuts in the decade after 2010. This continues a long historical pattern where further education receives the smallest increases when overall spending rises and the largest cuts when governments are looking to reduce spending. The current government has sought to make technical education a priority and provided additional funding in the 2019 and 2020 spending rounds and the 2021 Spending Review. However, this has not been enough to reverse the real-terms cuts experienced by providers after 2010.
This chapter begins with a discussion of spending on 16–18 education, which covers 16- to 18-year-olds studying academic and technical qualifications in school sixth forms, sixth-form colleges and further education colleges. This illustrates that spending per student is currently increasing faster than previously planned, which largely results from lower growth in student numbers than expected, with more 18-year-olds dropping out. Continuing with the theme of this report, we then examine how spending per student varies across the country and the extent to which these patterns are geared towards levelling up poorer areas. We illustrate that differences in spending per student are mostly determined by the relative availability of colleges and school sixth forms across different areas. Finally, we discuss trends and plans for spending on adult education and apprenticeships.
4.1 16–18 education
Colleges and sixth forms are currently facing three main challenges. First, like all education providers, they face rising costs, both in terms of staff salaries and non-staff costs. Second, student numbers are rising as a result of a population boom moving through the education system. However, an apparent drop-off in participation rates (particularly amongst 18-year-olds) is leading to smaller increases than previously expected, which is creating uncertainty in the short term. Third, the government is pressing ahead with an overhaul of the post-16 qualification landscape. In the short run, this includes the removal of funding from Level 3 qualifications that cover the same areas as the government’s new ‘T levels’. In the longer run, the government has set out plans for yet another major reform of post-16 qualifications, with academic and technical qualifications combined into a new ‘Advanced British Standard’ (despite the fact that education is devolved).
Spending per student over time
Figure 4.1 shows spending per student aged 16–18 in school sixth forms, further education (FE) colleges and sixth-form colleges in each academic year from 2013–14 onwards (the earliest year covered by the allocations data). In this graph and the remaining analysis in this section, we consider funding allocated per student aged 16–18, as opposed to actual amounts of spending on individual students, which could be higher or lower depending on how schools and colleges spend money on different stages of education.
Figure 4.1. Spending per student in further education colleges (16–18), sixth-form colleges and school sixth forms

Note and source: See Methods and data. HM Treasury, GDP deflators, November 2023.
In each year, spending per student aged 16–18 is noticeably higher in FE colleges. In the 2023–24 academic year, FE colleges are projected to spend roughly £7,100 per pupil, compared with £5,800 in school sixth forms and £5,400 in sixth-form colleges. This is because students in FE colleges are more likely to study vocational qualifications and are more likely to come from deprived backgrounds, both of which attract higher levels of funding.9
Real-terms cuts between 2013–14 and 2019–20 were similar across school sixth forms and sixth-form colleges, at 16–18%. The cuts for FE colleges were smaller, at 8% over the same period. This partly reflects the fact that FE colleges have a higher proportion of vocational qualifications, which have received more from new funding streams such as the Capacity and Delivery Fund (CDF). Additionally, there has been a decline in part-time study in FE colleges. The proportion of part-time 16- to 18-year-old students in FE colleges decreased from 17% in 2013 to 10% by the end of the decade, which has led to an increase in funding per student.
In the 2019 and 2020 spending rounds, the government allocated an additional £700 million in funding for colleges and sixth forms up to 2021–22, and then a further £1.6 billion up to 2024–25 in the 2021 Spending Review. This makes for a total of £2.3 billion in additional funding by 2024–25 relative to 2019–20 (all in cash terms). In the current academic year (2023–24), spending per pupil is set to have risen by 5% in FE colleges, 3% in sixth-form colleges and 6% in school sixth forms relative to 2019–20 in real terms. In the case of FE colleges, this takes spending per student back to about 2015/2016 levels, but spending per student in school sixth forms and sixth-form colleges remains well below these levels.
Figure 4.2. Spending per student in 16–18 colleges and sixth forms

Note and source: See Methods and data. HM Treasury, GDP deflators, November 2023.
This is further illustrated by Figure 4.2, which shows how per-student spending levels in school sixth forms and colleges have evolved between 1989–90 (2002–03 for school sixth forms) and the present day, and how the additional funding will change spending levels up until 2024–25. For data reasons, we combine FE and sixth-form colleges, which we refer to as 16–18 colleges, and track spending by financial instead of academic year.
Since 2010–11 (when public spending cuts began to take effect), there has been a decline in per-student spending across all types of institutions. Between 2010–11 and 2019–20, spending per student fell by 14% in colleges and 28% in school sixth forms. For colleges, this left spending per student at around its level in 2004–05, while spending per student in sixth forms was lower than at any point since at least 2002.
Overall, per-student spending in 16–18 education is set to rise by 3.5% in real terms between 2021–22 and 2024–25. Yet even with the additional funding set out in recent spending reviews, college spending, which includes spending on both sixth-form colleges and FE colleges, will still be around 10% lower per student in 2024–25 than in 2010–11, while school sixth-form spending per sixth-form student will be 23% below 2010–11 levels. Therefore, the additional funding for sixth forms and colleges will only partially reverse the cuts of the previous decade. By 2024–25, current forecasts imply that about a quarter of the cuts for colleges between 2010–11 and 2019–20 will have been reversed, and even less for school sixth forms.
Uncertainty on costs and student numbers
In common with the rest of the education sector, colleges and sixth forms are facing rising costs for inputs such as staff and energy. The number of 16- to 18-year-olds is also expected to rise rapidly, with projections from the Office for National Statistics (ONS) implying a 14%, or more than 250,000, rise in the number of 16- to 18-year-olds between 2019 and 2024. In reality, student numbers have not risen by as much as this. Uncertainty on costs and on student numbers are also interacting in quite important ways.
On staffing costs, college staff have seen significant real-terms pay cuts since 2010. The recommended pay of college teachers declined by 18% in real terms between 2010–11 and 2022–23 (Sibieta and Tahir, 2023), based on trends in CPIH inflation.10 Over the same period, teacher pay scales fell by between 5% and 13%. There have been especially sharp declines in recent years due to high levels of inflation. A large part of the reason for these real-terms salary falls is the squeeze on college budgets over the last decade, which has limited the ability to offer higher pay rises. The net result is that college teacher pay was, on average, about £7,000 or 21% lower than school teacher pay in 2022–23. This is likely to be connected to the higher share of college teachers that leave their job in each year (16%) as compared with school teachers (10%).
For 2023–24, the Association of Colleges (AoC) has recommended pay rises of 6.5% for college staff.11 This is the highest recommended pay rise for college staff for at least 15 years, and is in line with recommendations for school teachers this year. Schools received additional funding of £900 million over a full year to help fund the additional costs of the 6.5% pay award. At the same time (July 2023), the government announced an ‘additional’ £185 million in 2023–24 and £285 million in 2024–25 to help colleges afford a similar pay rise.12 This was implemented by increasing 16–19 funding rates for the 2023–24 academic year more than had been expected. This included a 4.6% increase in the main baseline funding rates, a 30% increase in the uplift provided by each of the programme cost weightings for higher-cost subjects, as well as some specific increases for particular subjects,13 and an extra £20 million in funding for disadvantage.14 Since then, in October, the Prime Minister has also announced a further £150 million per year to increase funding for pupils retaking English and maths in 16–19 education and apprenticeships (Department for Education, 2023b). This is part of ambitions for a new ‘Advanced British Standard’ (see below for further discussion).
In reality, this extra funding is being recycled from within the additional £1.6 billion announced at the time of the 2021 Spending Review. Actual student numbers have turned out to be lower than expected at the time of the Spending Review, which has allowed the government to increase funding rates by more than it expected. In this sense, the money announced in July and October 2023 was not, strictly speaking, additional and it is already included within our analysis of spending per student above.
Considering overall costs and funding for colleges in 2023–24, staff pay is expected to rise by 6.5% if colleges follow AoC recommendations. Initial evidence suggests that most colleges are implementing pay rises of 6.5–7.5%,15 and CPI inflation is expected to be about 6% for 2023–24. Cash-terms funding per student in FE colleges (calculated for Figure 4.1 above) is expected to grow by 6.4% in 2023–24. This would suggest cost rises are probably just about affordable for colleges, on average. Furthermore, our calculations for funding per student in 2023–24 make use of ONS projections showing a 3.0% rise in the number of 16- to 18-year-olds in 2023. The rise in the number of that age group in education may turn out to be lower than this, with the funding rise being spread over a smaller population.
To better understand the implications of the uncertainty on student numbers, Figure 4.3 shows the number of 16- to 18-year-olds in education over time (indexed to 2019) together with ONS projections for the total number of 16- to 18-year-olds. We also break down the figures in education into those aged 16–17 and those aged 18. We exclude 18-year-olds attending higher education (HE), in order to focus on the implications for colleges and sixth forms.
Figure 4.3. Trends and projections in numbers of 16- to 18-year-olds over time, relative to 2019–20

Source: Department for Education, Participation in education, training and employment age 16 to 18; Office for National Statistics, 2020-based interim national population projections.
According to ONS projections, the number of 16- to 18-year-olds is expected to grow by 14% between 2019 and 2024, or a steady average of about 3% per year. The actual number of 16- and 17-year-olds in education initially grew much faster than ONS projections in 2020, reflecting increased education participation during the COVID-19 pandemic and poor labour market options. Since then, the number of 16- to 18-year-olds in education has been largely flat. Whilst ONS projections imply 7.2% growth in the number of 16- to 18-year-olds between 2019 and 2022, actual numbers in education have grown by the lower amount of 5.5%. Interestingly, Figure 4.3 also shows that the number of 16- and 17-year-olds in education has continued to grow, by a total of 8.0% or 80,000 between 2019 and 2022. In contrast, the number of 18-year-olds in education (excluding HE) has fallen by 13% or 20,000 between 2019 and 2022, with most of the fall happening in 2022.
Figure 4.4 digs deeper into these trends by showing the shares of people aged 16–17 and of 18-year-olds in education or training, in employment, and who are classed as ‘NEET’ (not in education, employment or training) over time. To provide a complete a picture, this does include 18-year-olds in HE. The long-run trend is a rising share of young people in education and training between the late 1990s and mid 2010s, peaking around 2016 at about 95% for 16- and 17-year-olds and 73% for 18-year-olds. Since then, education and training participation has dropped off very slightly to about 93% for 16- and 17-year-olds in 2022. More dramatically, it has fallen to about 66% for 18-year-olds, the lowest level since 2010, with a drop of 4 percentage points since 2020 alone. This appears to have been made up for by a slight and gradual rise in the share of 18-year-olds in employment. It also reflects a sharp decline in the number of young people taking apprenticeships. Since peaking in 2015/2016, the number of apprentices under the age of 19 –predominantly 18-year-olds – has declined by 35%. More recently, there has been a dramatic rise in the number of 18-year-olds classed as NEET; 16% of 18-year-olds were NEET in 2022, near equal to the share last seen in the Great Recession of the late 2000s.
The lower-than-expected growth in the number of 16- to 18-year-olds in education is the main reason that the government could increase funding rates for 2023–24 by more than expected. If this lower growth in student numbers continues into next year, then spending per student will likely be higher than our projections in Figure 4.2. This is clearly a source of uncertainty, and the fact that participation in education and training is dropping amongst 18-year-olds is a concern in itself.
Figure 4.4. Education participation and labour market status of people aged 16–17 and of 18-year-olds

Source: Department for Education, Participation in education, training and employment age 16 to 18.
Qualifications reform
An additional challenge faced by the sector comes from an overhaul of the post-16 qualification landscape. There is a major ongoing reform of Level 3 qualifications, with funding being removed from technical qualifications that overlap with T levels.16 In March 2023, the government published the final list of qualifications that will have their funding withdrawn from August 2024, which amounts to 134 qualifications.17
The qualifications listed include many common BTEC and City & Guilds qualifications in subject areas that overlap with T levels. The removal of funding is estimated to affect around 40,000 enrolments by 16- to 19-year-olds, which equates to 2% of all enrolments at Level 3 and 6% of non-A-level enrolments at Level 3. These reforms are especially likely to affect the post-16 choices of poor households (eligible for free school meals), students with special educational needs, and low attainers who are not yet ready for T levels. It is vital that schools and colleges ensure that these students continue to have opportunities to access quality routes through post-16 education.
Reforms to further education qualifications are set to continue into the future, with the government recently announcing its intention to introduce the ‘Advanced British Standard’ (ABS). The proposed ABS would be a new baccalaureate-style qualification for 16- to 18-year-olds that would eventually replace A levels and T levels. Under the ABS, students would normally study at least five subjects and would spend significantly more time in the classroom, with a minimum of 1,475 hours of teaching over two years. Currently, a typical post-16 student receives up to 1,280 hours of tuition over two years of study.18 The government’s commitment that every student will study some form of maths and English up to the age of 18 will also be part of the ABS.
The ABS is a long-term policy goal, which the government has said will take a decade to fully implement. On the surface, the move to a broader post-16 curriculum with an increase in teaching time is a positive step. Indeed, England stands out from other countries in the narrowness of its post-16 education curriculum and providing students with the opportunity to drop maths after 16 (Robinson and Bunting, 2021). However, the advantage of this move must be balanced against the risk of adding further policy churn to the post-16 qualification landscape, especially given that T levels are still to be fully rolled out. Practically, the additional teaching under the ABS would also require higher levels of funding and the recruitment of additional further education teachers.
4.2 Differences across areas
Continuing the theme of this annual report, here we analyse differences in spending per student across areas, including the extent of extra funding for more deprived areas.
First, it is useful to briefly set out how funding is allocated for pupils aged 16–18 in FE colleges and sixth forms. In 2013, the government introduced a national funding formula for 16–19 education. Under this formula, each student is funded at a particular rate based on the costs and complexity of their programme of study. There is a national base rate for full-time students (£4,753 per student in 2023–24, with lower amounts for part-time students). Other factors in the formula then increase the funding for more costly programmes – such as engineering, manufacturing and agriculture – and for ‘high-value’ subjects, such as maths and many science, technology and engineering subjects. T levels receive additional funding given the courses involve more hours of teaching and require industrial placements. Disadvantaged students can also receive funding uplifts, such as if they live in deprived postcodes based on the Index of Multiple Deprivation (IMD) or if they failed to achieve a grade 4 or above in GCSE maths or English. There are also adjustments for course drop-out. Finally, there is an area cost adjustment based on the expected cost of employing staff across different areas. This is not the same area cost adjustment used for schools.
In line with this formula, we have already seen from Figure 4.1 that spending per student is highest in FE colleges, which is because they are more likely to cater for high-cost technical programmes and tend to serve more disadvantaged students.
Ideally, we would examine the full distribution across institutions with different levels of disadvantage, but there is no publicly available measure showing the share of disadvantaged students across colleges and sixth forms. We therefore focus on the distribution across areas.
With this in mind, Figure 4.5 shows the distribution of total education spending per student aged 16–18 across local authorities in England in 2023–24, combining all colleges and all sixth forms. This is shown relative to the national average and before application of the area cost adjustment, in order to abstract from differences in funding purely driven by differences in salary costs. It is based on the location of the college or grouping that students attend, so may reflect travel of students across local authorities (both in large cities and in more rural areas). Many colleges have merged or have campuses across multiple sites, with funding and student numbers only counted for the lead institution or head office. This can lead to high numbers of FE students and funding apparently located in the local authority of the lead institution, such as Camden and Stockton-on-Tees. One should therefore be cautious in interpreting the differences at the extremes or within local areas. The analysis is also slightly different from Figure 4.1 as we must use headcounts rather than full-time-equivalents.
Figure 4.5. 16–18 education spending per student across local authorities in 2023–24, relative to national average and before application of area cost adjustments

Note and source: See Methods and data. Office for National Statistics, Counties and Unitary Authorities 2019 Boundaries. Map design is based on non-contiguous hexagon-based cartograms of the UK (House of Commons Library, 2022).
Figure 4.5 shows that spending per student tends to be highest in most parts of the North West, Yorkshire and Humberside, and in most of the West Midlands. It tends to be lowest in London and the South of England (before application of the area cost adjustment). Interestingly, there are also some quite big apparent differences across localised areas. For example, there are stark local differences within Teesside, around Humberside and Lincolnshire, and in Cheshire, Tyneside and some parts of London. These local differences are likely to reflect the movement of students across local authority boundaries and the merger of many FE colleges. For example, City and Islington College is now part of the Capital City College Group based in Camden, and Redcar and Cleveland College is now part of the Education and Training Collective based in Stockton.
Figure 4.6 explores the factors driving this distribution by plotting spending per student against the share of students at FE colleges in each area. This makes clear that the share of pupils in FE colleges is a very important driver of spending per student across local areas, with spending per student much higher in areas with greater prevalence of FE colleges. This helps explain the overall pattern of higher spending per student in Northern regions of England (where FE colleges are more common), and mostly lower spending per student across London and the South of England (where sixth forms are more common). One should be cautious about interpreting the extremes in this graph as they may simply reflect the effects of college mergers and students crossing local authority boundaries (e.g. Islington, Middlesbrough and Stockport).
Figure 4.6. Comparing 16–18 education spending per student against the share of students in FE colleges across local authorities, 2023–24

Note and source: See Methods and data.
Figure 4.7. Spending per student in FE colleges and sixth forms across local authorities in 2023–24, relative to national average and before application of area cost adjustments

Note and source: See Methods and data. Areas with fewer than 100 students in each type of provision are excluded from the analysis and marked as ‘No data’.
Figure 4.7 shows spending per student in FE colleges and sixth forms (combining school sixth forms and sixth-form colleges) separately across local authorities relative to the national average (across all institution types). This shows that spending per student in FE colleges specifically is relatively similar across local authorities, being generally close to or well above the national average. Within school sixth forms and sixth-form colleges, spending per student is mostly well below the national average across local authorities. In both cases, there are a few unusual cases driven by the specific circumstances of areas where there are just one or two institutions of a given type. The relatively low variation within FE colleges and within sixth forms across areas once again highlights the important role played by the type of provision in shaping the distribution across areas.
Figure 4.8. Education spending per student aged 16–18 by IMD decile in 2023–24 and 2013–14 (before adjusting for area costs)

Note and source: See Methods and data. HM Treasury, GDP deflators, November 2023.
Finally, Figure 4.8 shows the level of total 16–18 education spending per student across deciles of local authorities based on their level of disadvantage as defined by the Index of Multiple Deprivation (IMD). This is shown for both 2023–24 and 2013–14.
In 2023–24, total spending per student in the most deprived decile was about £6,300 (before adding area cost adjustments), which is about 9% above spending levels in the bottom decile. This higher level of spending in the most deprived decile will partly reflect disadvantage funding in the funding formula (some of which is specifically targeted at IMD). It will also be shaped by the greater share of students attending FE colleges in the most deprived decile (55%) as compared with the least deprived decile (44%).
The distribution of spending per student has become more targeted at disadvantaged areas over time. In 2013–14, the differences across deciles were never more than 4–5%. By 2023–24, this had increased to 9% extra funding for the most deprived areas. This reflects small real-terms growth in spending per student in more deprived areas (about 2–3%) compared with small real-terms cuts in less deprived areas (about 2–3%). These growth rates are probably overstated as they relate to spending per head rather than per full-time-equivalent. However, they will also reflect decisions to focus more funding on measures of disadvantage, and funding changes that have tended to favour FE colleges in relative terms.
In summary, there is a wide distribution of education spending per student aged 16–18 across areas, with spending per student generally higher in Northern areas of England, particularly the North West, Yorkshire and Humber, and parts of the North East. These differences are highly shaped by differences in provision across areas, with spending per student generally higher in areas where more students attend FE colleges. This may reflect students travelling across local authority boundaries in order to attend FE colleges specifically. Such effects can also be observed across small local areas, such as Teesside and Cheshire. It also reflects the fact that the funding formula provides higher amounts for more costly technical programmes and also provides extra funding for disadvantaged students. The level of extra funding for more disadvantaged areas has gone up over time, from about 4–5% extra in 2013–14 to about 9% extra by 2023–24. This extra funding for disadvantaged areas is smaller than we see for schools, but similar to the early years. It is also noteworthy that it has gone up over time for 16–18 education, whereas it has declined for schools.
4.3 Adult education and skills
Few areas of public policy have experienced as much change as adult education and skills. Since the turn of the millennium, there have been a number of major reforms, creating a post-18 education system that is often difficult for individuals and employers to navigate. In recent years, this change has continued with the introduction of two new skills programmes targeted at adults (Multiply and Skills Bootcamps), changes to apprenticeship regulation, and the upcoming launch of the Lifelong Learning Entitlement. The backdrop to these policy changes is a funding landscape that has seen significant real-terms declines since the early 2000s, as well as major reallocations of public funding between different forms of adult education.
Public spending generally falls into three categories:
- classroom-based learning, including basic skills and qualifications at multiple levels;
- subsidies for work-based learning, such as apprenticeships;
- loans for further education courses, known as advanced learner loans.
In the remainder of this section, we set out how the public funding of adult education and skills has changed over time. We then consider each of the three areas of adult education in turn.
Adult education spending over time
Figure 4.9 shows public spending on adult education and apprenticeships since the early 2000s up until the present day, as well as the projected level of spending in 2024–25. We show the overall level of public funding and break this down into the three spending categories: classroom-based learning; work-based learning; and the amount lent through advanced learner loans in each year.
Total public spending on adult skills has decreased since the 2000s, with spending at around £4.4 billion in 2022–23 – a 30% drop from its peak of £6.3 billion in 2003–04 (adjusted for inflation). The trend is most pronounced in classroom-based learning, which has decreased by two-thirds since the early 2000s from £5.0 billion to £1.7 billion.
Figure 4.9. Public spending on adult education and skills (actual and projected for 2024–25)

Note and source: The figure for 2024–25 is a projected spending level based on spending plans announced in the 2021 Spending Review. See source for figure 6.4 in Drayton et al. (2022). Amount lent through advanced learner loans from Student Loans Company. HM Treasury, GDP deflators, November 2023.
During the 2000s, part of the decline in classroom-based funding was diverted to work-based learning, so overall spending remained fairly stable. The introduction of Train to Gain pushed expenditure on work-based learning to a peak of £2.8 billion in 2009–10. Since the early 2010s, funding for work-based learning has consistently been around £2 billion in today’s prices, while classroom-based funding has continued to decline. Advanced learner loans were introduced in 2013–14, but they have consistently represented a small share of skills spending. Around £130 million was lent through advanced learner loans in 2022–23, which is 3% of the overall skills budget.
The government allocated an additional £900 million in day-to-day funding for adult education in 2024–25 relative to 2019–20 in the 2021 Spending Review (Drayton et al., 2022). As a result, total spending on adult skills is set to increase by 14% in real terms between 2019–20 and 2024–25. Part of the additional spending has already been realised: total spending on adult education increased by almost 7% in real terms between 2019–20 and 2022–23. As with spending on 16–18 education, planned increases in spending only reverse a fraction of past cuts: total skills spending in 2024–25 will still be 23% below 2009–10 levels. Spending on classroom-based adult education has fallen especially sharply, and will still be over 40% below 2009–10 levels even with the additional funding.
Public funding for classroom-based learning
The largest cuts to public spending have been to funding for classroom-based learning. There are two key drivers behind its long-term decline. The first is a decline in the number of adults taking classroom-based FE courses. Figure 4.10 shows the number of publicly funded classroom-based qualifications taken at different levels in England. In 2004–05, adults enrolled in nearly 5.5 million government-funded FE qualifications. By 2020–21, that number had dropped to 1.5 million, which marks a 72% decline relative to the peak. There has been a decline in qualifications taken at every level, but there was a particularly dramatic decline in the number of learners studying at the lowest levels (below Level 2) during the 2000s.
This decline means that colleges and other education providers receive less funding, because funding is allocated on the basis of the number of courses provided. The decline in participation in classroom-based learning has resulted from the withdrawal of public funding for low-level qualifications in the 2000s, a large and deliberate shift from classroom-based to apprenticeship training, and the introduction of tighter eligibility criteria for funding entitlements in the 2010s.
The merit of this decline in participation depends in part on the returns to these qualifications. There is a high degree of variation in the value of different FE qualifications for learners. Yet evidence shows that many low-level classroom-based courses offer comparatively low returns in the labour market (Tahir, 2023). When considering future changes to public funding, the variation in returns to qualifications means that any funding needs to be well targeted: it matters how the money is spent, as well as how much is spent.
The second driver of the decline in public funding is the large real-terms reduction in funding rates for classroom-based courses. These funding rates determine how much education providers receive per course taught; since 2013–14, funding rates for many courses have not changed in cash terms (Sibieta, Tahir and Waltmann, 2021).
Figure 4.10. Participation in classroom-based further education qualifications by adults (19+) in England

Note: Level 2 corresponds to GCSE or equivalent. Skills for Life encompasses everyday literacy and numeracy courses. Level 3 corresponds to A-level or equivalent qualifications. Level 4+ corresponds to higher-level qualifications such as Higher National Certificates (HNCs) or Higher National Diplomas (HNDs).
Source: Learner numbers from 2002–03 to 2018–19 from figure 2.2 in Sibieta, Tahir and Waltmann (2021). Learner numbers for 2019–20, 2020–21 and 2021–22 calculated from Department for Education apprenticeship statistics and adult further education participation statistics.
Since 2013–14, the Skills Funding Agency (now the Education and Skills Funding Agency) has set funding levels using the following formula:
Funding received for teaching a learner
= Funding rate × Disadvantage uplift × Area cost uplift
Figure 4.11. Programme funding rates for selected classroom-based courses

Source: Programme funding rates obtained from Education and Skills Funding Agency’s Adult Education Budget (AEB): funding rates and formula. HM Treasury, GDP deflators, November 2023.
The level of funding received depends on the funding rate – which in turn depends on the type of qualification(s) taken by the learner (the number of taught hours and subject area) – a disadvantage uplift which is based on local area deprivation measures, and an area cost uplift to reflect higher salary costs in certain areas.
The key component in determining funding levels is the funding rate. This has been fixed in cash terms for many programmes since 2013–14. Figure 4.11 illustrates how funding rates for a selection of classroom-based courses have changed in real terms over the past decade. The government increased the funding rate for GCSE English and maths in 2015–16, but since then providers have received a fixed fee of £811 for teaching this course. The funding rates for ‘functional skills’ courses have not changed in cash terms in the last decade. This means that, in real terms, education providers are receiving 22% less than they did in 2015–16 for teaching an adult learner a GCSE in English or maths, while the funding rates for ‘functional skills’ courses have fallen by 24% in real terms in the last ten years.
The government announced in March 2023 that it will apply a 2.2% increase to the final earnings for all AEB formula-funded provision in the 2022–23 and 2023–24 academic years.19 However, the cash-terms freeze in programme funding rates over the past decade is unlikely to represent good policy. Funding rates have been eroded in an unpredictable and arbitrary way, and over time become detached from the resource needs of education providers. Ultimately, this is important because it determines the quality of education received by learners.
Public funding for apprenticeships
Employers receive public subsidies to cover the cost of apprenticeship training. Since 2017, these subsidies have been nominally funded through the apprenticeship levy. Under the levy, large employers with a total pay bill in excess of £3 million pay 0.5% of their pay bill above that level as an apprenticeship levy. This is transferred into a digital account and topped up by 10% of public funding, which can be used to pay for the costs of apprenticeship training. There is also a generous system of public funding for non-levy-paying firms, who only have to pay 5% of the costs of apprenticeship training.
Despite appearances, the apprenticeship levy is not a hypothecated tax, where the revenue collected goes directly into a separate fund dedicated solely to apprenticeships. Instead, the Treasury sets an Apprenticeship Budget in England at each spending review. While the system has demand-led elements, the government has control mechanisms such as anticipated revenue calculations and caps on funding bands for apprenticeships. The devolved governments of Scotland, Wales and Northern Ireland receive a corresponding amount via the Barnett formula.
Figure 4.12. Funds raised by, allocated and spent from the apprenticeship levy
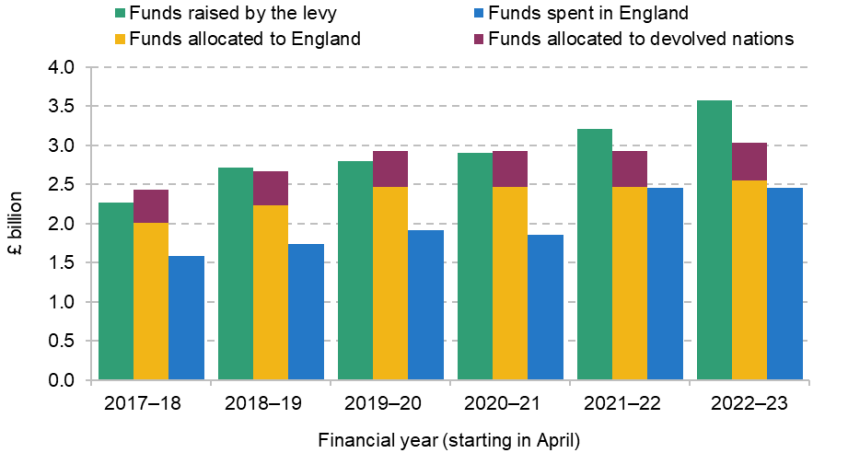
Source: Figure 9.9 in Tahir (2023).
The level of allocated funding can be, and has been, different from the amount of money raised through the apprenticeship levy. Figure 4.12 shows the revenue generated by the apprenticeship levy, the funds allocated to England’s Apprenticeship Budget and the amounts allocated to the devolved nations, as well as the actual expenditure from England’s Apprenticeship Budget.
The nominal amounts raised by the levy have grown over time, particularly in the last two years, driven by increases in companies’ pay bills due to wage inflation. In the early years of the levy, the amount allocated exceeded the amount raised. However, this has been reversed in the last two years, with almost £290 million more raised than allocated in 2021–22, rising to £550 million in the most recent year. Since the apprenticeship levy was introduced in 2017, it has raised £580 million more than has been allocated across the UK.
It is also important to differentiate between the funds allocated in England (through the Apprenticeship Budget) and actual expenditure. The former represents the government’s allocated budget for apprenticeship training, while the latter reflects the real uptake and utilisation by employers. In the first four years of the levy, 75–80% of the Apprenticeship Budget in England was spent each year. The gap has narrowed in recent years, with 96% of the budget being spent in the last financial year.
Policy reforms, such as the introduction of the apprenticeship levy, affect the incentives and capacity of employers to provide apprenticeships, and therefore the number of people taking them. There are four levels of apprenticeships in England:
- intermediate apprenticeships – equivalent to National Qualifications Framework (NQF) Level 2 (itself equivalent to five A*–C grades at GCSE);
- advanced apprenticeships – equivalent to NQF Level 3 or two A–E grades at A level;
- higher apprenticeships – equivalent to at least a Level 4 qualification (such as an HNC);
- degree-level apprenticeships – equivalent to an undergraduate degree.
Figure 4.13 shows how apprenticeship participation in England at each level has changed over time, with higher and degree-level apprenticeships aggregated together.
In the early 2000s, the total number of adult apprentices hovered around 200,000. There was a gradual increase in apprentice numbers from 2007–08 and then a sharp acceleration towards the end of the decade. The total number of apprentices in England more than doubled in two years between 2009–10 and 2011–12 from 300,000 to just over 600,000. This was almost entirely driven by individuals enrolled in the disbanded Train to Gain programme being migrated onto apprenticeships (Belfield, Farquharson and Sibieta, 2018). Between 2012–13 and 2016–17, there were consistently around 700,000 apprentices each year.
Figure 4.13. Participation in apprenticeships by adults (19+) in England

Source: Apprenticeship numbers from 2002–03 to 2018–19 are from figure 2.2 in Sibieta, Tahir and Waltmann (2021). Apprenticeship numbers for 2019–20, 2020–21 and 2021–22 are calculated from Department for Education apprenticeship statistics.
Since the introduction of the apprenticeship levy in 2017, the number of apprentices has declined. This cannot be solely attributed to the apprenticeship levy as other regulatory changes coincided with the introduction of the levy.20 However, between 2016–17 and 2021–22, the total number of apprentices fell by 16%. The overall fall in apprentices has largely been driven by a fall in intermediate apprenticeships; the number of higher or degree apprenticeships has tripled since 2016–17.
In summary, the government currently provides generous subsidies to employers to cover the cost of apprenticeship training, funded through the apprenticeship levy. Yet the amount raised through the levy exceeds the amount allocated to funding work-placed training. Since the introduction of the levy, there has also been an overall decline in the number of apprenticeships, which has mainly been driven by a fall in intermediate apprenticeships. The overall impact of this change in apprenticeship composition is unclear. The increase in the number of adults taking higher-level apprenticeships could be a positive trend. However, the reduction in intermediate apprentices may represent a decline in the opportunities for low-skilled adults.
Further education loans
The government currently provides access to loans for further education courses through advanced learner loans (ALLs). These represent a tiny fraction of public outlay on student loans: in 2022–23, the amount lent through ALLs (£124 million) was less than 1% of the amount lent through HE loans (£19.9 billion). However, the system of further education loans is set to be reformed through the introduction of the new Lifelong Learning Entitlement (LLE).
From 2025, the LLE is scheduled to replace the two existing systems of publicly funded student loans – HE student finance and ALLs. The LLE will provide individuals with financial support for four years of post-18 education up to the age of 60, which is the equivalent of £37,000 in current fees. This loan support can be used to finance short courses, modules or full courses at Levels 4 to 6.
The LLE is best thought of as a package of three reforms to the existing post-18 loan system. First, it will unify the two existing post-18 loans systems, with learners studying FE courses being offered maintenance loans like their counterparts studying at university. Second, the LLE will introduce ‘modular funding’, which will allow learners to access loans for specific modules and short courses rather than just entire courses. Third, the LLE will remove existing restrictions on accessing loan funding known as ‘equivalent and lower qualification’ rules.21
Taken together, these reforms should enhance the support available to FE learners and make the existing student loans system more flexible. However, there are a number of important design details still to be confirmed. One of the main areas of uncertainty is which courses will be eligible for the LLE. The government has announced that the LLE will be available for all courses currently funded through HE student finance, but qualifications currently funded through ALLs will only be eligible if there is ‘clear learner demand and employer endorsement’ (Department for Education, 2023d). This decision is still being consulted on, but it is critical to the LLE’s impact on the FE sector. The government is also yet to publish a full analysis of the likely impact of the LLE.
The continued uncertainty around the LLE is creating problems for the education sector, and could potentially cause institutions to hesitate in developing or adapting programmes in alignment with the LLE. Given that the LLE is due to be rolled out in the near future, it is essential that the government provides clarity as soon as possible.
4.4 Summary and future challenges
The government has placed a high emphasis on the role of further education and skills in improving productivity and ‘levelling up’ poorer areas of the country. This has been partly reflected in extra funding announced at recent spending reviews, as well as ongoing and planned reforms, such as T levels and the new Lifelong Learning Entitlement. However, further education and skills saw the largest cuts in the decade after 2010, which have only been partially reversed. There are also familiar challenges relating to low funding, uncertainty and policy churn.
Recent funding increases have provided a boost to college and sixth form funding for young people. But only about a quarter of the cuts to college funding per student are due to be reversed by 2024, and even less for sixth forms. Indeed, funding changes over the last decade have tended to favour FE colleges relative to sixth forms. As a result, the distribution of funding per student across areas is heavily shaped by the share of students in FE colleges. This, as well as extra funding for disadvantage, has slightly increased the targeting of 16–18 education funding towards disadvantaged areas over time, though this remains well below the targeting we see in school funding.
There also remain significant sources of uncertainty. Slower-than-expected growth in student numbers has allowed for higher-than-planned increases in funding rates and larger salary rises for college staff. However, the root causes are likely to be lower levels of education participation, with greater levels of apparent drop-out amongst 18-year-olds. This is a potential cause of concern in itself. The government has also announced yet another planned reform to post-16 educational qualifications, with plans for an ‘Advanced British Standard’. This has been announced before T levels have been fully rolled out and whilst funding is being gradually withdrawn from existing Level 3 qualifications.
Adult skills spending saw even larger cuts over the 2010s, particularly classroom-based adult education spending, which is set to be over 40% below 2009 levels by 2024. This decline in spending has been driven both by a fall in the number of learners and by a long-term freeze in funding rates. However, any measures to increase the number of learners must be weighed against the low returns from some classroom-based courses.
The government has highlighted the potential benefits from more young people and adults doing apprenticeships, and there were large increases in spending and numbers between 2010 and 2015. However, overall numbers have declined since the introduction of the apprenticeship levy in 2017, with a greater focus on higher and degree-level programmes. The fall in intermediate apprenticeships might represent a decline in the opportunities for low-skilled adults. There are ongoing arguments about broadening the use of the apprenticeship levy, which is discussed in greater detail in Tahir (2023).
Lastly, the Lifelong Learning Entitlement is supposed to unify the separate loan systems for FE and HE courses and is intended to make the loans system more flexible. However, progress in implementing the LLE has been slow, and there remain important questions about the design of the system, such as which courses will be covered.
5. Higher education
This year, the up-front cost of higher education per student has continued on a steady downward trajectory. For the 2023–24 university entry cohort, we estimate £9,600 is available in up-front total teaching resources per student per year in today’s prices. This is slightly more than was available to those starting in 2011–12 (£9,400), but considerably less than the peak in 2012–13 (£11,800) after the student loan reforms injected additional funding into the system, as shown in Figure 6.1.
This downward trend is largely a result of the cash freeze in the cap on tuition fees that universities have been able to charge to home students. This cap was set at £9,000 in 2012–13, increased to £9,250 in 2017–18 and will remain frozen at that level for at least the next academic year (2024–25). Inflation has been much higher than expected since the government confirmed the latest three-year freeze to the cap. Based on the latest forecasts for the GDP deflator – the standard measure of inflation for assessing real-terms changes in public spending – the real value of the cap will have fallen by £1,370 (13%) between 2021–22 and 2024–25. This is twice as large as the cut of 6.5% the government might have expected based on forecast inflation when it set the policy.
The other main source of teaching resources for universities is grants from government (through the Office for Students, OfS).22 These have increased in recent years, from £900 million in 2021–22 to £973 million in 2022–23 and £1,038 million in 2023–24. However, high inflation means these cash-terms rises of 8.1% and 6.7% respectively are only relatively small real-terms increases, and are dwarfed by the real-terms erosion of tuition fees which account for a much larger share of total teaching resources.
While there has been a real-terms fall in resources for home students, international student fees are not subject to the same cap and are typically much higher. The number of international students has increased substantially in recent years. In the year ending September 2023, 451,000 visas were issued to higher education students, 8% more than in the previous year (419,000) and twice as many as the 222,000 in 2019, the last pre-pandemic year (Home Office, 2023). In the 2021–22 financial year, tuition fees from non-UK students accounted for 42% of higher education course fees and 21% of all income for universities in England, and these percentages are likely to have increased further since.
While increasing international recruitment and fees has allowed many universities to cross-subsidise the teaching of home students, the extent to which they do this varies widely across the sector. For instance, non-UK students accounted for only 3% of higher education course fees at Edge Hill University in 2021–22, but for more than three-quarters at several London universities.23 As the Office for Students (2023) highlighted in May, over-reliance on income from overseas students’ fees now means a fall in international recruitment would present a material risk to the financial sustainability of some providers.
Another apparent risk to university finances, from university pension schemes, seems to have abated. In March 2020, a valuation of the largest scheme (the Universities Superannuation Scheme) suggested it had a substantial deficit. Since then, the scheme’s funding position has improved significantly, largely due to changing economic conditions. The latest monitoring report ahead of the publication of the 2023 valuation suggests the scheme now has a substantial surplus (USS, 2023).
In the remainder of this chapter, we provide an update on how the student finance system is coping in the current period of high inflation, and consider how policy choices have interacted with higher-than-expected inflation to reshape the system. Then, continuing with the theme of this report, we focus on higher education spending across different parts of England.
5.1 Student loans in times of high inflation
As well as eroding the real value of tuition fees, persistent high inflation continues to reshape the student finance and student loan system in England. In this section, we discuss the impact on the maintenance support students are entitled to, the interest rates applied to student loans, and the repayment threshold above which graduates make loan repayments.
Maintenance support
Of most immediate concern to current students is the flawed way in which maintenance loan entitlements – the amounts students can borrow each year towards their living costs – have been increased each year. As we first highlighted in February last year (Waltmann, 2022c), the method for uprating entitlements in line with a forecast for inflation (specifically RPIX) means that the generosity of maintenance loans in practice depends on forecast errors. For the last few years, inflation has turned out much higher than forecast, leading to substantial real-terms cuts to the amount students can borrow.
As shown in Figure 5.1, maintenance entitlements in the last three years have been increased by 3.1%, 2.3% and 2.8%, respectively. These increases have been far outpaced by rises in consumer prices, as measured by CPI, of 6.2%, 10.2% and a further 4.6% this year. As a result, the real value of support for every student has fallen by 11.4% since 2020–21. For students from the poorest families, this cut meant they were entitled to £1,288 less in real terms this academic year than in 2020–21.
Figure 5.1. Changes in maintenance entitlements, and consumer price inflation, each academic year

Note: Increase in consumer prices is based on the first quarter (Q1) falling in each academic year. Change in maintenance entitlement in 2024–25 assumes rise in line with the Office for Budget Responsibility’s November 2023 forecast for RPIX in 2025Q1. Average National Minimum Wage (NMW) applying to a 22-year-old during the academic year; including the National Living Wage applying from April 2024 onwards.
Source: Bolton, 2023; Low Pay Commission, 2023; Office for Budget Responsibility, 2023; authors’ calculations.
While higher-than-expected inflation may have surprised the government, it has chosen each year to again increase entitlements by the forecast for RPIX, rather than providing a larger increase to correct for forecast errors made in previous years. This has effectively made the cuts in generosity permanent. In contrast, the Welsh and Scottish governments increased support for the poorest students this academic year by 9.4% and 11.1% respectively, making up for real-terms cuts resulting from below-inflation increases the previous year.
At the same time, the earnings that students would otherwise make if they instead took a job at the applicable National Minimum Wage (for 22-year-olds) have been rising rapidly – by 10.4% last academic year and 11.7% this year, as the National Living Wage will be increased and extended to those aged 21 and 22 from April 2024. This may help some students who are able to work part-time alongside their studies. However, a declining standard of living amongst students, and a widening of the gap between the support students are entitled to while studying and what they could otherwise earn from working the same number of hours, may induce some to forgo university altogether.
The generosity of maintenance support has also been eroded in another important way. The amount students are entitled to depends on their household (typically their parents’) income, but the parental earnings thresholds that determine entitlements have been frozen in cash terms since 2008. As a result, students from families with the same real income are entitled to less support each year. Figure 5.2 shows the support a student living away from home, outside London would be entitled to this academic year – £9,978 for those with household income below £25,000 and £4,651 for those with household incomes above around £63,000, with support tapered in between. The yellow line shows what support the same students would have been entitled to if the maintenance loan system was as generous as it was when it was first introduced in this form in 2016–17.
Figure 5.2. Maintenance entitlements by household income in 2023–24, and if there had been no cuts to generosity since 2016–17

Note: For students living away from home, and attending universities outside London. ‘No cuts since 2016–17’ shows entitlements if 2016–17 levels had been increased by latest OBR forecasts of CPI between 2016 and 2023 calendar years, and if parental earnings thresholds had been increased in line with average earnings growth over the same period.
Source: Bolton, 2023; Office for Budget Responsibility, 2023; authors’ calculations.
Those with the lowest incomes, who are still entitled to the maximum support this year, are entitled to £672 less than in 2016–17 as a result of increases in maintenance support not keeping up with inflation. Similarly, those who would have been entitled to the minimum support even in 2016–17 (who have household incomes above £81,000 this year) are entitled to £312 less.
But the freeze to the parental earnings thresholds means those in between have faced much larger cuts. A student with a household income of £62,000 would be entitled to £4,700 this academic year, but would have received £7,149 in real terms in 2016–17 – 52% more. This implies a substantial increase in the contribution that government expects some parents to make towards students’ living costs, if they are not to have a much lower standard of living than earlier cohorts. We estimate that if government had instead maintained the generosity of entitlements at 2016–17 levels, initial outlay on loans for the 2023 entry cohort would have been £1.3 billion higher, at a long-run cost to the government of £0.3 billion per cohort.
Interest rates
High inflation also affects the interest that is added to student loan balances. Those who took loans out between 2012 and 2022 face an interest rate of between RPI and RPI + 3%, depending on their earnings after graduation.24 Importantly, by law, the interest rate applied is not allowed to rise above interest rates ‘prevailing on the market’, specifically the average interest rate on unsecured commercial loans. Because of this cap (and last-minute changes to its application, for which we successfully advocated (Waltmann, 2022b)), the maximum interest rate did not rise to 12% in September 2022, or to 16.5% this September (as it would have based on RPI figures of 9% and 13.5% in March 2022 and 2023 respectively). Instead, as shown in Figure 5.3, rates have risen gradually, with all Plan 2 borrowers currently facing an interest rate of 7.3%.
Based on the latest OBR forecasts, we expect the prevailing market rate cap to continue to bind for all graduates until next September, when the minimum interest rate will fall to 6.4% (the forecast for RPI in 2024 Q1). Despite the cap, the maximum interest rate will continue to rise, peaking at 9.4% in August 2025.
This is a result of the lagged way the interest rate is set. The rate applying for a year from each September is based on RPI the previous March. This protected borrowers from rises in interest rates from September 2021 to August 2022, even as RPI rose rapidly (shown by the grey line on Figure 5.3). But this lag also means interest rates will take longer to fall as inflation comes back down. Under current policy, a maximum interest rate of more than 9% would be applied to student loans in Summer 2025, at a point when the OBR forecasts RPI will be running at just above 2%. This is likely to be politically difficult for the government.
Figure 5.3. Minimum and maximum interest rates charged on student loans since 2012–13

Note: Dashed lines are forecasts. Forecast interest rates applying from September reflect the forecast for RPI in the year to the previous Q1. The prevailing market rate cap is assumed to be applied quarterly, with the OBR forecast for the prevailing market rate in 2023 Q3 assumed to apply from December 2023.
Source: DfE guidance, 2023; ONS RPI All Items; Office for Budget Responsibility, 2023; authors’ calculations.
Large swings in interest rates also create arbitrary redistribution between borrowers. Those whose loan balances have been falling over recent years will have benefited from the lagged adjustment of interest rates, as they will have been charged a lower interest rate when their loan balance was high, and a higher rate when their loan balance was lower. In contrast, those whose loan balances are rising over time will lose out, as interest rates will be high when their loan balances are low and low when their loan balances are high. This will apply particularly to those who entered university in 2022, who will not have benefited from the interest rate being below RPI in 2021–22, but will have seen the interest rate on their loan climb steadily while studying.
Loan repayments
Of course, unlike with a mortgage-style loan, the interest rate applied to student loan balances does not directly affect the amount graduates are required to repay in any given month (although it does affect how many years some will make repayments for). Instead, graduates repay 9% of their earnings above a specific earnings threshold.
In 2022, the government announced that the repayment threshold would be frozen at £27,295 until 2024–25 – its level in the 2021–22 fiscal year – instead of rising with average earnings. From 2025–26, the threshold will then rise in line with the RPI. As shown in Figure 5.4, the earnings threshold in the last year of the freeze will be £4,508 lower than it would have been under the previous policy, meaning all graduates earning above £31,803 will repay £406 more towards their student loans in 2024–25 (as well as a similar amount more in every subsequent year in which they make repayments).
As a comparison, a full-time employee earning £35,000 a year will be paying £249 a year more in direct tax (income tax and NICs) in 2027–28 as a result of all the changes to tax policy since 2021 (Adam et al., 2023) – and particularly multi-year freezes to tax thresholds, which will gradually bring more and more people into higher tax brackets.
For those who started university this academic year, the repayment threshold was set at £25,000 and will remain frozen until 2026–27, after which it will also rise in line with the RPI. By the last year of that freeze, when some three-year undergraduates will be starting to make repayments, the threshold will be £9,250 (27%) lower than it would have been under the pre-reform policy, increasing annual repayments by up to £833. As shown by the grey dotted line, this is an even bigger decrease in the nominal threshold than the government expected when it set the policy (£7,285).
Figure 5.4. Nominal student loan repayment thresholds

Note: Dashed lines show expected paths based on forecasts from the October 2021 EFO, the latest official forecasts when the policy change was announced in January 2022. Solid lines reflect most recent forecasts from November 2023 EFO.
Source: Office for Budget Responsibility, 2021 and 2023; authors’ calculations.
5.2 Differences across local areas
Most funding for early years, schools and further education can be thought of as being for the provision of local public services, which benefit local residents. Many people go further afield for higher education, travelling to universities outside of their local area or moving away from home to study. This makes it more complicated to think about which areas benefit from higher education spending – the area students come from, or the area in which they study.
Also unlike for other stages of education, per-student funding for higher education teaching does not vary across the country in line with local costs of delivery. An English-domiciled full-time undergraduate student is subject to the same tuition fee cap of £9,250 (and is eligible for the same tuition fee loan from the government) wherever in the UK they choose to study. They also attract the same Office for Students teaching grant to their university, which is based on the subject they study, with higher funding for subjects that are more expensive to deliver (such as medicine, dentistry and science).
The maintenance loan a student is entitled to does vary with their location, with those living away from home and those attending a university in London entitled to a larger loan, in recognition of their higher living costs. As discussed above, students with low household incomes (typically parental incomes) are also entitled to larger loans, and this will vary between areas.
First, we estimate the higher education spending on people who come from each local area. We use data on tuition and maintenance loans issued to students at each university, and data on the grants each university receives from the Office for Students, to estimate the total up-front higher education spending on English-domiciled students attending each UK university. The Higher Education Statistics Agency (HESA) also publishes data on where in England students at each university were living before they started their course. We estimate total higher education spending on students from each part of England by assigning each student the average per-student spending at the university they attended.
Published HESA data allow us to estimate funding for 89 areas, which broadly follow local authority boundaries but which group together authorities in London and six metropolitan county areas. Total higher education spending in each of these areas is not in itself particularly meaningful. In 2021–22, it ranged from £4.8 billion in Greater London (with a population of nearly 9 million) to £13 million in Rutland, which has a population of less than 50,000. How we think of the relevant population group for this spending makes a big difference to patterns in per-person funding across England.
Figure 5.5. Student funding by domicile of student
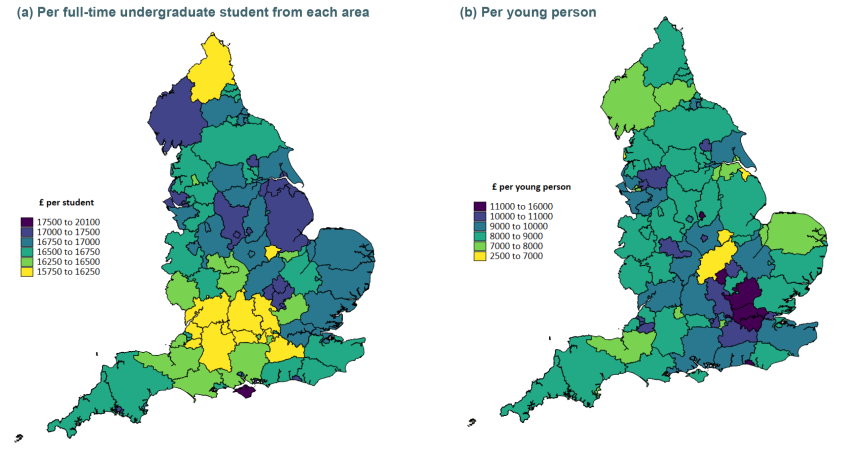
Note: Academic year 2021–22. Follows geography on which HESA publishes student domicile, largely by upper-tier local authority, except for Greater Manchester, London, Merseyside, South Yorkshire, Tyne & Wear, West Midlands and West Yorkshire. Each student attending the same university, and within a given category, is allocated the average per-student spending on that category of student at the university they attended; categories are full-time undergraduate, part-time undergraduate and postgraduate.
Source: Office for Students teaching and other grants from Higher Education Statistics Agency (2023b). Tuition and maintenance loans and grants by institution from Student Loans Company (2022). Student numbers by institution and domicile from Higher Education Statistics Agency (2023c). Resident population in each local authority in mid 2021 from Office for National Statistics (2022).
Funding per full-time undergraduate student averaged £16,700 in England in 2021–22. This was made up of loans for tuition fees (£9,250 per year for undergraduates who take them up), maintenance loans, and around £1,000 in grants from the Office for Students. Our estimates vary relatively little across the country, and are between £16,000 and £17,500 in 85 out of 89 areas. This will underestimate true differences between areas as we do not observe spending on individuals, but assign them averages for their university. As shown in Figure 5.5a, spending per student is lowest in some of the most affluent areas of the country (West Berkshire, Wokingham and Buckinghamshire). This suggests students from these areas disproportionately attend universities where fewer students are eligible for the maximum maintenance loan, or where take-up of loans is lower.
As an alternative, we estimate funding per young person. More specifically, we divide spending in each area by the number of residents aged 15–17, to capture the population of young people who could potentially attend higher education from each place (and account for the fact that most undergraduate courses are three years in length). As shown in Figure 5.5b, this measure is highest in Greater London (£15,800), followed by parts of the South East, the West Midlands and Greater Manchester. It is lowest in Northamptonshire (£5,800) and Blackpool (£6,250). This measure is largely capturing differences in higher education participation rates between areas.
Indeed, higher education participation rates have typically been highest in London and the South East and other relatively affluent areas, and lowest in more deprived places, where educational attainment is also typically lower. Estimated participation rates in each lower-tier local authority area based on POLAR4 – a measure of the proportion of young people who enter higher education aged 18 or 19 years old – are shown in Figure 5.6. This measure is based on students who began their studies between 2009–10 and 2013–14, so relates to an earlier period than the funding numbers, but still shows similar geographic patterns to Figure 5.5b.
An alternative approach would be to consider higher education spending as benefiting not the areas students are drawn from, but the areas in which universities are located. We estimate the higher education spending attracted by students at each provider and also the total spending attracted by providers in each area. For this to capture something about the wider economic impacts of higher education spending on an area, we must assume that a majority of teaching is delivered in the same area as the provider and also that students spend a majority of their maintenance loan in that area. This is less plausible where there is significant distance learning (we exclude the Open University) or teaching provided at faraway campuses, and it is also possible that students commute to university from other areas. We focus on spending in each travel-to-work area (TTWA) to minimise these concerns. These areas are drawn based on commuting patterns and so capture a more meaningful economic geography than local authority administrative boundaries. We focus on spending per head of the population.
Figure 5.6. Quintiles of share of young people entering higher education

Note: POLAR4 measure of young participation in higher education, calculated at Middle Layer Super Output Area level. Aggregated to lower-tier local authority.
Source: Authors’ calculations using Office for Students (2020).
As Figure 5.7 shows, higher education spending on this measure is highest by far in Canterbury (£2,300), followed by Bath (£1,380) and Brighton (£1,280). These are university towns, with a relatively high number of students per head of the population, so that their local economies are likely to be substantially affected by their universities. Around a third of the TTWAs in England (52 out of 149) do not contain any higher education provider, and so do not benefit directly from any higher education spending. As shown in Figure 5.8a, some areas do not contain a university (shown as dots on the map) but do receive some higher education spending as they contain another type of higher education provider.
As well as funding that supports students with living costs or funds their teaching, universities also receive funding for research. Public sector funding for research is worth around a third as much in total across English TTWAs (£117 per capita) as funding associated with students. It comes from a mixture of grants and contracts from public bodies such as research councils, UK government departments and the EU. As shown in Figure 5.8, only three areas receive more public funding for research than they do funding associated with English-domiciled students: Oxford, Cambridge and Bedford.25 The vast majority of this funding is received by a small number of research-intensive universities, notably the University of Oxford (£592 million), University of Cambridge (£549 million) and University College London (£487 million). As shown in Figure 5.8b, this research funding is even more concentrated in specific areas. Research funding per capita is highest in Oxford (£1,054) and Cambridge (£762), followed by Lancaster & Morecambe (£578).
These numbers show that higher education funding is very unequally distributed across the country, both in terms of where students are from and in terms of where they study. By area of origin, funding is skewed towards richer areas and London, as these areas have much higher shares of young people attending university. By area where money is spent, the places that benefit are those where universities are located, which again in most cases are wealthier places.
Figure 5.7. Research and student funding in 2021–22 by TTWA in England, £ per capita

Source: See Figure 5.8.
Figure 5.8. Funding by TTWA of higher education provider, per capita

Note: Academic year 2021–22. By travel-to-work area, based on commuting patterns in Census 2011. Left-hand figure is for England only and excludes cross-border TTWAs. Funding allocated based on registered location of the higher education provider (rather than specific location of campus). Excludes Open University. Per-capita figures based on resident population (all ages).
Source: Student funding (as in Figure 5.5) reflects tuition and maintenance loans for England-domiciled students from Student Loans Company (2022) and income from Office for Students grants from Higher Education Statistics Agency (2023b). Research funding includes funding body grants from Research England and capital grants recognised in the year; research contracts and grants from public bodies (including research councils, UK and EU governments); and income from other services rendered to UK public bodies, from Higher Education Statistics Agency (2023c). Resident population in each TTWA in England in mid 2020 from Office for National Statistics (2020).
A few areas benefit disproportionately from higher education spending, including Canterbury, Brighton, Bath, Oxford and Cambridge. The benefits for these places are likely far greater than the raw spending numbers would suggest. Students not only spend their maintenance loans but, in many cases, also money that they receive from their parents.
International students also pay tuition fees and spend in the local area, but are not counted in higher education spending statistics. Official statistics suggest the value of tuition fees paid by international students and their additional expenditure in the UK was just over £22 billion in 2022. This is more than government’s total outlay on student loans and, given large differences between providers in the scale of international recruitment, is likely to disproportionately affect some areas (particularly London). As well as benefits from additional spending, large increases in student numbers may also create challenges for some local areas, particularly where housing supply or funding for local public services is slow to adjust, or where international students are accompanied by family members on dependants’ visas.
Our estimates of research funding only include public funding, but government spending on research grants likely has a significant multiplier effect, attracting further private funding and innovation. Going forward, the government will need to trade off the benefits of concentrating research and innovation in small geographical areas against the cost of favouring a few already-wealthy areas. A large academic literature has shown that clusters of innovation can be extremely successful due to their ‘network externalities’, with Silicon Valley being just one famous example. The key objective for the government will be to preserve those positive externalities while making sure that other areas of the country are not left behind.
5.3 Summary
The student finance system in England has been reshaped by cash-terms freezes in recent years, which have led to a decline in resources for teaching home students and higher loan repayments from graduates. Higher-than-expected inflation means the freeze in the tuition fee cap has had more than twice the impact that government might have expected when it was announced. This does not seem a sensible way to set policy.
Maintenance support entitlements have been uprated each year in line with forecasts for inflation. The intention may have been to maintain the real-terms value of support provided over time, but this policy has failed to do so in recent years, as inflation has repeatedly exceeded forecasts. The government should reflect gaps between forecast and actual inflation when uprating the following period, to avoid the generosity of the system being determined in an arbitrary way by forecast errors.
Another major ongoing issue for students is the freeze to the parental earnings thresholds which govern eligibility for maintenance support and which bite even more given high nominal wage growth. Some students are now entitled to only two-thirds of thesupport that they would have been entitled to in 2016–17, when the current maintenance system was put in place. The parental earnings thresholds should be increased each year in line with average earnings by default.
Turning to the benefits of higher education spending, these accrue disproportionately to people from more advantaged areas, where higher education participation is highest. The wider economic benefits of public spending on higher education are skewed towards university towns, and particularly the even smaller number of areas with research-intensive universities which receive significant public research funding.
6. Comparisons
In this chapter, we compare the level of spending per pupil across the different stages of education. Figure 6.1 compares the trends in public spending per student on various stages of education over time in England, whilst Figure 6.2 shows the levels relative to primary school spending per pupil. For the early years, schools and further education colleges, we base these on the figures presented in Chapters 2–4, with projections up to 2024–25. For higher education, we focus on total up-front public resources provided for teaching. This is effectively tuition fees (minus any fee discounts) plus teaching grants. Whilst this includes up-front funding that will eventually be repaid via graduate contributions later in life, we feel this gives a better measure of the public resources available for teaching.
Figure 6.1. Spending per pupil or student per year at different stages of education (2023–24 prices)

Note and source: Early years figures are spending per part-time-equivalent child for 3- and 4-year-olds taking up a place. Secondary school spending per pupil includes spending on school sixth forms. Further education figures represent spending per student aged 16–18 in further education and sixth-form colleges. Higher education figures are cohort-based numbers divided by 3 – an approximate course length in years. HM Treasury, GDP deflators, November 2023.
Figure 6.2. Relative spending per pupil or student per year at different stages of education (primary school spending per pupil = 1)

Note and source: See Figure 6.1.
The shape of public spending on education has changed significantly since the early 1990s. In 1990–91, there was a very clear gradient across education stages: the older the pupils being taught, the higher the level of public spending (or resources) per pupil per year. Although this broadly remains true in 2022–23, the relative differences are much, much smaller.
At the start of the period in 1990–91, higher education spending was £10,000 per student per year (this and all figures here are in 2023–24 prices), about four times the level of primary school spending per pupil, and it all came directly from government spending. Further education spending was about £6,000 per student and 2.4 times the level of primary school spending (and 1.4 times the level of secondary school spending) per pupil. Secondary school spending was £4,100 per pupil, about 1.6–1.7 times the level of primary school spending per pupil (£2,500). Early years spending was very low (less than £100 million in total, with no centralised national programmes for early education) and is not shown on these graphs as a result.
Over the next 30 years, there were then significant changes in this balance of spending, with three distinct phases of change: falls in spending (1990–91 to 1997–98); rapid growth (1997–98 to 2010–11); and differential protections from spending cuts (2010–11 onwards).
In the period of falling spending during the 1990s, higher education spending per student fell by 25% in real terms and further education spending per student aged 16–18 fell by 17% in real terms between 1990–91 and 1997–98. These cuts largely reflected total spending not keeping pace with rapid rises in student numbers. Secondary school spending per pupil fell by 2% over the same period, whilst primary school spending per pupil rose by about 11% in real terms. These trends significantly narrowed the differences in spending per student between schools and further and higher education.
Spending per student then rose significantly across all stages of education between 1997–98 and 2010–11, though at different rates and for different reasons. The early years entitlement was introduced in the late 1990s and represented about £1,800 per child in 2001–02, rising to about £2,600 in 2010–11 or 45% of the spending per pupil in primary schools. Turning to schools, we see that spending per pupil rose by about 6% per year in real terms in primary schools, and by about 5% per year in secondary schools. This led primary school spending per pupil to rise from £2,800 in 1997–98 to £5,800 in 2010–11, and secondary school spending to rise from £4,000 to £7,500 per pupil. This narrowed the ratio between secondary and primary school spending per student from 1.5 in 1997–98 to 1.3 in 2010–11.
Further education spending per student also rose, but at the slower rate of about 4% per year in real terms. This narrowed the difference between further education and school spending per student, with further education spending per student only about 40% greater than primary school spending per pupil and very similar to secondary school spending per pupil by 2010.
Following the big decline during the 1990s, higher education spending per student increased by about 32% in total between 1997–98 and 2010–11, or about 2% per year, on average, in real terms. These increases largely reflected the introduction of tuition fees in 1998 and their increase to £3,000 in 2006. By 2006–07, spending per student in higher education was back above its level in 1990. However, cash-terms freezes in fees up to 2010 led to real-terms declines in spending per student, taking it back to below 1990 levels again. This meant that higher education spending per student was only 70% greater than primary school spending per student in 2010, having been about 2.7 times higher in 1997 and nearly 4 times in 1990.
Since 2010, most areas of education spending have seen real-terms cuts in some form or another. Early years has been the main exception, with spending per child about 72% higher in real terms in 2022–23 than in 2010–11. This mainly reflects extensions to the free entitlement, particularly the extension from 15 to 30 hours for working parents in 2017, and the boosts to hourly funding in 2017 and in more recent years. Hourly funding has grown more slowly, by about 15% in real terms between 2010–11 and 2022–23. Rapid growth in early years providers’ costs will leave core funding per hour 12% lower in 2024–25 than in 2012–13.
As we saw in Chapter 4, total school spending per student fell by 9% in real terms between 2010–11 and 2019–20. This was felt differently by individual primary and secondary schools, partly because of a transfer of funding and responsibilities from local authorities giving an artificial boost to individual schools’ budgets. Primary school spending per student actually rose by 7% in real terms between 2010–11 and 2019–20, reflecting the transfer of responsibilities and funding. Secondary schools saw a worse picture, with a 7% real-terms cut over the same period. This worse picture for secondary schools largely reflects the 28% drop in school sixth-form funding per student over the same period. The cuts to school spending per pupil are now being reversed and spending per pupil will largely be back to at least 2010 levels by 2024. However, the ratio between secondary and primary school spending per pupil is set to be much lower, at a difference of 10%.
Further education spending per student aged 16–18 fell by 14% in real terms between 2010–11 and 2019–20, the largest cut across all areas of education spending for young people. This is also now being partially reversed, but further education spending per student will still be about 10% lower in real terms in 2024–25 than in 2010–11.
The 2012 reforms to higher education led to a significant boost in spending per student of about 25% in real terms. This pushed spending per student up to nearly £12,000, well above its level of £10,000 in 1990. However, in a repeat of recent history, there have been real-terms falls in spending per student as fees have been frozen in cash terms across most years. In 2022–23, spending per student was around £1,900 or 16% lower in real terms than for 2012–13 entrants, largely because the cap on tuition fees is now 24% lower in real terms than it was in 2012–13. Notably, more than two-thirds of the decline is due to real-terms cuts over the past four years. Even with some additional public funding for teaching next year, we project higher education spending per student will fall by a further 3% in real terms between 2022–23 and 2024–25. This would take spending per student back to levels last seen in 2011–12, just before the increase in tuition fees to £9,000, and about 3% lower than its level more than 30 years ago in 1990.
This differential pattern of cuts has further narrowed differences in education spending per student by age. In 2022–23, early years spending per pupil represented about 70% of the value of primary school spending per pupil, having been a tiny element of public funding in the early 1990s. Secondary school spending per student will be about 10% greater than primary school spending in 2024–25, having been about 66% greater in 1990. Further education spending per student aged 16–18 in 2024–25 is set to be about the same as secondary school spending per student and only 11% greater than in primary schools, having been more than 2 times greater in the early 1990s. Higher education spending per student is still higher than across other stages, but is now back to levels last seen in the early 1990s and is due to be only around 50% greater than primary school spending per student, having been almost 4 times greater in the early 1990s.
7. Conclusion
In this year’s annual report, we have analysed trends in spending per student across different stages of education over time, with a particular focus on the effects of rising costs and the extent to which spending is targeted on disadvantaged areas. In what follows, we set out some of the key themes that have emerged from this analysis.
First, rising overall levels of inflation have eroded the real-terms value of government spending plans. In some cases, large salary increases mean costs are growing faster than headline measures of inflation. In the early years, core funding per hour for the free entitlement will be 12% lower in 2024 than in 2012, once providers’ rising costs are taken into account. For schools, the purchasing power of school budgets is set to be 4% lower than in 2010 when we account for costs facing schools. Higher-than-expected inflation has also reduced the real-terms value of maintenance loans for higher education students. By and large, the government is not planning to compensate education providers for the higher costs brought by inflation: in its Autumn Statement, for example, it chose to prioritise cutting personal and business taxes over increasing funding for public services.
Second, we see the pernicious effects of cash-terms freezes in key features of the education funding system. For example, cash-terms freezes in funding rates for further and adult education during the 2010s led to substantial real-terms declines in spending per student. In higher education, cash-terms freezes in tuition fees across most years is reducing spending per student down to 2011 levels. Cash-terms freezes in the student support system have reduced eligibility for maintenance support. In general, using cash-terms freezes as a default leads to unpredictable declines in the real-terms value of spending and support over time, with changes in individual years varying with inflation. A better default would be to uprate all relevant funding rates and thresholds with a sensible measure of inflation, such as CPI inflation or the GDP deflator.
Third, rising levels of the National Living Wage are increasingly creating pressures within the education system. It is directly increasing costs in the early years, where many staff are paid at or close to the National Living Wage. It is indirectly increasing costs in schools as local government employers seek to maintain pay differentials for support staff, and schools compete for staff with supermarkets and other employers. Next year (2024), the National Living Wage will rise by 10%, which will add to budgetary pressures in the early years and schools. Within further and higher education, the rate of education participation has fallen for 18-year-olds and higher education student numbers are below previous expectations. This may be because employment or on-the-job training is looking like an increasingly attractive financial option relative to staying in education, where maintenance support levels have fallen. There may be good reasons to increase minimum wages, but there are equally good reasons to make sure students feel able to continue in education.
Fourth, higher levels of education spending are explicitly targeted at children and young people from disadvantaged backgrounds. Figure 7.1 summarises the pattern across different stages of education by showing a measure of resources across 10 deciles of deprivation, relative to the level provided in the least deprived decile. We use two measures of deprivation to gain a fuller picture: the share of pupils eligible for free school meals (FSM) and the Index of Multiple Deprivation (IMD). Reflecting differences in organisation and data, the measure of resources differs slightly by stage of education (spending per pupil for schools and 16–18 education, core hourly funding for the early years) and covers slightly different years (2021–22 for schools, 2023–24 for the early years and 16–18 education). We therefore focus on broad patterns.
The figure shows that resources are about 15–21% higher in the most deprived decile (relative to the least deprived decile) in the early years and schools when we use eligibility for FSM as our measure of deprivation, and 13% higher in the second most deprived decile. Differences in resources by decile of FSM are much smaller for 16–18 education, with spending per student only 6% higher in the most deprived decile. The picture is slightly different when we look at IMD. Resources are still about 16–17% higher for the most deprived decile in the early years and secondary schools. However, this difference is only about 8% for primary schools and 9% for 16–18 education.
Some of these patterns are easy to explain. The early years and school funding systems explicitly use FSM eligibility to allocate funding, whilst IMD is used in the 16–19 education funding formula. We also know that funding for deprivation is lower in the 16–19 education funding formula. However, the differences between the pictures using IMD and FSM for the early years and primary schools raise obvious questions about whether FSM eligibility is fully capturing educational disadvantage. Governments across the UK should be reviewing whether FSM eligibility is the best indicator of disadvantage for allocating a high level of disadvantage funding, particularly in light of transitional protections under the transition to universal credit.
It is also important to look beyond the most deprived two deciles. There are very small differences between deciles 1 and 5 for FSM and between deciles 5 and 10 for IMD. In the case of FSM, this may reflect the impact of using a binary measure of disadvantage in areas with high inequality. In the case of IMD, it may create further potential concern as to whether resources really are targeted where they are most needed, which emphasises the importance of reviewing indicators used for allocating funding for deprivation.
Figure 7.1. Differences in resources across deciles of deprivation and stages of education (before application of area cost adjustments)
a) Deciles based on eligibility for free school meals
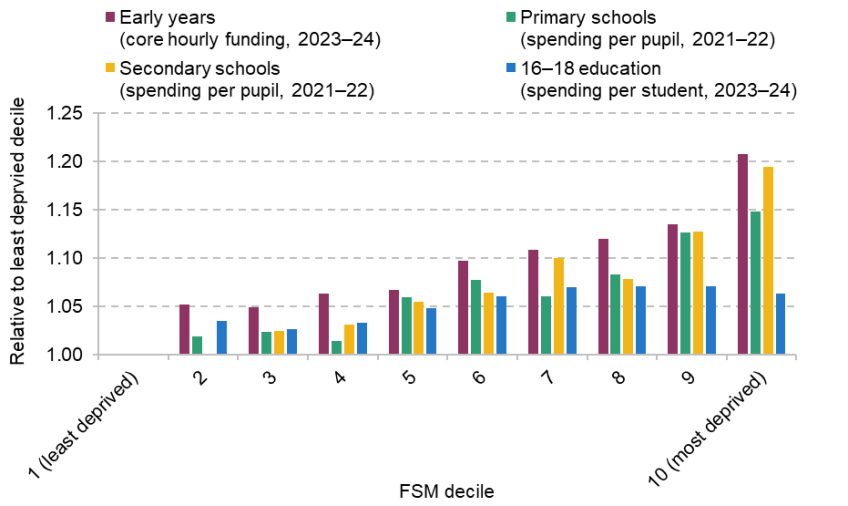
b) Deciles based on Index of Multiple Deprivation

Note and source: Figures for early years are drawn from Figure 2.6 together with eligibility for FSM in primary schools; figures for schools are drawn from Figures 3.12 and 3.13; figures for 16–18 education are drawn from Figures 4.5 and 4.8 together with eligibility for FSM in secondary schools.
We also know there have been big changes over time. Early years deprivation funding has become spread over a larger population of children eligible for FSM, and the targeting of school funding towards deprivation has reduced over time. In contrast, funding has become slightly more targeted over time in further education colleges and sixth forms, but still remains relatively low.
Despite these reductions, the government does deserve credit for the way in which additional funding is allocated across local authorities and individual education providers. The move to a national funding formula for both early years and schools has tightened the link between disadvantage and funding, and has brought education budgets in line with up-to-date measures of need. Broadly, the direction of travel here has been a good one, though the government could go further yet by adopting some of the sophisticated measures of disadvantage in the funding formula for schools (such as area-level deprivation and low prior attainment) in its funding for early years, and FE colleges and sixth forms.
The picture is more complicated in higher education, where there is a greater degree of choice around whether and where to participate. Students from less disadvantaged backgrounds are more likely to go to university and spending is not explicitly targeted at disadvantaged students. As a result, higher education spending per young person is clearly highest for better-off young people. This will only really change if there is progress in narrowing socio-economic inequalities in higher education participation.
Finally, the government has signalled a further tight set of public spending plans after 2024, such that budgetary pressures may continue into the rest of the decade. Set against this backdrop, the government’s ambitious plans for reform in the education system – with new childcare entitlements, a target for 90% of 11-year-olds to achieve the expected standards in reading, writing and maths, the introduction of the ‘Advanced British Standard’, the roll-out of T levels, and reforms to the funding and regulation of further and higher education – look like quite a big ask. Balancing the reforms and innovation that policymakers are asking of the system against the delivery of existing programmes in a tough funding landscape looks challenging indeed. All political parties will need to be clear-eyed and realistic about the education system’s capacity to implement major reforms against these headwinds.
References
Adam, S., Boileau, B., Delestre, I., Emmerson, C., Johnson, P., Joyce, R., Mikloš, M., Miller, H., Phillips, D., Ray-Chaudhuri, S., Stockton, I., Waters, T., Wernham, T. and Zaranko, B., 2023. Autumn Statement 2023 response. IFS Comment, https://ifs.org.uk/Autumn-Statement-2023-response.
Andrews, J., 2020. Analysis: school funding allocations 2021–22. Education Policy Institute, https://epi.org.uk/publications-and-research/school-funding-allocations-2021-22/.
Belfield, C., Farquharson, C. and Sibieta, L., 2018. 2018 annual report on education spending in England. IFS Report R150, https://ifs.org.uk/publications/2018-annual-report-education-spending-england.
Belfield, C. and Sibieta, L., 2016. Long-run trends in school spending in England. IFS Report R115, https://ifs.org.uk/publications/long-run-trends-school-spending-england.
Boileau, B., 2023. Public service spending: an even bigger squeeze. IFS presentation, 23 November, https://ifs.org.uk/sites/default/files/2023-11/Public-service-spending-an-even-bigger-squeeze-B-Boileau.pdf.
Bolton, P., 2023. The value of student maintenance support. House of Commons Library, Research Briefing 00916, https://commonslibrary.parliament.uk/research-briefings/sn00916/.
Britton, J., Farquharson, C., Sibieta, L., Tahir, I. and Waltmann, B., 2020. 2020 annual report on education spending in England. IFS Report R183, https://ifs.org.uk/publications/2020-annual-report-education-spending-england.
Cardim-Dias, J. and Sibieta, L., 2022. Inequalities in GCSE results across England and Wales. Education Policy Institute, https://epi.org.uk/publications-and-research/inequalities-in-gcse-results-across-england-and-wales/.
Cribb, J., Farquharson, C., McKendrick, A. and Waters, T., 2023. The policy menu for school lunches: options and trade-offs in expanding free school meals in England. IFS Report R253, https://ifs.org.uk/publications/policy-menu-school-lunches-options-and-trade-offs-expanding-free-school-meals-england.
Cunha, F., Heckman, J. J. and Schennach, S. M., 2010. Estimating the technology of cognitive and noncognitive skill formation. Econometrica, 78, 883–931, https://doi.org/10.3982/ECTA6551.
Department for Education, 2021. Review of post-16 qualifications at level 3 in England: policy statement. https://www.gov.uk/government/publications/reforms-to-post-16-qualifications-at-level-3-in-england.
Department for Education, 2022. The national funding formulae for schools and high needs: 2023–24. https://assets.publishing.service.gov.uk/media/62d679d98fa8f50c0a8a3ffc/2023-24_NFF_Policy_Document_.pdf.
Department for Education, 2023a. Early years supplementary grant 2023 to 2024: methodology. Guidance, https://www.gov.uk/government/publications/early-years-supplementary-grant-2023-to-2024/early-years-supplementary-grant-2023-to-2024-methodology.
Department for Education, 2023b. A world-class education system: the Advanced British Standard. https://www.gov.uk/government/publications/a-world-class-education-system-the-advanced-british-standard.
Department for Education, 2023c. 2023 to 2024 early years funding formulae: technical note. Guidance, https://www.gov.uk/government/publications/early-years-funding-2023-to-2024/2023-to-2024-early-years-funding-formulae-technical-note.
Department for Education, 2023d. Lifelong Learning Entitlement overview. https://www.gov.uk/government/publications/lifelong-learning-entitlement-lle-overview/lifelong-learning-entitlement-overview.
Department for Education, 2023e. Education investment areas. Guidance, https://www.gov.uk/government/publications/education-investment-areas/education-investment-areas.
Drayton E. and Farquharson, C., 2022. Early years spending update: the impact of inflation. IFS Report R229, https://ifs.org.uk/publications/early-years-spending-update-impact-inflation.
Drayton, E. and Farquharson, C., 2023. Early years spending update: Budget reforms and beyond. IFS Report R274, https://ifs.org.uk/publications/early-years-spending-update-budget-reforms-and-beyond.
Drayton, E., Farquharson, C., Joyce, R. and Waters, T., 2023. Childcare reforms create a new branch of the welfare state – but also huge risks to the market. IFS press release, https://ifs.org.uk/news/childcare-reforms-create-new-branch-welfare-state-also-huge-risks-market.
Drayton, E., Farquharson, C., Ogden, K., Sibieta, L., Tahir, I. and Waltmann, B., 2022. Annual report on education spending in England: 2022. IFS Report R234, https://ifs.org.uk/publications/annual-report-education-spending-england-2022.
Education and Skills Funding Agency, 2022. Early years funding: 2023 to 2024. Guidance, https://www.gov.uk/government/publications/early-years-funding-2023-to-2024.
Education Policy Institute. 2023. EPI Annual Report 2023. https://epi.org.uk/publications-and-research/annual-report-2023/.
Farquharson, C., 2023a. Why take-up of the two-year-old offer has really fallen. Nursery World, https://www.nurseryworld.co.uk/opinion/article/christine-farquharson-why-take-up-of-the-two-year-old-offer-has-really-fallen.
Farquharson, C., 2023b. Changes and challenges in childcare. IFS presentation, 16 March, https://ifs.org.uk/events/spring-budget-2023-ifs-analysis.
Gibbons, S., McNally, S. and Viarengo, M., 2018. Does additional spending help urban schools? An evaluation using boundary discontinuities. Journal of the European Economic Association, 16, 1618–68, https://doi.org/10.1093/jeea/jvx038.
Higher Education Statistics Agency, 2023a, Tuition fees and education contracts analysed by HE provider, domicile, mode, level, source and academic year 2016/17 to 2022/23. HE provider data: finance, DT031 table 6, https://www.hesa.ac.uk/data-and-analysis/finances/table-6.
Higher Education Statistics Agency, 2023b. Income analysed by source 2015/16 to 2021/22. HE provider data: finance, DT031 table 7, https://www.hesa.ac.uk/data-and-analysis/finances/table-7.
Higher Education Statistics Agency, 2023c. UK domiciled HE students by HE provider and domicile in academic year 2021/22. HE student data, DT051 table 59, https://www.hesa.ac.uk/data-and-analysis/students/table-59.
Home Office, 2023. Why do people come to the UK? To study. https://www.gov.uk/government/statistics/immigration-system-statistics-year-ending-september-2023/why-do-people-come-to-the-uk-to-study.
House of Commons Library, 2022. UK hex cartograms non-contiguous. https://github.com/houseofcommonslibrary/uk-hex-cartograms-noncontiguous.
Jackson, C. K., 2020. Does school spending matter? The new literature on an old question. In L. Tach, R. Dunifon and D. L. Miller (eds), Confronting Inequality: How Policies and Practices Shape Children’s Opportunities, American Psychological Association. https://doi.org/10.1037/0000187-008.
Jackson, C. K., Johnson, R. C. and Persico, C., 2016. The effects of school spending on educational and economic outcomes: evidence from school finance reforms. Quarterly Journal of Economics, 131, 157–218, https://doi.org/10.1093/qje/qjv036.
Johnson, R. C. and Jackson, C. K., 2019. Reducing inequality through dynamic complementarity: evidence from Head Start and public school spending. American Economic Journal: Economic Policy, 11, 310–49, https://doi.org/10.1257/pol.20180510.
Low Pay Commission, 2023. Minimum wage rates for 2024. https://www.gov.uk/government/publications/minimum-wage-rates-for-2024.
McLean, D., Worth, J. and Faulkner-Ellis, H., 2023. Teacher labour market in England: Annual Report 2023. National Foundation for Educational Research, https://www.nfer.ac.uk/publications/teacher-labour-market-in-england-annual-report-2023/.
Office for Budget Responsibility, 2021. Economic and fiscal outlook – October 2021. https://obr.uk/efo/economic-and-fiscal-outlook-october-2021/.
Office for Budget Responsibility, 2023. Economic and fiscal outlook – November 2023. https://obr.uk/efo/economic-and-fiscal-outlook-november-2023/.
Office for Health Improvement and Disparities, 2023. Public health profiles. https://fingertips.phe.org.uk/search/school%20readiness#page/4/gid/1/pat/15/par/E92000001/ati/6/are/E12000004/iid/90631/age/34/sex/4/cat/-1/ctp/-1/yrr/1/cid/4/tbm/1/page-options/tre-ao-1.
Office for National Statistics, 2020. Population estimates - small area based by single year of age, 2018-based. Accessed via NOMIS, https://www.nomisweb.co.uk/.
Office for National Statistics, 2022. Population estimates - local authority based by single year of age, Census 2021 based. Accessed via NOMIS, https://www.nomisweb.co.uk/.
Office for Students, 2020. Young participation by area. POLAR4 data, https://www.officeforstudents.org.uk/data-and-analysis/young-participation-by-area/about-polar-and-adult-he/.
Office for Students, 2023. Financial sustainability of higher education providers in England: 2023 update. https://www.officeforstudents.org.uk/publications/financial-sustainability-of-higher-education-providers-in-england-2023-update/.
Robinson, D. and Bunting, F., 2021. A narrowing path to success? 16–19 curriculum breadth and employment outcomes. Education Policy Institute, https://epi.org.uk/publications-and-research/a-narrowing-path-to-success-16-19-curriculum-breadth-and-employment-outcomes/.
Sibieta, L., 2023a. The decline in spending on school buildings. IFS Comment, https://ifs.org.uk/articles/decline-spending-school-buildings.
Sibieta, L., 2023b. How does school spending per pupil differ across the UK? IFS Report R256, https://ifs.org.uk/publications/how-does-school-spending-pupil-differ-across-uk.
Sibieta, L., 2023c. Tax, private school fees and state school spending. IFS Report R263, https://ifs.org.uk/publications/tax-private-school-fees-and-state-school-spending.
Sibieta, L. and Tahir, I., 2023. What has happened to college teacher pay in England? IFS Report R254, https://ifs.org.uk/publications/what-has-happened-college-teacher-pay-england.
Sibieta, L., Tahir, I. and Waltmann, B., 2021. Big changes ahead for adult education funding? Definitely maybe. IFS Report BN325, https://ifs.org.uk/publications/big-changes-ahead-adult-education-funding-definitely-maybe.
Student Loans Company, 2022. Student support for higher education in England 2022, https://www.gov.uk/government/statistics/student-support-for-higher-education-in-england-2022.
Tahir, I., 2023. Investment in training and skills. In C. Emmerson, P. Johnson and B. Zaranko (eds), The IFS Green Budget: October 2023. https://ifs.org.uk/publications/investment-training-and-skills.
USS, 2023. Monitoring of the FMP – September 2023. Available at https://www.uss.co.uk/about-us/valuation-and-funding/2023-valuation.
Waltmann, B., 2022a. Student loans reform is a leap into the unknown. IFS Report BN341, https://ifs.org.uk/publications/student-loans-reform-leap-unknown.
Waltmann, B., 2022b. High inflation set to cause interest rate rollercoaster for student loans. IFS Comment, https://ifs.org.uk/articles/high-inflation-set-cause-interest-rate-rollercoaster-student-loans.
Waltmann, B., 2022c. Government uses high inflation as cover for hitting students, graduates and universities. IFS Comment, https://ifs.org.uk/articles/government-uses-high-inflation-cover-hitting-students-graduates-and-universities.
White, H., Hoddinott, S., Pope, T., Gill, M., Wilkes, G., Urban, J. and Norris, E., 2023. Six key takeaways from the Conservative Party conference in Manchester. Institute for Government, https://www.instituteforgovernment.org.uk/comment/key-takeaways-conservative-party-conference-2023.
Zaranko, B., 2022. Spending on public services. IFS presentation, 18 November, https://ifs.org.uk/sites/default/files/2022-11/Spending-on-public-services-Ben-Zaranko.pdf.
Data
Department for Work and Pensions, NatCen Social Research. (2021). Family Resources Survey. [data series]. 4th Release. UK Data Service. SN: 200017, DOI: http://doi.org/10.5255/UKDA-Series-200017.
Office for National Statistics. Social Survey Division, Northern Ireland Statistics and Research Agency. Central Survey Unit. Quarterly Labour Force Survey. [data collection]. Retrieved from https://discover.ukdataservice.ac.uk/series/?sn=2000026.
Office of Population Censuses and Surveys. Social Survey Division. Labour Force Survey. [data collection]. UK Data Service. Retrieved from https://discover.ukdataservice.ac.uk/series/?sn=2000026.
University of Essex, Institute for Social and Economic Research. (2023). British Household Panel Survey . [data series]. 3rd Release. UK Data Service. SN: 200005, DOI: http://doi.org/10.5255/UKDA-Series-200005.
University of Essex, Institute for Social and Economic Research. (2023). Understanding Society. [data series]. 11th Release. UK Data Service. SN: 2000053, DOI: http://doi.org/10.5255/UKDA-Series-2000053.
Endnotes
Authors


Christine Farquharson
Christine's research examines inequalities in children's education and health, especially in the early education and childcare sector.

Kate Ogden
Kate joined the IFS in 2020 and works on local government finance and higher education.

Luke Sibieta
Luke is a Research Fellow at the IFS and his general research interests include education policy, political economy and poverty and inequality.

Imran Tahir
Imran joined the IFS in 2019 and works in the Education and Skills sector.

Ben Waltmann
Ben's main research areas are tax and social protection in developing countries, higher education, and dynamic discrete choice models.
More from IFS
Understand this issue


Policy analysis


Academic research