
Downloads
Death and taxes and pensions
PDF | 518.02 KB
The tax system treats funds that remain in a pension at death extremely favourably. Where an individual dies before age 75, funds remaining in their pension escape income tax entirely – there was income tax relief when the money was paid into the pension and no income tax when the money is taken out. Furthermore, any funds that remain in a pension at death (at any age) are not subject to inheritance tax. This results in the bizarre situation where pensions are treated more favourably by the tax system as a vehicle for bequests than they are as a retirement income vehicle. As such, there is a large incentive, for those who can, to use non-pension assets to fund their retirement while preserving their pensions for bequests.
This report sets out some options for a more coherent tax treatment of funds that remain in a pension at death. The reforms we propose, potentially with some transitional arrangements, would make the tax system fairer and more economically efficient. The revenue raised by moving to a more sensible system, even if relatively modest in the near term, could be substantial in the longer term. This revenue could be used to cut taxes elsewhere – including income tax and inheritance tax – or to ease the planned squeeze on public spending.
Key findings
1 Pensions are being increasingly used as a vehicle for bequests. Growth in defined contribution pensions along with the introduction of ‘pension freedoms’ would lead to more pension wealth being bequeathed at death even if people did not respond to the strong tax incentives to use pensions for bequests. Pensions and wealth-management professionals are fully aware of these tax benefits which, increasingly, are also being reported in the press. If nothing changes, more people will respond to the incentives the tax system creates.
2 Basic-rate income tax could straightforwardly be levied on all funds that remain in pensions at death. Alternatively, current income tax rules could extend to those inheriting pension pots from someone who dies before age 75. This would mean levying income tax when the person inheriting the pension pot withdraws the funds from it regardless of the age of death of the deceased. This could be combined with a minimum rate of income tax on withdrawals, set at the basic rate of income tax, in order to prevent funds withdrawn by non-income-tax-payers, in particular children, escaping income tax entirely.
3 Pension pots should be included in the value of estates at death for the purposes of inheritance tax. If we are to have an inheritance tax at all, it should apply evenly across all forms of wealth. Where the funds held in pension pots are to be subsequently subject to income tax – reducing their effective value – it would be appropriate for 80% of these funds to be counted for inheritance tax purpose.
4 Subjecting pensions to inheritance tax would raise revenue and remove the perverse incentive to avoid using a pension to fund retirement. Short-term revenue would be limited because few of those dying today are bequeathing pension pots. But if the generation benefiting from pension freedoms – those retiring after April 2015 – were to die with their full pension pots intact, we estimate that it would raise the equivalent of £1.9 billion a year (in today’s terms) in extra inheritance tax revenue. This increase would be substantial, representing an increase of around a quarter in the scope and yield of inheritance tax. The yield is very sensitive to the extent to which pensions will be run down before death: were half of current pensions intact at death, the yield would fall to £0.9 billion.
5 If the government did not want this change to increase the overall yield of inheritance tax, it could use the revenue to cut the inheritance tax rate and/or increase the threshold. To give a sense of scale, £1.9 billion would be roughly enough to reduce the rate from 40% to 30%, while £0.9 billion would be roughly enough to reduce the rate to 35%.
6 Reforms should be announced as swiftly as is practical. This would reduce the extent to which individuals will have saved in a pension in the incorrect expectation that they will be able to bequeath these funds under the current generous arrangements. As with any reform to wealth taxes, some retrospective taxation would be inevitable. If some transitional phasing of implementation were deemed appropriate, it would be straightforward for both the income tax and inheritance tax reforms we propose to be gradually introduced by date of death.
1. Introduction
‘[T]is impossible to be sure of any thing but Death and Taxes’ wrote Christopher Bullock in his 1716 play The Cobler of Preston. But while death and taxes might be certain, taxation at death is not – especially where pensions are concerned. Income tax is extremely generous to those who inherit pension wealth from someone who dies before the age of 75, while inheritance tax typically does not apply to any funds still remaining in a pension at death. Together, these two features mean that defined contribution private pensions – which give much greater scope than defined benefit pensions to be used as a vehicle for bequests – are a particularly tax-efficient vehicle for leaving money to children and other heirs.
This is rather odd. It means that pensions are actually treated more favourably by the tax system as an inheritance vehicle than they are as a retirement income vehicle. The tax system encourages those with sufficient means to use their non-pension assets rather than their pension to finance their retirement spending. As IFS researchers previously noted, ‘it is hard to understand why the government should subsidise saving for bequests via a pension, while at the same time levying inheritance tax on other bequests’ (Adam and Waters, 2018).
In this context, it is peculiar that while there are often proposals to reform the taxation of pensions, as summarised in Mirza-Davies and Keep (2022), these typically focus on the tax treatment of pension contributions, the annual and lifetime allowances, and the ability to withdraw up to 25% of an accumulated pension free of income tax. Getting these right is undoubtedly important, and will be the subject of a forthcoming IFS report, also funded by the abrdn Financial Fairness Trust as part of the same project on the taxation of pensions as this report. But getting right how funds remaining in pensions at death are treated by the tax system is also important and is too often ignored. This report seeks to redress that.
The reforms we propose would, on their own, increase both inheritance tax and income tax. A government that did not want to increase the overall burden of these taxes could use the resulting revenues to increase the thresholds and/or cut the rates of those taxes. Combined, this would improve the economic efficiency and fairness of the tax system. Alternatively, increased revenues from income tax and inheritance tax could be usefully deployed elsewhere – for example, by a government that wanted to do more to meet growing demands on public services, not least on the NHS and adult social care.
Section 2 provides a description of how income tax and inheritance tax treat funds remaining in a private pension at death. In Section 3 we set out what a better system of income tax and inheritance tax treatment would look like and what transitional arrangements should be put in place. Section 4 briefly concludes.
2. The current system
This section sets out how income tax and inheritance tax treat funds remaining in a private pension when someone dies.1 Income tax (discussed in Section 2.1) is extremely generous to those who inherit pension wealth from someone who dies before the age of 75. Inheritance tax (discussed in Section 2.2) typically does not apply to any funds still remaining in a pension at death. Together, these two features of the tax system mean that defined contribution private pensions (which typically come with much more flexibility than defined benefit arrangements) are a particularly good savings vehicle for leaving money to children and other heirs.
This is rather odd. It means that pensions are actually treated more favourably by the tax system as a vehicle for bequests than they are as a retirement income vehicle. The tax system encourages those with sufficient means to use their non-pension assets rather than their pension to finance their retirement spending. This is not an obscure point – it is widely known and has been for some time. There are many media articles explaining this feature of the system: for example, a Daily Telegraph article from 8 July 2022 entitled ‘How to avoid inheritance tax in the UK – 7 legal loopholes to cut the cost’ listed ‘Stuff your pension full of cash – but don’t spend it’ as one of its recommended strategies.2 And we know from our own conversations with financial advisers that some individuals understand, and are responding to, the incentives that the tax system is providing.
This situation is something that the coalition government in 2010 explicitly stated that it wanted to avoid:
‘the Government does not intend pensions to become a vehicle for the accumulation of capital sums for the purposes of inheritance. The Government will therefore ensure that the tax rate on unused funds remaining on death does not leave open incentives for pension saving to be used to reduce inheritance tax liabilities. The Government will monitor this closely and will take further action if there is evidence of such activity.’
HM Treasury, 2010
The government may or may not have been monitoring this closely, and of course a new government may view this activity differently, but it is clear that such activity is happening, and increasing, and no action has been taken.
The option to use pensions as a vehicle for bequests is of growing importance for two reasons. First, defined contribution pensions have been increasing in prevalence since the late 1980s, with more recent retirees having spent a greater proportion of their working lives in a labour market where such arrangements were common. This matters because defined contribution pensions involve individuals building up pension pots which can potentially be bequeathed, whereas the defined benefit pensions they are increasingly replacing do not.3
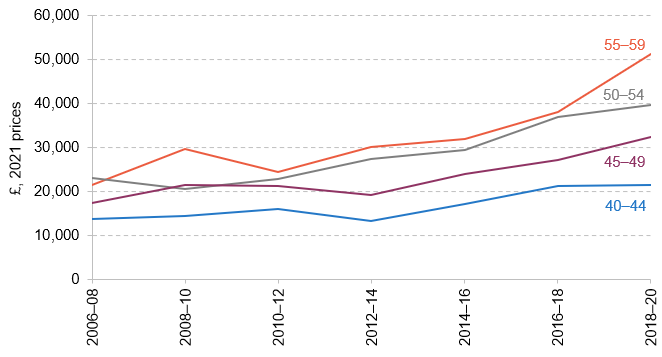
Figure 2.1 shows the average wealth held in defined contribution pensions by age. Particularly for age groups nearing retirement, it shows a substantial increase in the amount of wealth being held in such vehicles in recent years. In 2006–08, for example, on average 55- to 59-year-olds had savings of a little over £20,000 (in 2021 prices) in a defined contribution pension. Just 12 years later, in 2018–20, this had increased to over £50,000. This reflects both an increase in the share of individuals with a defined contribution pension in these age groups and an increase in the average defined contribution pension wealth among those with such a pension. For example, among those aged 55–59, the share with some defined contribution pension wealth increased from 32% to 49% between 2006–08 and 2018–20, while average holding among those with some defined contribution pension wealth increased from £68,000 to £105,000.
Given that inheritance tax is levied only on the estates of a small number of wealthy individuals, it is informative to consider not only the average size of pension pots, but also their importance for those with high levels of wealth. In 2010–12, defined contribution pension pots comprised 15% of the wealth of those aged 45–59 whose total wealth exceeded £500,0004 (in 2021 terms). By 2018–20, this figure had increased substantially to 24%. Interestingly, this reflects not an increase in the average size of pension pots amongst this group, but rather a fall in their average level of non-pension wealth.
Figure 2.1. Average defined contribution pension pots over time, by age group
Source: Authors’ calculations using the Wealth and Assets Survey.
The second reason that the income tax and inheritance tax treatment of bequeathed pensions is becoming increasingly important is so-called ‘pension freedoms’, which were announced by then Chancellor George Osborne in the March 2014 Budget and introduced from April 2015 (HM Treasury, 2014a). These lifted all remaining requirements for those with defined contribution pensions to purchase an annuity (a regular income payable until death) with their accumulated pension pot, thereby increasing the scope for many individuals to retain funds within their pension, including right up until their death.
The numbers annuitising their accumulated defined contribution pension pot have collapsed since the introduction of pension freedoms was announced: data from the Financial Conduct Authority show that 353,000 annuities were purchased in 2013 but this fell to just over 60,000 in 2020–21 (Pensions Policy Institute, 2022). Assuming that annuity purchases remain low, over time this will lead to increasing numbers of individuals dying with pension pots that they can bequeath. In fact one might expect most defined contribution pensions not to be fully exhausted before death. This would happen even without deliberate inheritance tax planning by individuals: people do not know when they will die, so someone gradually drawing money from their pension pot in retirement (rather than using it to buy an annuity) and trying to spread the money over their remaining life might well die with some money left in their pension pot, and cautious individuals – as well as those unfortunate enough to die unexpectedly young – are (all else equal) likely to bequeath more. But the tax incentives to leave the pension pot intact as far as possible will discourage the purchase of annuities and will increase the amount of pension wealth bequeathed. It is clear that both the scope for, and the interest in, bequeathing pension pots are growing.
2.1 Income tax treatment of pensions
The income tax treatment of private pension saving is based on a system where contributions are made out of pre-tax income, there is no tax due as any returns accrue, but withdrawals from the pension are subject to income tax. In effect, income tax on earnings paid into a pension is deferred from the time the contribution is made until the time the earnings (along with any returns accrued in the meantime) are withdrawn from the pension. It is as if individuals, rather than receiving their earnings in full now, agree to get part of their earnings in future instead, and income tax is levied when that deferred remuneration is actually received. Such treatment of pension saving has many advantages (Emmerson, 2014), although allowing most high and moderate earners to reduce their lifetime income tax bills by shifting taxable income from working life into retirement – smoothing it across years – is not without its critics (Johnson, 2013).
There are some exceptions to this income tax treatment. Perhaps the most widely known – and certainly the aspect that is relevant to the most people – is that up to one-quarter of an accumulated pension pot can be taken from the pension free of income tax (thus escaping income tax altogether, since the money paid into the pension was not taxed). This feature (as well as the opportunity to shift taxable income into retirement, as mentioned above, and the fact that employers’ contributions to pensions escape both employer and employee National Insurance contributions completely5) provides a strong financial incentive for many to save for retirement in a private pension rather than in some alternative forms such as an Individual Savings Account (ISA).
There are limits on the amount that can be contributed to a pension each year (the annual allowance) and the total amount that can be held in a pension (the lifetime allowance) before income tax charges apply. These limits are currently set (for most people) at £40,000 and £1,073,100 respectively. While most people are not affected by either of these limits, they are considerably less generous than they were in 2010, leading to the numbers who are affected by them growing substantially over time.
Income tax treatment of pensions at death
The focus of this report is what happens to funds that remain in a pension when an individual dies.
Prior to April 2015, there was no income tax due in cases where the individual died before the age of 75 and had not touched their pension. Where the person died at age 75 or over, or where they died younger but had already started to draw their pension, there was an income tax charge of 55% on the remaining pension pot. This 55% rate may seem high but in 2011 was justified by the government on the basis that these funds were not subject to inheritance tax (which these typically high-wealth individuals’ estates would be more likely to attract).6 This is particularly important: the 55% charge was intended (at least for those dying at or beyond age 75) to make up for the absence of both income tax and inheritance tax on pension pots, a feature we return to in the next section.
In April 2015, the exemption from any income tax was extended to all pension pots of those dying before the age of 75 (rather than just pension pots that had not yet been touched). In addition, in an announcement made by Mr Osborne at the end of his speech at the 2014 Conservative Party conference,7 the 55% income tax charge on the remaining pension pots of those dying at 75 or over was abolished from April 2015. Instead, those receiving these funds would pay income tax at their marginal rate. At the time of the announcement, this change was costed by the Treasury at £150 million a year (HM Treasury, 2014b).
The result is a system where, if an individual dies before age 75, any funds remaining in their pension escape income tax entirely (i.e. income tax relief is given on contributions and not levied on withdrawals), whereas if an individual dies at age 75 or older the beneficiaries of any inherited pension pots will pay income tax on those funds as they are withdrawn (so income tax relief is given on contributions and income tax is levied at the marginal income tax rate of the beneficiary of the pension when the funds are withdrawn).8
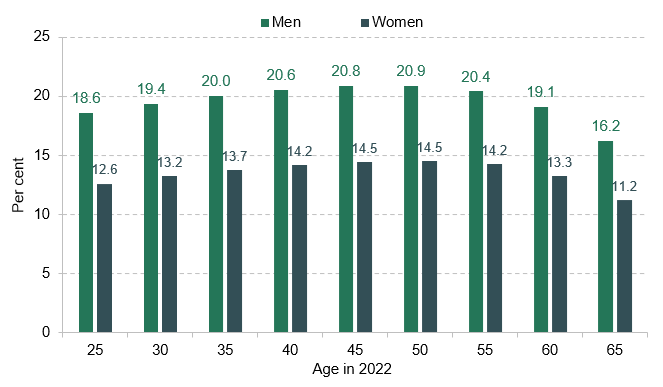
In practice, most individuals in the UK will live beyond age 75, and any funds remaining in their private pension at death will therefore not escape income tax entirely. Figure 2.2 shows the percentage of men and women who are expected to die before their 75th birthday by their current age (in 2022). These are based on cohort life expectancies, which means that they take into account forecast changes in mortality in future years. Among those in their 30s, 40s and 50s, around 20% of men and 14% of women are expected to die before their 75th birthday. Because wealthier individuals live longer, on average, the proportion of those with substantial defined contribution pension pots dying before their 75th birthday is likely to be somewhat lower.
Figure 2.2. Projected shares of men and women dying before age 75, by current age and sex
Source: Authors’ calculations using data from the 2020 UK life tables from January 2022.
The fact that only a minority of bequeathed pension pots will escape income tax entirely does not provide a justification for the tax exemption. Moreover, it creates a very obvious inequity between those inheriting a pension pot from someone who dies just before versus just after their 75th birthday. For someone who is always a basic-rate taxpayer inheriting a £100,000 pension pot, the difference in income tax would be at least £20,000. Much bigger differences exist for those paying higher rates of income tax and those receiving bigger pension pots: for example, for someone who is always a higher-rate taxpayer receiving a £1,000,000 pension pot, the difference in income tax between whether the deceased died just before or just after their 75th birthday would be (at least) £400,000. The fact that men of all the ages shown are (on average) about 45% more likely to die before they reach their 75th birthday also means the policy is – in a rather odd way – more generous on average for men making bequests than for women.
2.2 Inheritance tax treatment of pensions
Inheritance tax is levied on the value of an individual’s estate when they die. It is charged at a rate of 40% on the value of estates worth over £325,000. There are a number of exemptions. One is that transfers to a spouse or civil partner are exempt, and (since October 2007) any unused allowance can also be bequeathed to them at this point. Another is that the value of a main residence (or a previously sold main residence, if higher) – up to £175,000 – is also exempt from inheritance tax, and again any unused portion of this can be bequeathed to a spouse or civil partner.9 Overall these rules mean that most single people’s estates will only attract inheritance tax if they are worth more than £500,000 and most couple’s estates will only be taxed if worth more than £1,000,000.
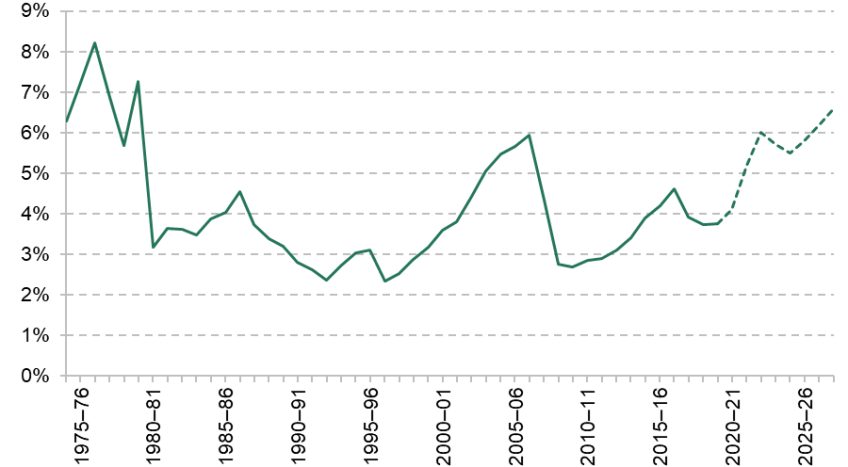
Figure 2.3. Share of estates at death liable for tax over time
Note: Includes estate duty and capital transfer tax, the predecessors of inheritance tax.
Source: Estimates/forecasts for 2020–21 onwards from OBR, Economic and fiscal outlook – November 2022, supplementary fiscal table 2.13. Figures for 2012–13 to 2019–20 from HMRC Statistics table 12.3b. Figures for earlier years calculated using the number of tax-paying death estates from HMRC Statistics, Numbers of taxpayers and registered traders (years from 2002–03 onwards at https://www.gov.uk/government/statistics/numbers-of-taxpayers-and-registered-traders, earlier years from the equivalent table in the National Archives at https://www.webarchive.org.uk/wayback/archive/
20131109170354/https://www.gov.uk/government/publications/numbers-of-taxpayers-and-registered-traders), and the number of deaths from ONS, Deaths registered by single year of age, UK, estimating the number of deaths in each tax year as a weighted average of the number of deaths in the two calendar years it spans.
As a result, only a small minority of estates are liable for inheritance tax at death, as shown in Figure 2.3. Over the 11 years from 1996–97 to 2006–07, it increased from 2.3% to 5.9%. It then fell sharply to below 3% in 2009–10 when the ability to bequeath any unused inheritance tax allowance to a spouse or civil partner was introduced and some asset values fell due to the global financial crisis. Since then, the share of estates liable for inheritance tax has again tended to increase, albeit with a decline due to the gradual introduction of the residence nil-rate band from 2017. Having stood at 3.8% in 2019–20, the share of estates liable for inheritance tax has since increased, reaching an estimated 5.2% in 2021–22. The latest forecasts from the Office for Budget Responsibility are for it to continue increasing in subsequent years, reaching 6.6% in 2027–28. While still a small minority of estates, this would be the highest share liable for inheritance tax since its introduction in place of capital transfer tax in March 1986.
Inheritance tax treatment of pensions
The crucial feature of inheritance tax with respect to pensions is that, typically, any funds that remain in a pension at death are not subject to inheritance tax.10 Prior to pension freedoms, this inheritance tax break would have been less relevant, as for those dying after annuitising their pension pot there would be no remaining pension pot to bequeath.11 And, as described above, for the vast majority of people (those who had already drawn some of their pension and those who died at age 75 or over) any funds remaining in a private pension at death were subject to a 55% charge on pension withdrawals, with this being explicitly designed in part to make up for the absence of inheritance tax. There was, of course, a considerable tax break to the minority of individuals who died before the age of 75 having not touched their pension (or at least those within that group whose taxable estates might then have been above the inheritance tax threshold) as the 55% charge only ever applied to those who had drawn from their pension or died aged 75 or over.
The shift from defined benefit to defined contribution pensions, pension freedoms and the removal of the 55% charge thus increase the value of this inheritance tax break considerably. Wealthy individuals who have other resources to finance their spending needs can now reduce or eliminate their inheritance tax bill simply by putting as much as possible into a pension pot and then leaving it untouched until death. To give the most extreme example: a married couple who both had pension pots equal to the lifetime allowance (i.e. the maximum amount that can be held in a defined contribution pension before a surcharge is applied, currently set to £1,073,100) could bequeath a total of £3,146,200 without incurring any inheritance tax simply by leaving funds in their private pension and making full use of their inheritance tax thresholds and residence nil-rate band.12 Obviously very few will be wealthy enough to be able to do this; but relative to aggregate inheritance tax receipts it could be a significant issue, since just over half of inheritance tax comes from estates whose value is in excess of £2,000,000 (excluding the value of any remaining pension pot at death).13
As long as funds are not removed from the pension, these advantages can be cumulated across multiple generations as inherited pension pots can continue to be handed on without incurring inheritance tax when each beneficiary in turn dies.
2.3 Revenue implications and timing
The revenue forgone from such generous tax treatment of pensions at death is difficult to estimate. It is likely to be very small at the moment as most deaths are among those who will either have had a defined benefit pension or have purchased an annuity prior to the announcement of pension freedoms in March 2014. But increasingly deaths will occur among those who had defined contribution pensions that they did not annuitise. In addition, since the introduction of pension freedoms and the removal of the 55% tax charge, some individuals will be deliberately saving more in their pension for the purposes of bequests. The forgone revenue is therefore likely to increase rapidly in the coming years. This issue is not unique to the UK: in Australia, for example, while the causes are different, the amount of pension wealth bequeathed at death is projected to increase rapidly in coming decades, with similar concerns expressed that ‘A system meant to fund retirement – not inheritance – is broken. Low-taxed death benefits are the new tax planning nirvana’.14
This means that the fiscal saving from moving to a more efficient and fairer system, even if relatively modest in the near term, could be substantial in the longer term. It also places a premium on announcing any reform quickly. Delaying reform means more people could reasonably argue that they had saved in a pension with the expectation of receiving generous tax treatment at death, and that changes therefore amounted to unfair retrospective taxation. With more at stake, the opposition to such a change could be more vociferous if pursued at a later date. The next section sets out reforms that would lead to a more rational system.
2.4 Summary
The tax treatment of pension pots remaining at death is very, and oddly, generous. The income tax treatment of funds remaining in a pension when someone dies prior to age 75 allows money put into a pension to escape income tax entirely. And funds remaining in a pension pot at death are generally not captured by inheritance tax. This means that pension pots are treated more generously by the tax system as an inheritance vehicle than as a retirement income vehicle. It encourages wealthy individuals to finance their retirement spending by running down their other assets rather than drawing on their pension. And those with sufficient means are free to do this as there is no minimum withdrawal requirement from pensions in the UK (unlike in, for example, some pension arrangements in Australia and the United States). The scope for doing so is increasing over time with the increased prevalence of defined contribution pensions and the introduction of pension freedoms from April 2015.
3. A better system for taxing pensions after death
The principle of how funds remaining in a private pension should be treated at death is straightforward. The starting point should be that income tax is applied when funds are taken from the pension and that funds held in a pension are subject to inheritance tax in the same way as other assets. Any deviations from this should be carefully justified. This section provides more detail on how this could work and how transitional arrangements could operate.
3.1 Where to get to
Income tax treatment of pensions at death
As set out in the previous section, the income tax treatment of private pensions is based on a system where funds are taxed only when they are withdrawn from the pension. This principle should continue to apply when an individual dies; i.e. funds remaining in the pension pot at death should still be subject to income tax. In deciding how best to do this, there are three main questions:
- Should income tax be levied at the point of death (which would presumably be before any inheritance tax was levied) or only when the beneficiary withdraws the funds (which would be after any inheritance tax was paid)?
- What rate of income tax should be applied? For example this could be a flat rate, related to the income / income tax rate of the beneficiary, or related to the income / income tax rate of the deceased before they died.
- Where the deceased has not taken full advantage of being allowed to withdraw one-quarter of the pension pot free of income tax, should the remaining benefit of this relief be applied at death?
The first two questions are intrinsically linked, so we discuss those jointly before turning to the issue of the one-quarter of a private pension that can be withdrawn tax-free.
When should income tax be levied, and at what rate?
Perhaps the most straightforward thing to do would be to extend the current treatment of pension pots when an individual dies aged 75 or over to younger ages: this could be achieved simply by changing age 75 to (say) age 0 in the legislation. The result would be that funds would be transferred to the recipient(s) prior to any income tax being levied. The funds would initially be retained in an account, and when the recipient withdrew money from the account it would be included in their taxable income for that year.
There are two, related, potential criticisms of this approach – and of the current approach when people die aged 75 or over. The first is that, when funds are withdrawn by a non-income-tax-payer, substantial amounts could be withdrawn from bequeathed pension pots without income tax being levied. For example, a 16-year-old who inherited a £62,850 pension pot, who had no other taxable income for the next five years (for example, because they remained in full-time education and did not work part-time) could withdraw the value of the income tax personal allowance each year and therefore enjoy the proceeds of the entire pension pot without paying any income tax. An even more extreme example would be a newborn inheriting £263,970 who (or, in practice, whose parents on their behalf) could then potentially withdraw funds equal to the personal allowance each year over the following 21 years and, assuming they had no other taxable income, pay no income tax at all.15
Of course, something analogous can happen when pension savings are withdrawn within the saver’s lifetime: the saver might withdraw the money over several years as a non-taxpaying pensioner, even if they got relief from basic- or higher-rate income tax when paying the money into the pension. While some find this objectionable, it can be defended as merely allowing the individual to smooth their taxable income over their lifetime, evening out lifetime tax payments between those who have stable incomes and those who have high income in some periods and low income in others. But one might reasonably think differently about an individual smoothing their taxable income over their own life from the idea of smoothing taxable income across generations. It is also not the case that individuals can smooth their taxable income between childhood and adulthood, and it is not clear this should be enabled. One option to limit this would be to set a minimum tax rate on withdrawals, equal to the basic rate of income tax. If this is seen as unfair on non-income-tax-paying adults who were drawing funds from the account, and the concern is primarily about minors inheriting pension pots and withdrawing the money free of tax, the basic-rate minimum tax could be applied only to those making withdrawals under the age of 16 or 18, say.
The second potential criticism of taxing funds when they are withdrawn by the beneficiary is that it would (continue to) allow income tax to be avoided indefinitely simply by keeping the inherited funds untouched in the account – potentially even for several generations. The suggestion above of having a minimum tax rate, equal to the basic rate of income tax, on withdrawals would not address this. But it is not clear whether this is really a problem, as long as the commitment to tax withdrawals is equally long-term. The funds must be withdrawn at some point if they are ever to be used, and at that point income tax would be levied – including on any investment returns earned in the fund in the meantime (thus maintaining the present value of the tax liability). It is also the case that under the proposed reform to inheritance tax that we discuss in this section, these funds would be subject to inheritance tax each time they were passed on.
An alternative to taxing inherited pension pots whenever the money is withdrawn by the beneficiary would be instead to take the investments out of the pensions ‘wrapper’ at the point of death and apply income tax on the withdrawal at that point. There are several ways this could be done:
- Counting it all as the deceased’s income in the year of death would seem harsh. For example, take someone who had been a basic-rate income tax payer throughout their life and died with a £200,000 pension pot. Counting this as all being withdrawn in a single year would mean much of the £200,000 would fall into higher tax bands, leading to between 40% and 45% being paid in income tax – much more than the individual (or perhaps their descendants) would have paid if they had withdrawn the money from the fund gradually.
- One way to avoid this would be to apply the deceased’s marginal income tax rate in the last full financial year, rather than adding the withdrawal to their taxable income in the current financial year. But this has problems, not least as it would strongly encourage individuals to try to keep in lower tax bands in the year before death and might be considered unfair to the heirs of those who were unable to do this.
- A simple compromise could be just to levy income tax at the basic rate on all pension funds that remain at death. But this could lead to complaints that the application of basic-rate income tax to the entire remaining pot would be ‘too high’ for some (as the income tax personal allowance would have allowed them to draw some funds free of income tax) and ‘too low’ for others (as, for example, they would have paid higher-rate income tax on some of the pension).
There are certainly arguments for either approach, i.e. levying income tax either when the beneficiary withdraws the funds or at the point of death. Either would be better than retaining the current system where the pension pots of those dying before age 75 escape income tax entirely. Levying basic-rate income tax on all funds that remain in pensions at death would be straightforward. So would extending the current practice for those who die aged 75 and over to those who die at any age – i.e. always applying income tax when the beneficiary makes withdrawals from the fund. If the latter approach were implemented, it could be combined with a minimum rate of tax on withdrawals, set at the basic rate of income tax, in order to prevent large amounts of funds withdrawn by non-taxpayers, in particular children, escaping income tax entirely.
Should any remaining tax-free withdrawal be applied?
Under the current rules, any unused part of the 25% of a pension that can be withdrawn tax-free cannot be claimed on an inherited pension. This introduces potential inconsistencies. Had the deceased claimed their 25% tax-free withdrawal from the pension the day before they died, no income tax would have been applied. It might therefore be considered fairer to extend this benefit to the beneficiaries of those who had not made full use of the tax-free withdrawal prior to death.
If this were deemed appropriate then it would be relatively straightforward to allow any unused part of the 25% tax-free withdrawal not to be lost at death. If the funds were to be withdrawn from the pension at the point of death, and income tax paid at that point, then this could be done after any remainder of the 25% tax-free withdrawal were claimed. If the pension were instead to be transferred to beneficiaries and only subject to income tax upon withdrawal, there would be a choice. Either beneficiaries could be allowed to take the remainder of the 25% tax-free withdrawal at the point of death (without paying income tax), or all of the funds could remain in the pension and beneficiaries could be allowed to take the remainder of the 25% tax-free withdrawal at their time of choosing. The latter would be more generous as, for example, it would open up the possibility of beneficiaries’ choosing to take the tax-free element in periods when their marginal income tax rate would be higher (as pension savers can when they withdraw the money themselves, of course).
On the other hand, given that the purpose of the tax-free component is to support individuals in retirement, it might be considered perfectly appropriate for any unused tax-free withdrawal to be lost at death. Furthermore, as we will discuss in a forthcoming report, the tax-free lump sum is badly designed (for example, it is of no benefit to those who do not expect to be income tax payers in retirement and of less benefit to those who expect to be basic-rate taxpayers in retirement than to those expecting to pay income tax at higher rates). It could be argued, therefore, that extending the availability of the tax-free withdrawal beyond death would be a step in the wrong direction. It should also be remembered that those receiving the inheritance could – unless they were constrained by annual contribution limits or the lifetime allowance – always respond by increasing their own pension saving, which would allow them to make greater use of the ability to withdraw one-quarter free of income tax in their retirement.
There is an argument in favour of allowing any unused part of the pension that can be taken free of income tax to remain not subject to income tax at death. But given the poor design of the tax-free element, there is also a case for not extending its benefits further and therefore continuing the current practice of not allowing any remaining tax-free withdrawal to be taken at death.
Inheritance tax treatment of pensions
Inheritance tax is not a popular tax (Hedges and Bromley, 2001; Rowlingson and McKay, 2005; Prabhakar, Lymer and Rowlingson, 2017; YouGov, 2015, 2020). There are reasonable arguments both for and against having an inheritance tax,16 but if inheritance tax is in place it should apply evenly across all forms of wealth. Taxing bequests of some kinds of assets but not others will inappropriately distort the forms of wealth that individuals hold and also lead to unfair differences in tax payments according to the forms of wealth that happen to be held by the deceased.
This means that, since we have an inheritance tax, it should apply to funds held in private pensions at death. While this would imply higher tax on some estates, a government that did not wish to increase the burden of inheritance tax overall would be free to use the additional revenue to cut the inheritance tax rate and/or increase the threshold.
Including pension pots in the value of estates to which inheritance tax is applied could be done relatively straightforwardly. There is, however, an interaction with how income tax on any pension pots left at death is to be applied:
- If income tax is levied at death – for example, at the basic rate of income tax, as described above – then this should be deducted first and the pension pot net of income tax should be included in the inheritance tax calculation.
- If funds are to be left in an account for the beneficiary, and income tax only paid when the funds are withdrawn, then inheritance tax would be paid first. This leads to a more complicated situation as in this case an adjustment should be made in the calculation for the fact that the future income tax liability attached to these pension assets makes them less valuable than other assets with the same notional cash value (but on which no subsequent income tax will be due). More specifically, to treat pensions on a par with other assets, this means the taxable estate should only include the value of bequeathed pension wealth net of the value of the expected future income tax liability on it. As the beneficiary’s eventual income tax rate will not be known, perhaps the simplest practical approximation would be to assume that they will pay income tax on the funds at the basic rate (and this approximation would be more accurate in the scenario where a minimum tax rate equal to the basic rate of income tax would be applied). With a 20% basic rate of income tax, this would imply including 80% of the bequeathed pension pot in the estate for inheritance tax purposes. Were any portion of the pension to be allowed to be withdrawn free of income tax, an upwards adjustment in the share of the pension that should be included in the estate for inheritance tax purposes should also be made.17
It is clear that pension pots should be included in the value of estates for the purposes of inheritance tax; where the funds held in these pension pots are to be subsequently subject to income tax, it would be appropriate for 80% of those funds to be counted for inheritance tax purposes.
How many more estates would become subject to inheritance tax?
An obvious question that arises from the proposed inclusion of defined contribution pension pots in the estates of the deceased is how this would impact the number of estates liable for, and the amount of revenue raised by, inheritance tax.
In the short term, it would have very little effect. As discussed above, most of those likely to die soon have defined benefit pensions or have annuitised their defined contribution pension pot, so will not bequeath any pension wealth. The question is how much that might change in future.
Providing a precise answer is not straightforward. Those benefiting from pension freedoms (i.e. those retiring after April 2015) are still relatively young. While survey data can provide us with insights into the wealth holdings of the group retiring shortly after April 2015, it is likely that they will spend or give away at least some portion, and perhaps a large portion, of that wealth before they die. And if – as we propose – taxes on pension pots that remain at death are increased, this would reduce the extent to which some individuals hold wealth in pensions with the intent of bequeathing it at death. Nevertheless, by considering how their inheritance tax liability would be altered by the inclusion of pension pots and assuming that they died without running down their wealth, we can put a rough ceiling on the expected impact of the change. And we can also show how much less would be raised were these pensions run down before death.
Figure 3.1 undertakes this exercise explicitly, showing how the effect of bringing 80% of the value of bequeathed pension pots within the inheritance tax net varies depending on what proportion of people’s defined contribution pension wealth at age 60–64 (likely to be their peak pension wealth) they end up bequeathing. Since we do not know how people’s wealth holdings or the inheritance tax threshold might change in future, we assume that the inheritance tax nil-rate band and the residence nil-rate band are set at a level that would ensure 4% of estates were subject to inheritance tax if pension pots remained untaxed – the average from 2015–16 to 2019–20 and roughly the long-term historical average shown in Figure 2.3.
Figure 3.1. Effects of extending inheritance tax to 80% of the value of pension pots, by amount bequeathed

Note: We calculate the total inheritance tax liability of all individuals aged 60–64 if they were to die with their current levels of non-pension wealth and the levels of defined contribution pension wealth shown, scaling the nil-rate band and residence nil-rate band such that 4% of estates are subject to inheritance tax when defined contribution pension wealth is treated as non-taxable. We assume that the first of a married couple or civil partnership to die leaves all wealth – and transfers their full nil-rate bands – to their spouse/partner. In cases where one member of a married (or civil-partnered) couple is aged 60–64 and the other falls outside this age range, we randomly impute which partner in the couple dies first with 50% probability, taking the mean of 100 random iterations.
Source: Authors’ calculations using the Wealth and Assets Survey Round 6.
Clearly, if people spend or give away all of their pension wealth before death, the reform would raise no additional revenue and the proportion of estates liable for inheritance tax would remain at 4%. At the other extreme, if people bequeathed 100% of their defined contribution pension wealth then taxing 80% of its value would increase the share of estates paying inheritance tax from 4% to almost 5% and increase inheritance tax revenue by about £1.9 billion (in today’s terms),18 from £6.7 billion to £8.6 billion. This increase would be substantial, representing an increase of around a quarter in the scope and yield of inheritance tax. That said, the share of estates paying the tax would remain only a small minority of the total, and – as shown in Figure 2.3 – the UK has seen fluctuations in the share of estates liable for inheritance tax of more than 1% of estates in recent years.
If instead 50% of defined contribution pension wealth were bequeathed then the revenue raised would be halved to £0.9 billion. This highlights that the amount that would be raised is sensitive to the extent to which wealth currently held in defined contribution pensions will remain there at death. It will also depend on how the inheritance tax nil-rate band and the residence nil-rate band are indexed. The calculations above assume they are indexed so that the share of estates subject to inheritance tax, prior to any reform, remains at the long-run historical average. If instead they were indexed in line with inflation, this would imply less generous allowances and increase the amount that would be raised from bringing 80% of the value of bequeathed pension pots within the inheritance tax net. In this case, the amount of revenue raised in steady state by bringing defined contribution pensions into the taxable estate would be around 50% higher than if the threshold were set (as outlined above) to ensure that 4% of estates paid inheritance tax.19 Freezing allowances – as is current policy through to March 2028 – would increase the revenue raised from this reform even further.
Were a government to do this reform but not wish to increase inheritance tax overall, it could use the revenue to cut the rate of inheritance tax and/or increase the threshold. To give a sense of scale, £1.9 billion would be roughly enough to reduce the rate from 40% to 30%, while £0.9 billion would be roughly enough to reduce the rate to 35%.20
3.2 Transition to a better system
If both income tax and inheritance tax were to be applied to pension pots that remain at death in the way that we recommend, then a decision would need to be made over the appropriate timetable for bringing the reforms in.
We recommend that the government announces the changes as soon as is practical. This would reduce the extent to which individuals will have saved in a pension under the incorrect expectation that they will be able to bequeath these funds under the current generous arrangements. Swift announcement of the reforms – alongside a reasonable time frame for implementation – would ensure that the benefits of the new system were realised quickly – not least through reducing the incentive for people to put money into a pension, and keep it there, as a way of minimising income tax and inheritance tax on funds eventually bequeathed.
A ‘big bang’ approach with swift implementation could, however, be considered unfair on those who had already placed funds in a private pension since the introduction of pension freedoms in 2015 in the expectation that they would be subject to the current (generous) income tax and inheritance tax rules. There would certainly be a degree of retrospective taxation to the proposal – though that is hard to avoid with most tax changes, and certainly those that increase taxes on wealth, without extremely long transitions. The problem could have been avoided if the tax treatment at death had been fixed when pension freedoms were first introduced; but the longer the delay, the worse the problem gets, so if the government wishes to change the system as we propose, the priority should be to announce the reform as soon as possible so that people are no longer making financial decisions under false expectations of the tax implications. Even if announced immediately, some transitional phasing of implementation could be considered appropriate.
A phase-in of the reforms we propose could be implemented relatively easily. It could be done by applying reforms incrementally by year of death. For example, suppose a five-year transition period were deemed appropriate. In year 1, those receiving pension pots from individuals who had died aged under 75 could pay income tax on 20% of the funds that they withdraw (regardless of when they actually draw the funds from their account). For those receiving pension pots from individuals who had died under age 75 in year 2, this could increase to 40%, in year 3 to 60%, in year 4 to 80% and finally, in year 5, to 100%.21 Obviously, faster or slower transition periods could be chosen.
Similarly, in the case of inheritance tax, if 80% of pension pots are eventually to be subject to inheritance tax then for the estates of those dying in year 1, 16% of the pension pot could be included in the estate. For the estates of those dying in year 2, 32% could be included, then 48% in year 3, 64% in year 4, and finally, from year 5, 80%. Again, faster or slower transition periods could be chosen: the right length of transition is a matter of judgement.
Reforms to the income tax and inheritance tax treatment of bequeathed pension wealth should be announced as soon as practical. There would be a degree of retrospective taxation to the proposals, though that is hard to avoid with any change to the taxation of wealth. There is, however, a case for some gradual phasing-in of these reforms over time which, if desired, could easily be done by date of death.
4. Conclusion
Whether by accident, design or inertia, the tax treatment of pension pots at death has – in the age of pension freedoms – become increasingly anomalous. With the amount of wealth held in defined contribution pensions increasing year-on-year, and with well-understood incentives for those who can afford it to ‘stuff your pension full of cash – but don’t spend it’, this is a problem that will only get worse. Without reform, pensions will increasingly come to serve not just as a means of funding retirement, but also as a vehicle for the wealthiest households to reduce their inheritance tax liability.
A sensible set of reforms would include pension pots in the value of estates for the purposes of inheritance tax and extend current income tax practice for those who die aged 75 and over to those who die at any age. This would leave the tax system both fairer and more economically efficient. It is not yet too late to act, but the longer the government delays, the more painful such reforms will become. The Chancellor has a great deal on his plate, but failure to embrace reform now will leave a legacy for which his successors will not thank him.
References
Adam, S. and Waters, T., 2018. Options for raising taxes. In C. Emmerson, C. Farquharson and P. Johnson (eds), The IFS Green Budget: October 2018. https://ifs.org.uk/books/options-raising-taxes.
Boadway, R., Chamberlain, E. and Emmerson, C., 2010. Taxation of wealth and wealth transfers. In J. Mirrlees et al. (eds), Dimensions of Tax Design: The Mirrlees Review, Oxford: Oxford University Press.
Bullock, C., 1716, The Cobler of Preston. https://archive.org/details/coblerofprestonf00bull/page/21/
mode/2up?ref=ol.
Cremer, H. and Pestieau, P., 2006. Wealth transfer taxation: a survey of the theoretical literature. In L-A. Gérard-Varet, S-C. Colm and J. Mercier Ythier (eds), Handbook of the Economics of Giving, Reciprocity and Altruism, Volume 2, Amsterdam: North-Holland.
Emmerson, C., 2014. Taxation of private pensions. In C. Emmerson, P. Johnson and H. Miller (eds), The IFS Green Budget: February 2014, https://ifs.org.uk/publications/ifs-green-budget-2014.
Farhi, E. and Werning, I., 2010. Progressive estate taxation. Quarterly Journal of Economics, 125(2), 635–73.
Farhi, E. and Werning, I., 2013. Estate taxation with altruism heterogeneity. American Economic Review, 103(3), 489–95.
Gale, W. and Slemrod, J., 2001. Rethinking the estate and gift tax: overview. In W. Gale, J. Hines and J. Slemrod (eds), Rethinking Estate and Gift Taxation, Washington, DC: Brookings Institution Press.
Hammond, P., 1988. Altruism. In J. Eatwell, M. Milgate and P. Newman (eds), The New Palgrave: A Dictionary of Economics, Basingstoke: Macmillan.
Hedges, A., and Bromley, C., 2001. Public Attitudes towards Taxation: The Report of Research Conducted for the Fabian Commission on Taxation and Citizenship. London: Fabian Society.
HM Treasury, 2010. Removing the Requirement to Annuitise by Age 75. https://assets.publishing.service.gov.uk/government/uploads/system/uploads/attachment_data/file/81232/consult_age_75_annuity.pdf.
HM Treasury (2014a), Freedom and Choice in Pensions.https://webarchive.nationalarchives.gov.uk/ukgwa/
20150130185255/https://www.gov.uk/government/consultations/freedom-and-choice-in-pensions.
HM Treasury, 2014b. Chancellor abolishes 55% tax on pension funds at death. https://webarchive.nationalarchives.gov.uk/ukgwa/20150202200733/https:/www.gov.uk/government/news/chancellor-abolishes-55-tax-on-pension-funds-at-death.
Johnson, M., 2013. Costly and ineffective: why pensions tax reliefs should be removed. Centre for Policy Studies, https://cps.org.uk/research/costly-and-ineffective-why-pension-tax-reliefs-should-be-reformed/.
Kaplow, L., 1995. A note on subsidizing gifts. Journal of Public Economics, 58, 469–77.
Kaplow, L., 1998. Tax policy and gifts. American Economic Review: Papers and Proceedings, 88(2), 283–8.
Kopczuk, W., 2009. Economics of estate taxation: a brief review of theory and evidence. Tax Law Review, 63, 139–57.
Mirrlees, J. et al. (2011), Tax by Design: The Mirrlees Review. Oxford: Oxford University Press.
Mirza-Davies, J. and Keep, M., 2022. Reform of pension tax relief. House of Commons Library, Research Briefing CBP-7505, https://researchbriefings.files.parliament.uk/documents/CBP-7505/CBP-7505.pdf.
Office of Tax Simplification, 2019. Inheritance Tax Review – Second Report: Simplifying the Design of Inheritance Tax.https://www.gov.uk/government/publications/ots-inheritance-tax-review-simplifying-the-design-of-the-tax.
Pensions Policy Institute, 2022. Set for life? Guaranteed incomes in retirement. PPI Briefing Note 130, https://www.pensionspolicyinstitute.org.uk/media/4079/20220526-ppi-bn130-set-for-life-a-guaranteed-income.pdf.
Piketty, T. and Saez, E., 2013. A theory of optimal inheritance taxation. Econometrica, 81, 1851–86.
Prabhakar, R., Lymer, A. and Rowlingson, K., 2017. Does information about wealth inequality and inheritance tax raise public support for wealth taxes? Evidence from a UK survey. In B. Peeters, H. Gribnau and J. Badisco (eds), Building Trust in Taxation, Cambridge: Intersentia.
Retirement Income Review (2020), Retirement Income Review – Final Report, https://treasury.gov.au/publication/p2020-100554.
Rowlingson, K. and McKay, S., 2005. Attitudes to Inheritance in Britain. Bristol: Policy Press.
Seely, A. 2021. Inheritance tax. House of Commons Library, Briefing Paper 93, https://commonslibrary.parliament.uk/research-briefings/sn00093/.
Thurley, D., 2019. Tax treatment of DC pensions on death. House of Commons Library, Briefing Paper CBP7318, https://researchbriefings.files.parliament.uk/documents/CBP-7318/CBP-7318.pdf.
YouGov, 2015. Voters in all parties think inheritance tax unfair. https://yougov.co.uk/topics/politics/articles-reports/2015/03/19/inheritance-tax-most-unfair.
YouGov, 2020. Budget 2020, What tax changes would be popular?. https://yougov.co.uk/topics/politics/
articles-reports/2020/03/10/budget-2020-what-tax-changes-would-be-popular.
Data
Office for National Statistics, Social Survey Division. (2022). Wealth and Assets Survey, Waves 1-5 and Rounds 5-7, 2006-2020. [data collection]. 17th Edition. UK Data Service. SN: 7215, http://doi.org/10.5255/UKDA-SN-7215-17
Acknowledgements
The abrdn Financial Fairness Trust has supported this project (grant reference 202107-GR000046) as part of its mission to contribute towards strategic change which improves financial well-being in the UK. Its focus is on tackling financial problems and improving living standards for people on low-to-middle incomes. It is an independent charitable foundation registered in Scotland. Co-funding from the ESRC-funded Institute for the Microeconomic Analysis of Public Policy at IFS (grant number ES/T014334/1) is also gratefully acknowledged. The authors would like to thank Mubin Haq, Paul Johnson and Helen Miller for comments on this report, and members of the project advisory group – and the many others that we consulted for this report – for their advice and support. None of these individuals or organisations bears any responsibility for the views expressed in this report, which – along with any errors and omissions – are those of the authors alone.
Where an individual dies before age 75, funds remaining in their pension escape income tax entirely – there was income tax relief when the money was paid into the pension and no income tax when the money is taken out. Furthermore, any funds that remain in a pension at death (at any age) are not subject to inheritance tax. This results in the bizarre situation where pensions are treated more favourably by the tax system as a vehicle for bequests than they are as a retirement income vehicle. As such, there is a large incentive, for those who can, to use non-pension assets to fund their retirement while preserving their pensions for bequests.
This report sets out some options for a more coherent tax treatment of funds that remain in a pension at death. The reforms we propose, potentially with some transitional arrangements, would make the tax system fairer and more economically efficient. The revenue raised by moving to a more sensible system, even if relatively modest in the near term, could be substantial in the longer term. This revenue could be used to cut taxes elsewhere – including income tax and inheritance tax – or to ease the planned squeeze on public spending.
Key findings
1 Pensions are being increasingly used as a vehicle for bequests. Growth in defined contribution pensions along with the introduction of ‘pension freedoms’ would lead to more pension wealth being bequeathed at death even if people did not respond to the strong tax incentives to use pensions for bequests. Pensions and wealth-management professionals are fully aware of these tax benefits which, increasingly, are also being reported in the press. If nothing changes, more people will respond to the incentives the tax system creates.
2 Basic-rate income tax could straightforwardly be levied on all funds that remain in pensions at death. Alternatively, current income tax rules could extend to those inheriting pension pots from someone who dies before age 75. This would mean levying income tax when the person inheriting the pension pot withdraws the funds from it regardless of the age of death of the deceased. This could be combined with a minimum rate of income tax on withdrawals, set at the basic rate of income tax, in order to prevent funds withdrawn by non-income-tax-payers, in particular children, escaping income tax entirely.
3 Pension pots should be included in the value of estates at death for the purposes of inheritance tax. If we are to have an inheritance tax at all, it should apply evenly across all forms of wealth. Where the funds held in pension pots are to be subsequently subject to income tax – reducing their effective value – it would be appropriate for 80% of these funds to be counted for inheritance tax purpose.
4 Subjecting pensions to inheritance tax would raise revenue and remove the perverse incentive to avoid using a pension to fund retirement. Short-term revenue would be limited because few of those dying today are bequeathing pension pots. But if the generation benefiting from pension freedoms – those retiring after April 2015 – were to die with their full pension pots intact, we estimate that it would raise the equivalent of £1.9 billion a year (in today’s terms) in extra inheritance tax revenue. This increase would be substantial, representing an increase of around a quarter in the scope and yield of inheritance tax. The yield is very sensitive to the extent to which pensions will be run down before death: were half of current pensions intact at death, the yield would fall to £0.9 billion.
5 If the government did not want this change to increase the overall yield of inheritance tax, it could use the revenue to cut the inheritance tax rate and/or increase the threshold. To give a sense of scale, £1.9 billion would be roughly enough to reduce the rate from 40% to 30%, while £0.9 billion would be roughly enough to reduce the rate to 35%.
6 Reforms should be announced as swiftly as is practical. This would reduce the extent to which individuals will have saved in a pension in the incorrect expectation that they will be able to bequeath these funds under the current generous arrangements. As with any reform to wealth taxes, some retrospective taxation would be inevitable. If some transitional phasing of implementation were deemed appropriate, it would be straightforward for both the income tax and inheritance tax reforms we propose to be gradually introduced by date of death.
Endnotes
Authors

Stuart Adam
Stuart is a Senior Economist working in the Tax sector, and focuses on analysing the design of the tax and benefit system.

Isaac Delestre
Isaac is a Senior Research Economist in the Taxation sector, focusing on the taxation of high-income individuals and closely-held corporate entities.


More from IFS
Understand this issue


Policy analysis


Academic research


